

US Market Brief — Jul 16, 2026 | Futures, movers & what to watch
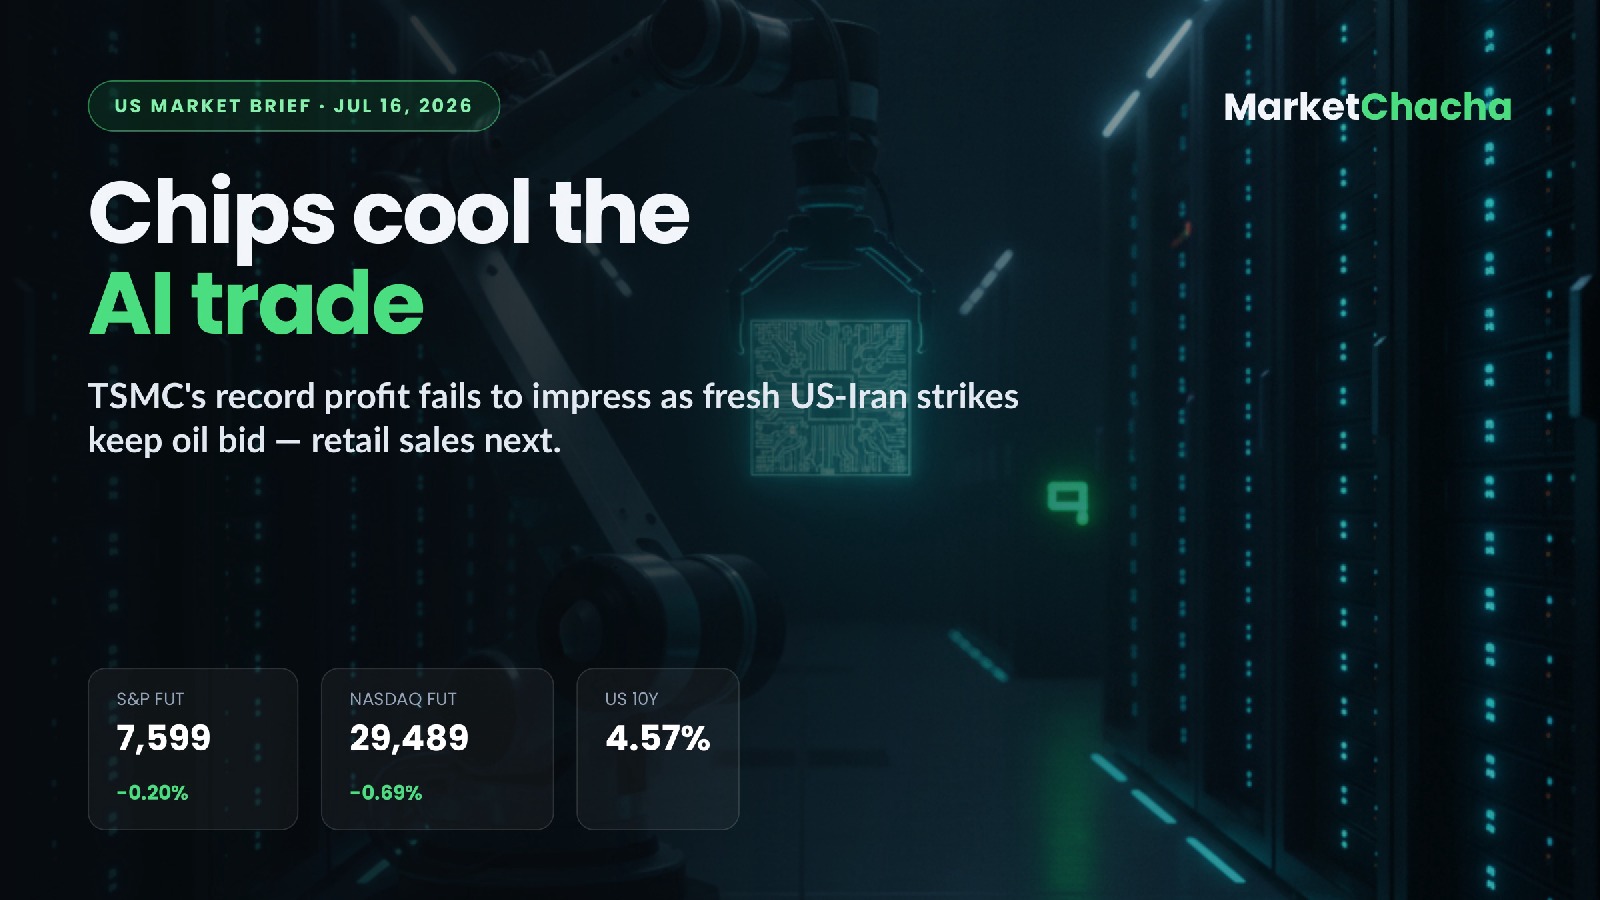
US futures are split early Thursday: the Dow edges up while the Nasdaq lags for a second day as the AI/chip trade cools after TSMC's record quarterly profit failed to impress, and a fresh US escalation against Iran keeps oil bid ahead of the June retail sales report.
Futures now
Per Yahoo Finance, Dow futures were up about +0.2% (~53,011), S&P 500 futures roughly flat at -0.2% (~7,599) and Nasdaq-100 futures down -0.7% (~29,489). Small-caps (Russell 2000) fell ~0.4% and the VIX ticked up ~2% to ~16. The single biggest overnight driver is a second-day pullback in semiconductors layered over renewed Middle East risk.
Pre-market movers
- TSMC (TSM) slipped pre-market despite a record Q2 profit and a lifted capex/investment plan — a cautious tone on pricing dented the AI-demand read, per Benzinga. Chip and memory peers (Nvidia, AMD, SanDisk) stayed soft for a second session.
- Apple (AAPL) hit a record high on Wednesday, helping cushion the Dow.
- UnitedHealth (UNH) and GE Aerospace (GE) report before the bell; Netflix (NFLX) headlines after the close, with options implying a ~±8% swing.
Earnings today
Before the open: TSMC (reported), UnitedHealth, GE Aerospace. After the close: Netflix — the first Big-Tech-adjacent read of the season. Bank and industrial earnings continue to ramp through the week.
Macro today (ET)
- 8:30 — Retail sales (June): consensus +0.2% m/m vs +0.9% prior; ex-autos -0.1% vs +0.8%. A soft print would stoke hard-landing worries; in-line would reinforce hopes for autumn Fed cuts.
- 8:30 — Initial jobless claims: consensus ~216k vs 215k prior — a labor-market pulse check.
- 8:30 — Philadelphia Fed manufacturing (July): consensus ~13 vs 10.3 prior; a beat signals firmer factory activity.
- 10:00 — Business inventories (May) +0.3% expected; NAHB homebuilder index (July) seen steady at 35.
- 10:30 — EIA natural gas storage.
- Fed speakers: Lorie Logan (~12:30pm) and Jeffrey Schmid (~1:25pm). No CPI/PCE or FOMC today — CPI landed earlier this week.
Rates, dollar & commodities
The US 10-year yield sat near 4.57% (down ~6bp Wednesday from a two-month high ~4.62%), easing borrowing-cost pressure. The dollar index (DXY) was ~100.7, off ~0.4%. Brent traded ~$84.6/bbl and WTI ~$79.5 — cooling after an early rally but still near a one-month high on Strait of Hormuz risk. Gold held above $4,000 at ~$4,034 (Yahoo/Trading Economics).
Overnight global
Asia was mixed-to-soft on the chip drag and Europe traded lower. In the UK, May GDP came in at +0.1% m/m (in line) with stronger manufacturing, nudging the pound higher — a mild risk-neutral backdrop for the US open.
What to watch at the open
The 8:30 retail sales print is the swing factor: a weak consumer read would test the soft-landing narrative, while an in-line number keeps rate-cut hopes intact. Watch whether chip weakness broadens or whether the Dow and value names keep the indices afloat, and track oil/Hormuz headlines for risk appetite. Netflix after the close then sets the early tone for tech earnings.
As of 9:10 AM ET. Sources: Yahoo Finance, XTB, Benzinga, Trading Economics, Investing.com. Automated US market brief for discussion and education only — not investment advice. Verify before acting.
This article is for educational and informational purposes only. It is not financial advice, investment recommendation, or a solicitation to buy or sell securities. Investing involves significant risks. I am not a SEBI-registered investment advisor. Readers should consult their own financial advisor and conduct their own research before making any investment decisions.
Comments
Join the conversation
Sign in to join the conversation.
Follow replies, add your view, and take part in the discussion.
Sign in to commentLoading comments...