

Pre-Market Global Brief — Aug 03, 2026 | Nifty, Nasdaq, Nikkei, DAX & more
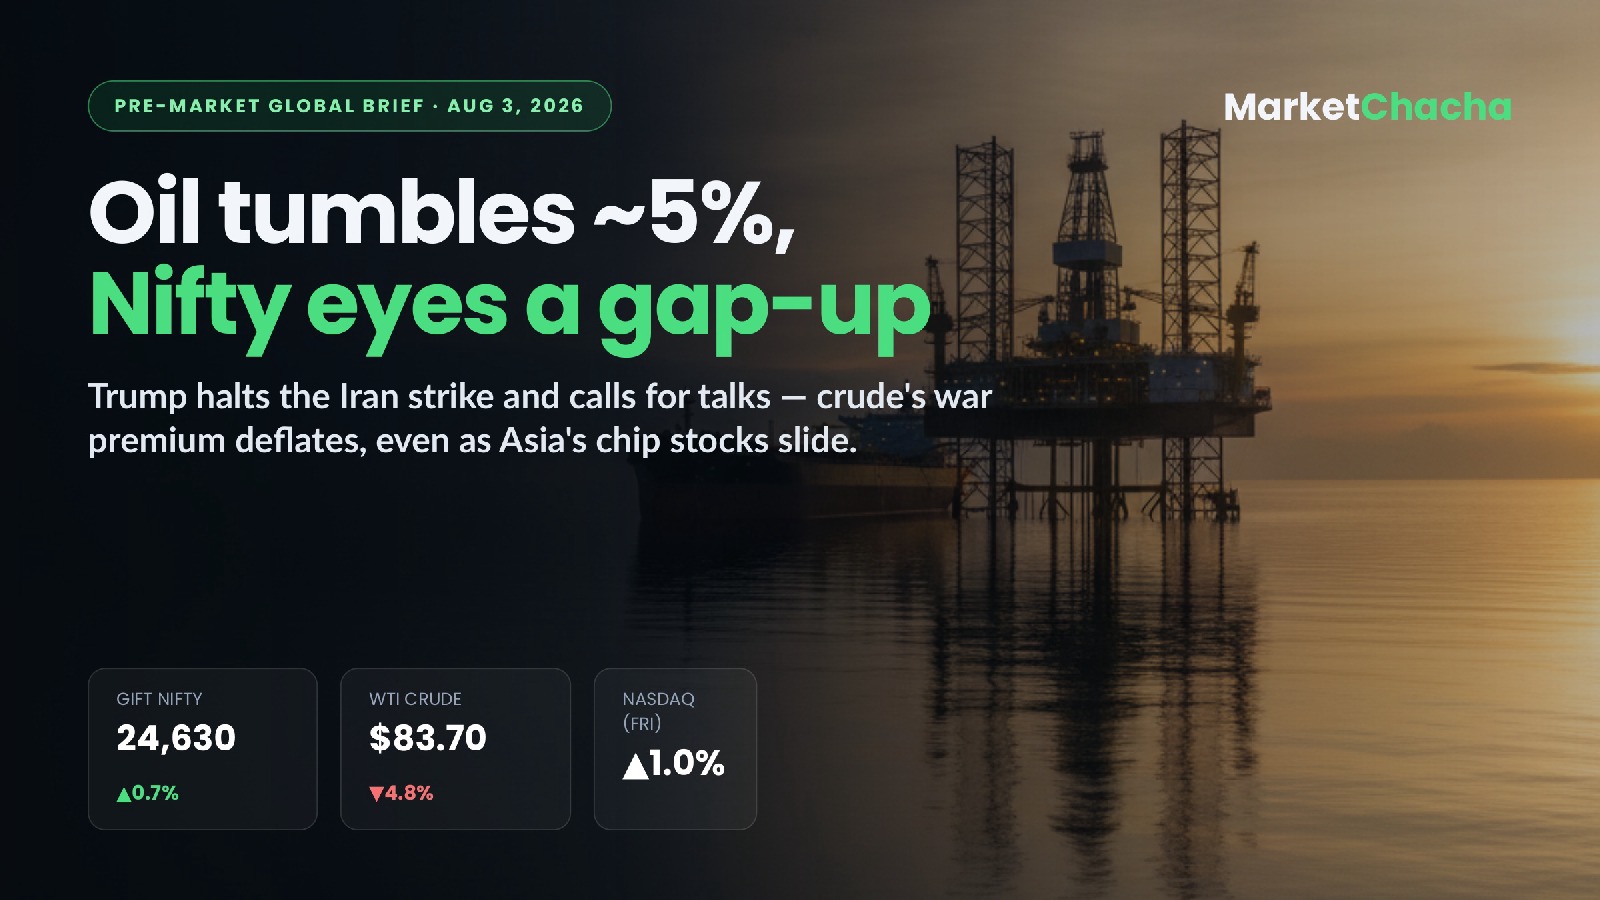
Wall Street ended Friday firmer and US stock futures are up this morning, but the single biggest driver for Dalal Street is a near 5% crash in crude oil after President Trump shelved a strike on Iran and said US–Iran talks begin today. GIFT Nifty points to a firm, gap-up open even as Asia's chip-heavy markets sell off.
US prior close (Friday)
The Dow rose 0.53% to about 52,485, the S&P 500 gained 0.70% to roughly 7,490, and the Nasdaq Composite led with +1.0% near 25,374 as chip names rallied (as reported by Business Standard and 24/7 Wall St.).
Asia now — chip-led retreat
Most Asian markets are lower this morning: South Korea's Kospi is down over 4% (leading losses), Japan's Nikkei 225 -1.84% and Hong Kong's Hang Seng -3.9%, dragged by a pullback in semiconductor and AI-linked stocks after a long rally (per Business Standard).
Europe (Friday close)
Europe eased off record highs: the STOXX 600 slipped 0.1% to 649, the Euro STOXX 50 held +0.2% near 6,360, while London's FTSE 100 fell 0.3% and the DAX dipped 0.15% (as reported by U.S. News/Reuters).
India lead — GIFT Nifty
GIFT Nifty was quoted around 24,630, up ~176 points near 8:24 AM IST, signalling a positive/gap-up start for the Nifty50 (per Business Standard).
Commodities, currency & yields
- Crude: US WTI August futures ~$83.70, down ~4.8%; Brent off ~5% — Trump dropped plans to strike Iran, said talks start today and a Strait of Hormuz deal is "imminent" (Iran has denied a reopening deal, so headline risk remains).
- Gold: futures firmer (~+0.2%), spot near the $4,050/oz zone (as reported).
- Rupee & dollar: USD/INR near 95.6 (latest reported, close to record lows); the Dollar Index (DXY) around 100.9.
- US 10Y yield: ~4.73% Friday, highest since Jan 2025; the Fed remains on hold at 3.50–3.75% (Trading Economics/FXStreet).
Global sentiment
Mixed: risk-on for India on cheaper oil, but risk-off in Asian tech. Lower crude deflates the war-risk premium that had built through late July.
Economic data due today
US: ISM Manufacturing PMI (July) at ~7:30 PM IST, prior 53.3 — a beat signals US industrial strength (mildly dollar-supportive); S&P Global US Manufacturing PMI (final) also today. India: S&P Global India Manufacturing PMI (July) is due today; a strong (>55) print underscores domestic demand and is a tailwind for cyclicals. Already on the tape: July GST at ₹2.11 trillion (+15.4% YoY), and monthly auto sales (Maruti, Tata Motors, M&M) digested over the weekend.
Headlines & movers
Iran rejected Trump's Hormuz-reopening claim (oil headline risk); India–China border trade via Shipki La resumed after six years. Q1 results today: CAMS, Escorts Kubota, GSK Pharma, JM Financial, KEI Industries. Muthoot Finance Q1 profit jumped 43% to ₹2,825 cr. Manipal Health lists today (IPO subscribed 5.12x); Juniper Green Energy's ₹1,800-cr IPO is live. Watch Maruti, ITC, Vodafone Idea and auto names.
What it means for the India open
Cheaper crude is an outright positive for India — a lighter import bill, softer inflation risk and relief for oil marketers, paints, aviation and the rupee — which is why GIFT Nifty leans to a gap-up despite Asia's tech-led weakness. Watch whether Nifty holds early gains against the regional risk-off, and any fresh Iran headlines that could snap oil's move. OMCs, paints and rate-sensitives look best placed; IT and chip-linked names may track Asia's caution.
As of ~8:46 AM IST, Aug 3, 2026. Sources: Business Standard, U.S. News/Reuters, Trading Economics, FXStreet, Investing.com. Automated pre-market brief for discussion and education only — not investment advice. Verify before acting.
This article is for educational and informational purposes only. It is not financial advice, investment recommendation, or a solicitation to buy or sell securities. Investing involves significant risks. I am not a SEBI-registered investment advisor. Readers should consult their own financial advisor and conduct their own research before making any investment decisions.
Comments
Join the conversation
Sign in to join the conversation.
Follow replies, add your view, and take part in the discussion.
Sign in to commentLoading comments...