

Pre-Market Global Brief — Sep 07, 2026 | Nifty, Nasdaq, Nikkei, DAX & more
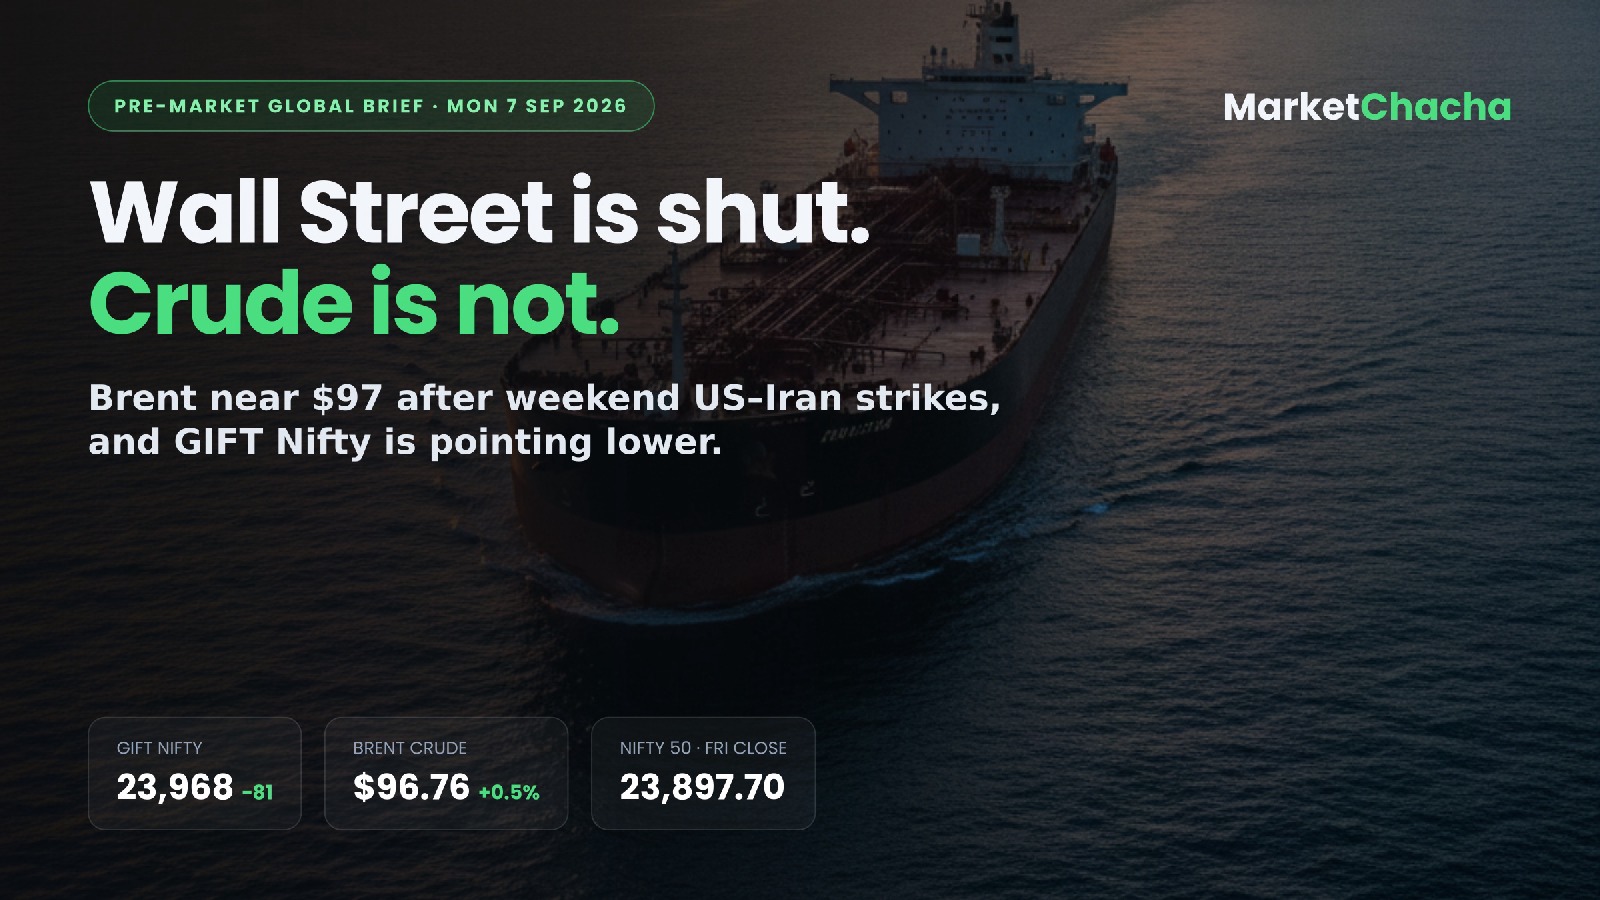
Asia is rallying hard but India is not invited yet — Wall Street is shut for Labor Day and Brent is back near $97 after weekend US–Iran strikes, leaving crude, not equities, as the biggest swing factor for today's open.
Wall Street: closed today, soft on Friday
US stock and bond markets are closed Monday for Labor Day (Kiplinger) — no fresh Wall Street lead, and volumes may thin out. Friday was mildly negative: Dow −0.51%, S&P 500 −0.38%, Nasdaq −0.29%, per TheStreet. The trigger was a blowout August jobs report — 162,000 payrolls vs a ~55,000 forecast, unemployment steady at 4.1% — pushing traders to price a Fed hike, not a cut. Trading Economics puts the 10-year Treasury yield at 4.79%, with roughly a 52% chance of a 25bps increase this month.
Asia now, Europe last
- Nikkei 225 up ~2.2%, Kospi up ~3.0% this morning (Business Standard) — a tech-and-chips bid on top of Friday's 65,021 and 6,687.21 closes (Trading Economics).
- Friday in China/HK: Hang Seng 25,651 (+1.74%), Shanghai Composite 3,930.12 (−0.30%).
- Europe finished Friday flat-to-firm: DAX 26,046.40 (+0.17%), FTSE 100 10,831.09 (unchanged), Euro Stoxx 50 6,401 (+0.34%) — with the ECB widely expected to hike 25bps next meeting.
India lead: GIFT Nifty points down
Business Standard reports GIFT Nifty near 23,968, down about 81 points, signalling a soft start. Friday's close: Nifty 50 23,897.70 (+0.10%), Sensex 76,515.43 (+362.57 pts, +0.48%), Bank Nifty 57,369.65 — the Sensex snapping a four-day losing run. Goodreturns flags support at 23,800–23,600, resistance at 23,990 and 24,070.
Commodities, currency, yields
- Brent $96.76 (+0.5%), WTI $92.02 (+0.59%) this morning (Trading Economics) — the US and Iran exchanged strikes over the weekend, with a US naval blockade and a proposed Iranian "restricted" zone near the Strait of Hormuz. Brent is up ~10% in a month.
- Gold $4,424.83/oz (−0.92%) as the jobs print lifted the dollar.
- USD/INR 94.38 at Friday's mark; dollar index 99.13. Forex reserves rose to $740.8bn (week to Aug 28) from $729.33bn.
Data due — and what it means
A light day: no India releases and no US prints (holiday). Overseas, per Trading Economics: German industrial production (Jul, f/c +0.3% MoM vs +0.2%), Euro Area Q2 GDP third estimate (f/c +0.4% QoQ / +1.0% YoY), UK Lloyds house prices, and overnight Japan average cash earnings (Jul, f/c +3.9% YoY vs +3.4%) plus Korea's final Q2 GDP. Hot Japanese wages would harden BoJ hike bets and lift global yields — a headwind for Indian rate-sensitives. The real India tests land Sept 14 (CPI f/c 4.7% vs 4.45%; WPI f/c 10.0% vs 9.78%) and Sept 15 (trade deficit f/c −$31.98bn, August passenger vehicle sales). With crude near $97, an upside CPI surprise pushes RBI-cut hopes further out.
Stocks in focus
- ICICI Bank / LIC — RBI has approved LIC acquiring up to a 9.99% stake in ICICI Bank.
- Tata Motors — all-cash tender offer for Iveco Group at €14.10 a share, valuing it near €3.82bn.
- TCS — HyperVault has secured 264 acres in Hyderabad for an AI data centre, potential investment about ₹70,000 crore.
- SAIL / JSW Steel — August crude steel output up 8% YoY to 1.68 MT and 3% to 24.65 lakh tonnes.
- IPOs — Pranav Constructions (₹351 crore) and Apana Logistics (₹34 crore) open; Purple Style Labs lists with GMP at ₹565 against a ₹575 issue price, i.e. a discount.
What it means for the India open
Expect a soft, choppy start rather than a directional one: GIFT Nifty points lower, the US is absent, and $97 Brent is a live import-bill and inflation problem. Oil marketing companies, paints, tyres and aviation stay under pressure, while metals and exporters get some cover from the Asian tech bid. Watch 23,800 — losing it opens 23,600.
As of 8:45 AM IST, 7 September 2026. Sources: Business Standard, TheStreet, Trading Economics, Kiplinger, Goodreturns. All prices and index levels are as reported by these publications, not live exchange data. Automated pre-market brief for discussion and education only — not investment advice. Verify before acting.
This article is for educational and informational purposes only. It is not financial advice, investment recommendation, or a solicitation to buy or sell securities. Investing involves significant risks. I am not a SEBI-registered investment advisor. Readers should consult their own financial advisor and conduct their own research before making any investment decisions.
Comments
Join the conversation
Sign in to join the conversation.
Follow replies, add your view, and take part in the discussion.
Sign in to commentLoading comments...