

US Market Brief — Sep 17: chips lead futures ~1% higher as 10Y eases to 4.95%
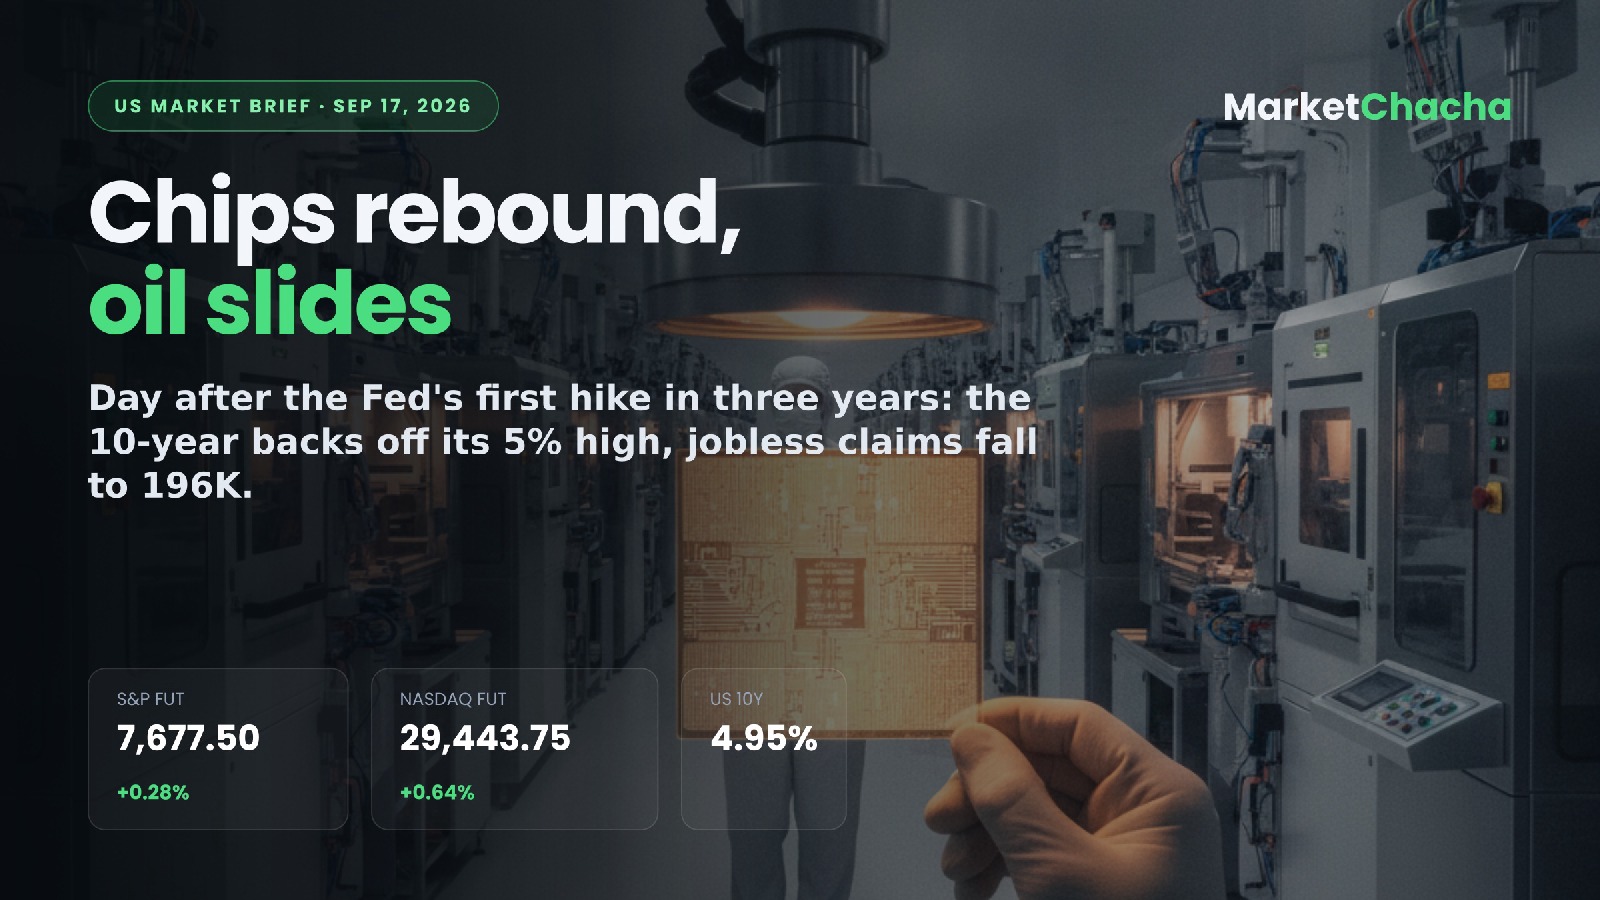
A day after the Fed's first rate hike in three years, the mood has flipped: US futures point higher as Treasury yields back off multi-decade highs and oil extends a sharp slide, letting beaten-up chip stocks lead a broad pre-open bounce.
Futures now
Trading Economics reports S&P 500, Nasdaq 100 and Dow contracts all around 1% higher, erasing two sessions of losses; index ETF proxies were up 1.16%–1.60% against Wednesday's close (StockAnalysis.com). The driver is the bond market. The FOMC raised the fed funds target 25bp to 3.75%–4.00% in a unanimous vote — its first hike since July 2023 — and Chair Kevin Warsh reaffirmed the inflation fight without triggering a fresh yield spike.
Pre-market movers
Semis are doing the heavy lifting after this week's AI-capex scare (StockAnalysis.com, ~9:12 AM ET):
- Marvell +4.85%, Lam Research +4.23%, Seagate +4.19%, AMD +4.06%, Intel +3.61%, Broadcom +2.47%, Nvidia +2.15%.
- Hyperscalers follow: Amazon +2.10%, Alphabet +1.41%, Microsoft +0.92%; Tesla +2.06%.
- Generac +33% to ~$233.50 — Investing.com reports a deal to supply backup generators for Amazon's data centres: $2.4bn of initial deliveries in 2027–28, up to $8bn over its life, plus a warrant for Amazon over ~1.69m shares at ~$200.93.
- Fluence Energy −23% on a guidance cut and analyst downgrades.
More at marketchacha.com/movers.
Earnings & IPOs
A thin corporate day: Thursday's reporters are small caps (Rezolute, US Gold, Bridgford), with no S&P 500 name after the close. Yesterday's print was Lennar — Q3 net earnings $284m ($1.19/sh) versus $591m a year ago, new orders −9% to 20,879 homes, homebuilding gross margin 15.8% from 17.5%, FY26 deliveries guided down to 80,000–81,000. Holtec Nuclear (HNUC) and Orion180 Insurance (OIG) are slated to list tomorrow.
Macro today
The 8:30 ET block is already out (Trading Economics):
- Initial jobless claims 196K (week to Sep 12), −10K and well under the ~208K consensus, the lowest since July. Continuing claims 1.730m, the lowest since January 2024.
- Philadelphia Fed manufacturing 37.8 in September, down from 47.4 but far above the ~30.5 consensus; both price gauges rose again.
- Housing starts 1.275m in August, −2.6% m/m, below the ~1.31m forecast; building permits 1.394m, −2.7% m/m, under ~1.41m.
Still due: pending home sales (10:00 ET), EIA natural gas stocks (10:30 ET), the weekly 30-year mortgage rate, a 10-year TIPS auction and bill auctions, and the Fed balance sheet after the close. No Fed speakers scheduled. A tight labour market plus hot Philly Fed prices-paid is the mix that keeps a second 2026 hike live; soft housing is the counterweight. Full calendar.
Rates, dollar & commodities
Per Trading Economics: US 10-year 4.95%, about 7bp lower and back below the 5.04% touched earlier this week (highest since 2007); 2-year 4.68%, 30-year 5.31%. DXY 100.08 (−0.17%), near seven-week highs. Brent $102.31 (−3.33%), WTI $100.26 (−2.12%) after Saudi Arabia signalled progress restoring flows through its East-West pipeline. Gold $4,363/oz (+2.33%).
Overnight global
Asia took the hike well: the Nikkei 225 closed +0.33% at 64,136 and the Topix +0.8% on a weaker yen and cheaper crude, while the Shanghai Composite slipped 0.41% to 3,875.6 before US–China talks ahead of the September 24 Trump–Xi summit. In Europe, the DAX is up ~0.7% above 25,700, the CAC 40 +0.4% at 8,172, and the FTSE 100 +0.5% near 10,750 after the Bank of England held with three MPC members voting to hike.
What to watch at the open
The question is whether the 10-year holds below 5% — that, more than anything, is what has let long-duration tech bid this morning. Watch whether the semiconductor bounce survives the cash session or fades as it did earlier this week, and whether Generac's Amazon contract re-rates the wider data-centre power complex or stays a single-stock story. Housing remains the soft spot against a Fed that has just said it is not finished.
As of 9:18 AM ET. Sources: Trading Economics, StockAnalysis.com, Investing.com, InvestingLive, StockTitan. Figures as reported by those sources. Automated US market brief for discussion and education only — not investment advice. Verify before acting.
This article is for educational and informational purposes only. It is not financial advice, investment recommendation, or a solicitation to buy or sell securities. Investing involves significant risks. I am not a SEBI-registered investment advisor. Readers should consult their own financial advisor and conduct their own research before making any investment decisions.
Comments
Join the conversation
Sign in to join the conversation.
Follow replies, add your view, and take part in the discussion.
Sign in to commentLoading comments...