

Why did AstraZeneca drop ~8% today? A reported $400bn merger with Bristol Myers
What happened
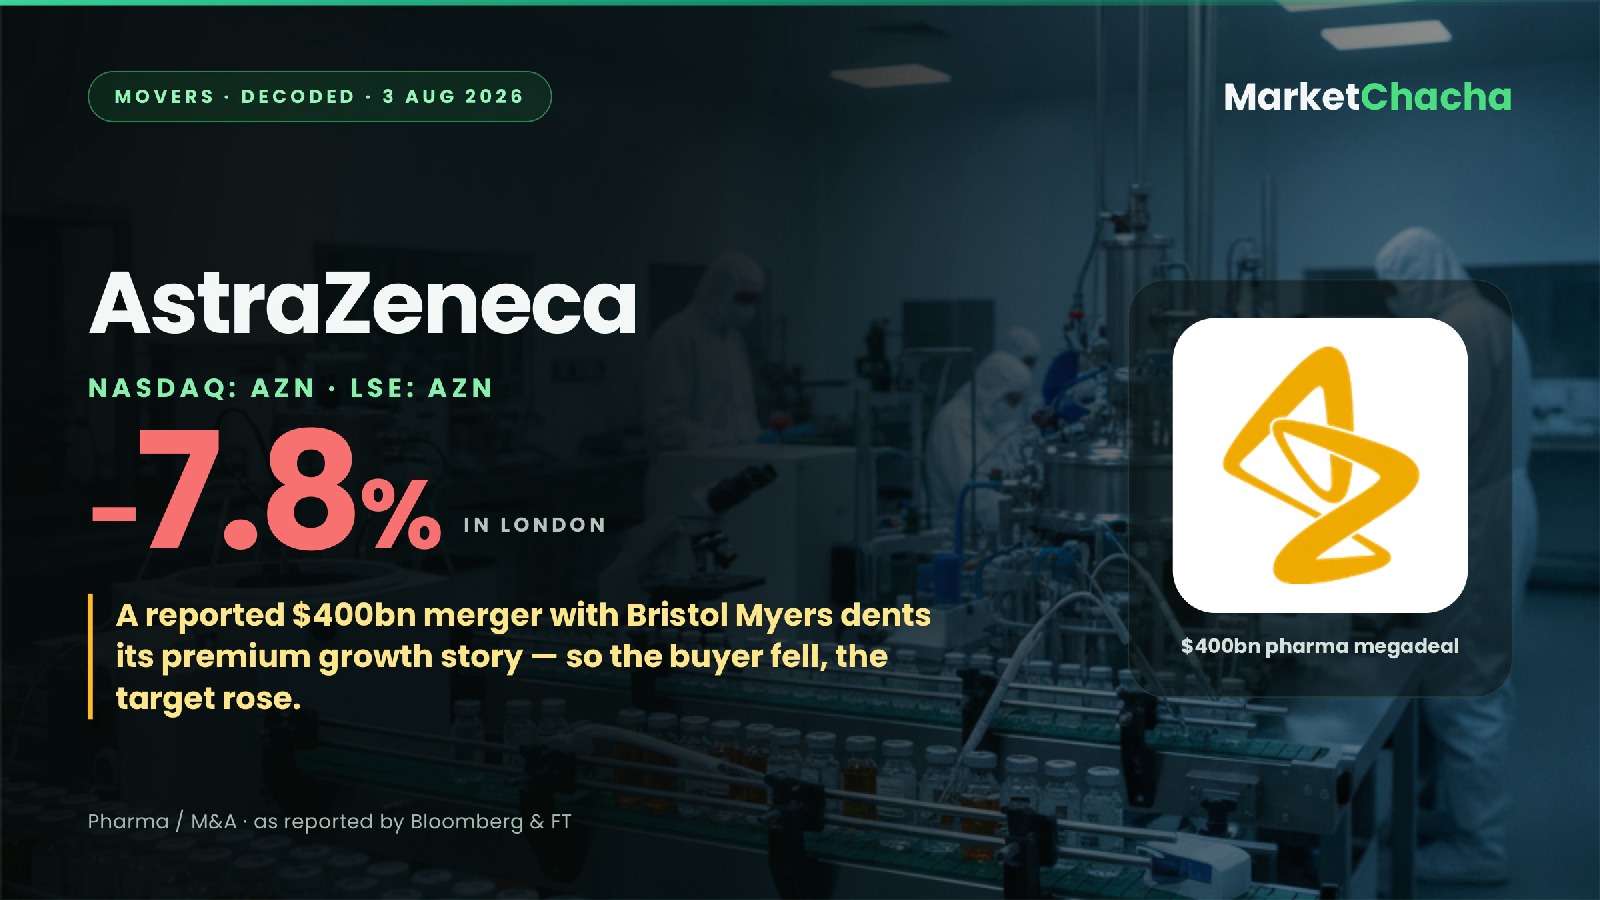
AstraZeneca (LSE / NASDAQ: AZN) fell as much as 7.8% in London on Monday, per Bloomberg — one of the FTSE 100’s ugliest moves — after the Financial Times reported it has held talks to merge with America’s Bristol Myers Squibb (NYSE: BMY). Here’s the twist: the company cast as the buyer got hammered, while the target rose as much as 3.8% before the US open. That gap tells you almost everything about how the market read this.
Why it moved
A tie-up would create a drugmaker worth about $400 billion — one of the largest on earth, and roughly the world’s fourth-biggest by market value. AstraZeneca is worth around $263bn; Bristol Myers about $133bn. On paper, that’s scale. Investors saw something else: risk.
The mechanism is simple. AstraZeneca is the market’s premium pharma story right now — fast organic growth, a deep cancer pipeline, and a public goal of $80bn in revenue by 2030. Bristol Myers is the opposite trade: cheaper, slower, and staring at patent cliffs on big sellers like the blood-thinner Eliquis and cancer drug Opdivo. Merging the two waters down AstraZeneca’s growth premium, adds years of integration work, and — because both are heavyweights in oncology — invites tough antitrust scrutiny. So the market knocked roughly $20bn off AstraZeneca and nudged Bristol Myers up on hopes of a takeover premium.
Is it expensive?
This is really a tale of two multiples. AstraZeneca trades near a P/E of ~31 (as reported, down from a 12-month average around 52) — the kind of rating you only get when the market trusts your growth. Bristol Myers sits at about 16x, roughly half that, because its earnings are seen as flatter and more cliff-prone. When a 31x company buys a 16x company mostly for size, its own shareholders often foot the bill first. That’s exactly what Monday looked like.
The business
AstraZeneca isn’t one thing. Its biggest engine is oncology, but it also runs large cardiovascular-renal-metabolism and respiratory & immunology franchises, plus rare-disease unit Alexion. Bristol Myers brings its own cancer, heart and immunology drugs. The overlap in cancer is both the strategic prize and the regulatory headache — so today’s move is about the whole company’s re-rating, not one product.
Who it touches
- Indian CDMO / CRO names — Syngene International, Divi’s Labs and peers that make and test molecules for global pharma. Mega-mergers can freeze outsourcing decisions during integration, but a bigger combined pipeline means more long-run work.
- Indian generics — Sun Pharma, Dr Reddy’s and Cipla watch Bristol Myers’ coming patent cliffs (Eliquis, Revlimid) as future copy-drug openings.
- AstraZeneca Pharma India (NSE: ASTRAZEN) — the separately listed Indian arm. Its local business isn’t changed by a parent-level deal, but sentiment can still wobble.
- US peers — Pfizer, Merck and J&J, who’d suddenly face a far larger rival in cancer.
What to watch
The one thing that flips this: the talks are early and, in the FT’s telling, could still collapse. If AstraZeneca walks away or the report is denied, Monday’s de-rating can reverse just as fast. If a deal is confirmed — especially at a rich premium — expect the buyer-pays-first pressure to stick around.
As of ~5:20 PM IST / 7:50 AM ET, Aug 3, 2026. Sources: Bloomberg, CNBC, Benzinga. For discussion and education only — not investment advice. Verify before acting.
This article is for educational and informational purposes only. It is not financial advice, investment recommendation, or a solicitation to buy or sell securities. Investing involves significant risks. I am not a SEBI-registered investment advisor. Readers should consult their own financial advisor and conduct their own research before making any investment decisions.
Comments
Join the conversation
Sign in to join the conversation.
Follow replies, add your view, and take part in the discussion.
Sign in to commentLoading comments...