

US Market Brief — Sep 09, 2026 | Futures, movers & what to watch
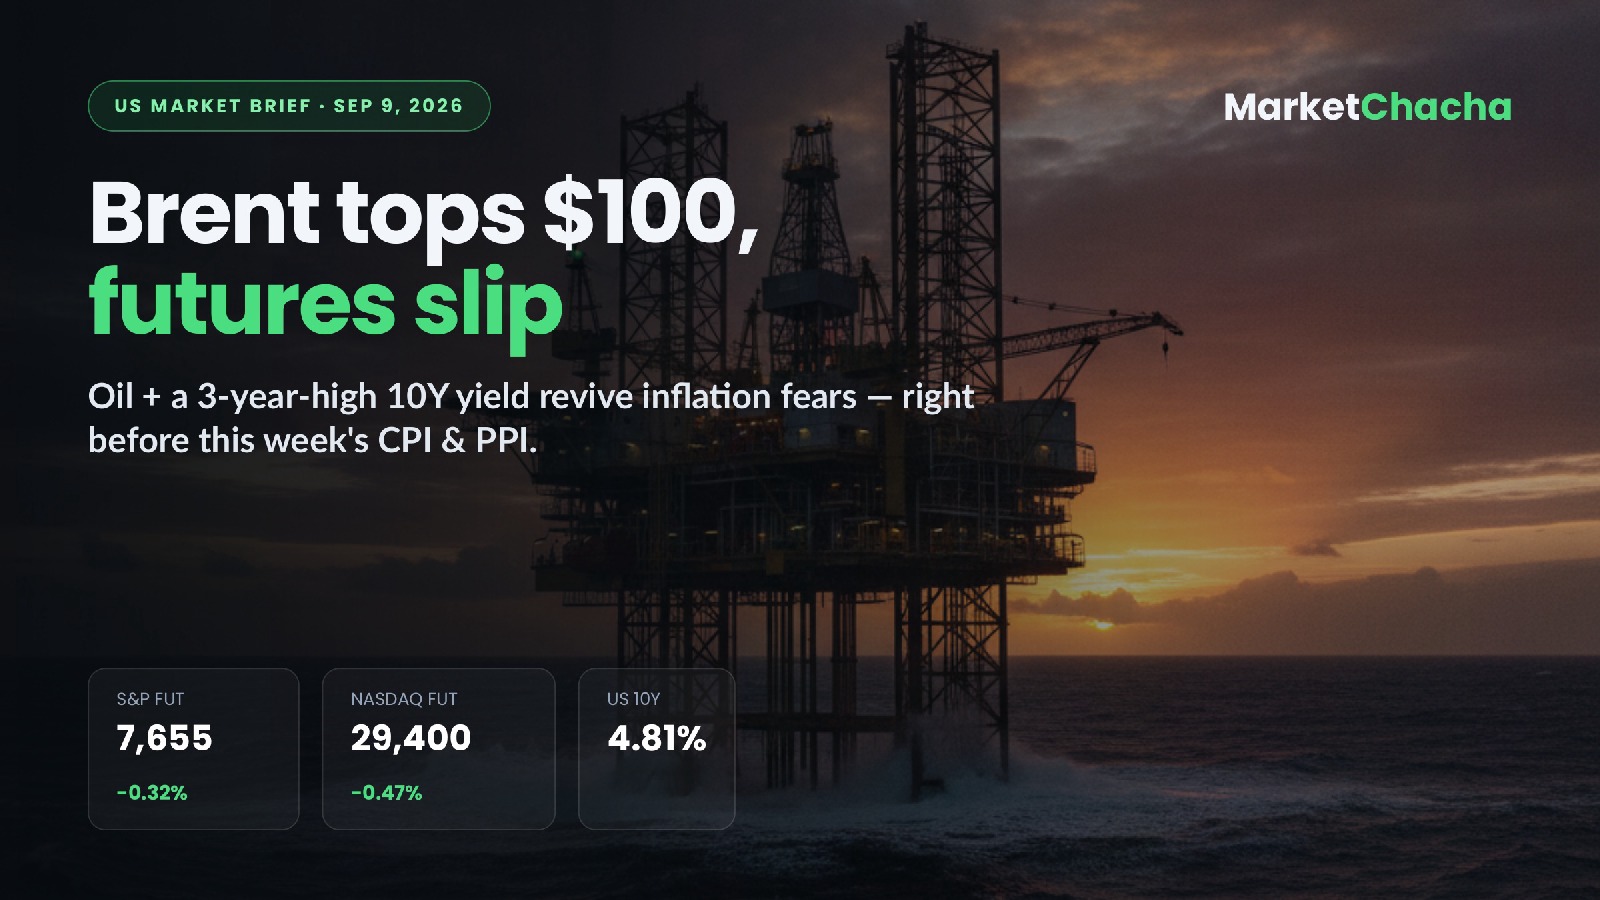
US stock futures are pointing lower into the open as a relentless climb in oil and the highest 10-year Treasury yield since 2023 revive inflation worries — just as traders brace for CPI and PPI later this week. The single biggest overnight driver: Brent crude topping $100 a barrel after US–Iran tensions escalated.
Futures now
- Dow −266 pts (−0.50%), S&P 500 −0.32%, Nasdaq-100 −0.47% (Investrade morning preview / QuoteMedia).
- Follows Tuesday's losses: S&P 500 −0.58% to 7,673.52, Dow −1.18% to 52,786.07, Nasdaq Composite −0.32% to 26,421.41, Russell 2000 −0.52%.
Why: oil & yields
Brent tops $100 (WTI ~$95) after CENTCOM said US forces destroyed five Iranian crude carriers on Sept. 8, following IRGC missile attempts on a US Navy warship. The US 10Y yield sits near 4.81% — its highest close since 2023 — lifting inflation and margin fears. The dollar is near a 7-month low as the yen rallies. Gold eased slightly to ~$4,438/oz. (Sources: Investrade, Yahoo Finance, CNBC.)
Movers & events
- Apple (AAPL) holds its annual iPhone event this afternoon — the first under new CEO John Ternus. A foldable iPhone (possibly $2,000+), iPhone 18 Pro upgrades and new Apple Watches are expected.
- Chime (CHYM) to acquire Stride Bank for $590M and raised Q3 guidance. Sysco (SYY) unveiled a $500M AI cost program. Google (GOOGL) committing €13B to AI infrastructure in Finland. ServiceTitan and Braze fell on guidance.
- Barclays lifted its S&P 500 year-end target to 7,950 from 7,800.
Earnings today
Before the open: Chewy (CHWY), Academy Sports (ASO), Signet (SIG), Caleres. After the close: American Eagle (AEO), AeroVironment (AVAV), Cooper Cos (COO), Skillsoft. The week's marquee AI print, Oracle (ORCL), is due Sept. 10 (options imply an ~11% swing).
Macro today
A light data day ahead of this week's inflation reports: MBA Mortgage Applications (7:00 ET), ICSC & Redbook weekly retail sales, a 10-year Treasury note auction (1:00 ET) — closely watched given the yield backup — and API weekly oil inventories after the close. Note: the EIA petroleum status report is delayed to Thursday (Sept. 7 federal holiday). CPI and PPI land later this week and are the real catalysts.
Global context
Asia mixed (Nikkei −0.2% to 65,142; Shanghai +0.3%; Hang Seng −0.2%). Europe lower (DAX −1.3%, FTSE 100 −0.6%). China's Aug CPI rose 0.8% y/y and PPI 3.8% y/y. The US also escalated a trade dispute with Canada, with new import bans and 50% tariffs on some goods from Sept. 29.
What to watch at the open
Watch whether oil holds above $100 and whether the 10Y pushes further past 4.8% — both would keep pressure on rate-sensitive tech and pre-position the tape defensively into CPI. The 1:00 ET 10-year auction is a real-time read on appetite for duration at these yields. And Apple's event could swing sentiment across the megacap complex into the afternoon.
As of 09:10 ET, Sep 9, 2026. Sources: Investrade Morning Preview, Yahoo Finance, CNBC, Trading Economics. Automated US market brief for discussion and education only — not investment advice. Verify before acting.
This article is for educational and informational purposes only. It is not financial advice, investment recommendation, or a solicitation to buy or sell securities. Investing involves significant risks. I am not a SEBI-registered investment advisor. Readers should consult their own financial advisor and conduct their own research before making any investment decisions.
Comments
Join the conversation
Sign in to join the conversation.
Follow replies, add your view, and take part in the discussion.
Sign in to commentLoading comments...