
Pre-Market Global Brief — Jul 20, 2026 | Nifty, Nasdaq, Nikkei, DAX & more
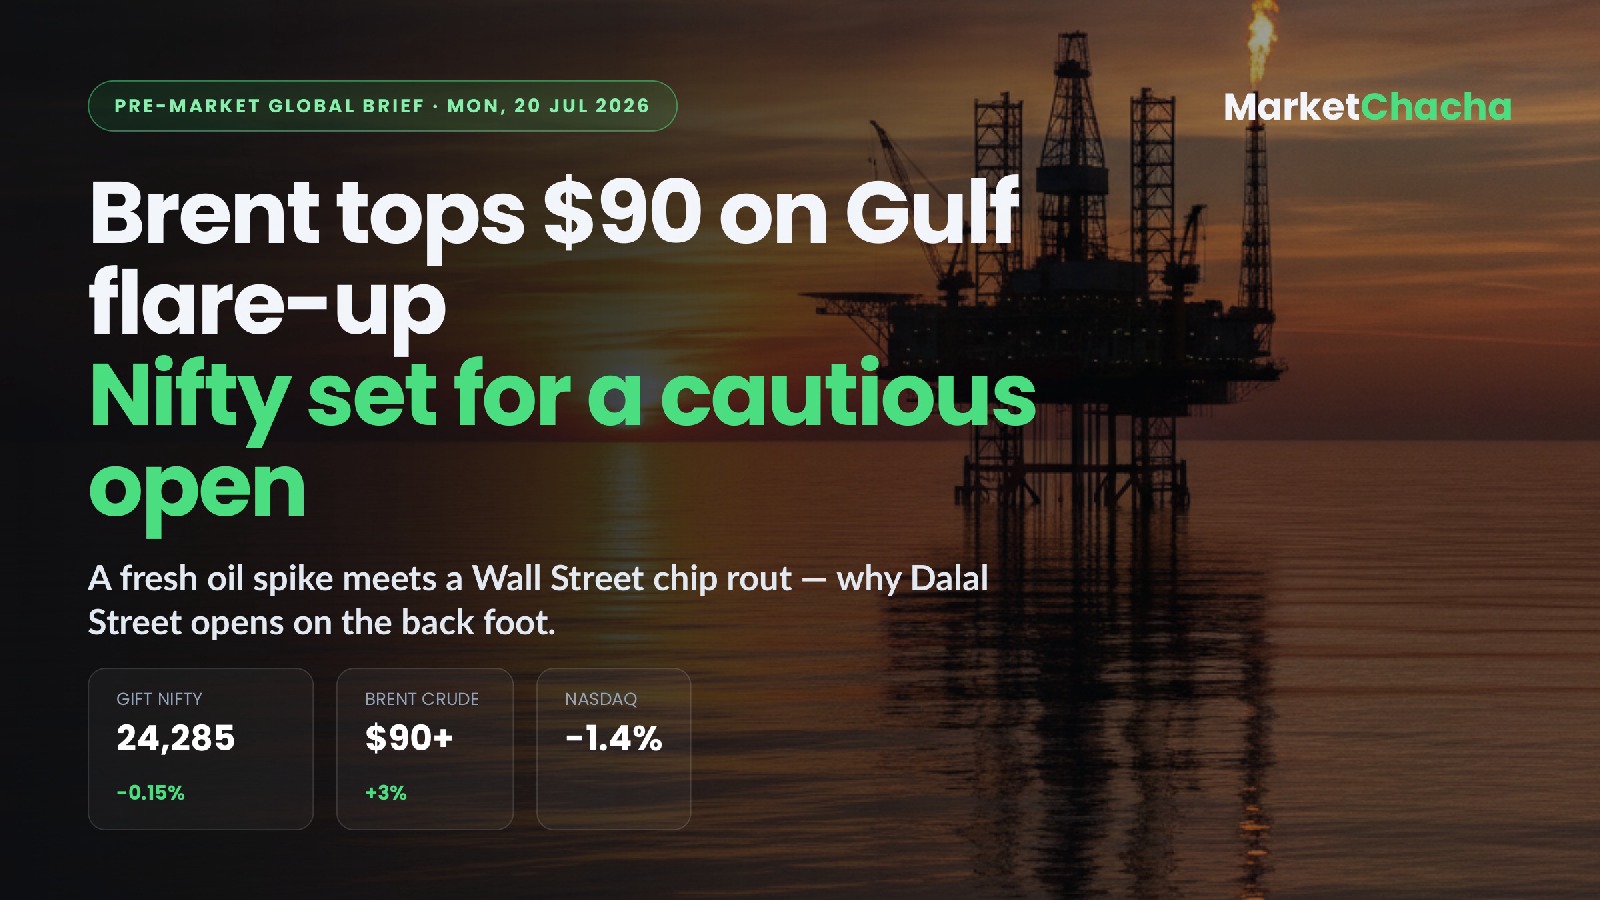
Overnight tone is decisively risk-off: Brent crude jumping back above $90 for the first time in over a month — as the US-Iran conflict ran into a ninth day — collided with a deepening Wall Street sell-off in AI and chip stocks, leaving Indian benchmarks pointed to a cautious, flat-to-lower open despite Friday's strong earnings-led rally.
Wall Street — Friday close
US stocks fell a third straight session as a pullback in AI-linked megacaps morphed into broader risk aversion (AP). The Dow lost 0.8% to 52,146.42, the S&P 500 slid 1.0% to 7,475.69, and the Nasdaq dropped 1.4% to 25,520.24, dragged by a semiconductor rout led by SK Hynix and peers.
Asia now
Trade is hesitant. Japan's Nikkei 225 is shut for the Marine Day holiday; South Korea's Kospi is off about 0.6% after a near-9% weekly plunge, and MSCI's Asia-ex-Japan index is down roughly 0.3% (Reuters). Oil-driven inflation worries are the common thread.
Europe — Friday close
Germany's DAX eased 0.34% to 24,831 while London's FTSE 100 edged up 0.08% to 10,581, helped by energy names (Trading Economics).
India lead — GIFT Nifty
GIFT Nifty was down 36.7 points (0.15%) at 24,285, pointing to a muted, flat-to-lower open. On Friday the Sensex jumped 964.58 pts (1.25%) to 78,151.45 and the Nifty rose 261.55 (1.09%) to 24,334.30 on private-bank, IT and auto buying (Business Standard). FPIs net sold ₹376 cr on Friday while DIIs net bought ₹1,018 cr (Business Today).
Commodities, currency & yields
- Brent crude: up ~3% above $90/bbl — today's single biggest driver (Business Today).
- Gold: down ~0.6% near $3,993/oz as yields firmed.
- Dollar index (DXY): +0.1% at 100.84; USD/INR near 96.5.
- US 10-year yield: around 4.56%.
Data & events to watch this week
India's macro calendar is light — the driver is Q1 earnings, with UltraTech Cement and Paytm reporting today and RBI's weekly forex reserves due Friday. Globally, watch US weekly jobless claims (Thu) and S&P Global flash PMIs (Fri); the Fed is in its pre-FOMC blackout ahead of the July 28-29 meeting (funds rate 3.50-3.75%). A hot PMI or another oil leg-up would harden the market's surprising bet on ~29 bps of Fed hikes by year-end — a headwind for rate-sensitive Indian sectors.
What it means for the India open
Expect a soft, headline-driven open with energy front and centre: higher crude helps upstream names like ONGC and Oil India but squeezes OMCs, paints, tyres and aviation. Earnings will steer stock-specific action — heavyweights RIL, HDFC Bank and ICICI Bank set the tone. Nifty support sits near 24,000-24,200, with resistance at 24,500-24,800.
As of 8:45 AM IST, 20 Jul 2026. Sources: Business Standard, Business Today, Reuters via Yahoo Finance, Washington Post/AP, Trading Economics. Automated pre-market brief for discussion and education only — not investment advice. Verify before acting.
This article is for educational and informational purposes only. It is not financial advice, investment recommendation, or a solicitation to buy or sell securities. Investing involves significant risks. I am not a SEBI-registered investment advisor. Readers should consult their own financial advisor and conduct their own research before making any investment decisions.
Comments
Join the conversation
Sign in to join the conversation.
Follow replies, add your view, and take part in the discussion.
Sign in to commentLoading comments...