

Post-Market Wrap — Jul 30, 2026 | How India & the world closed
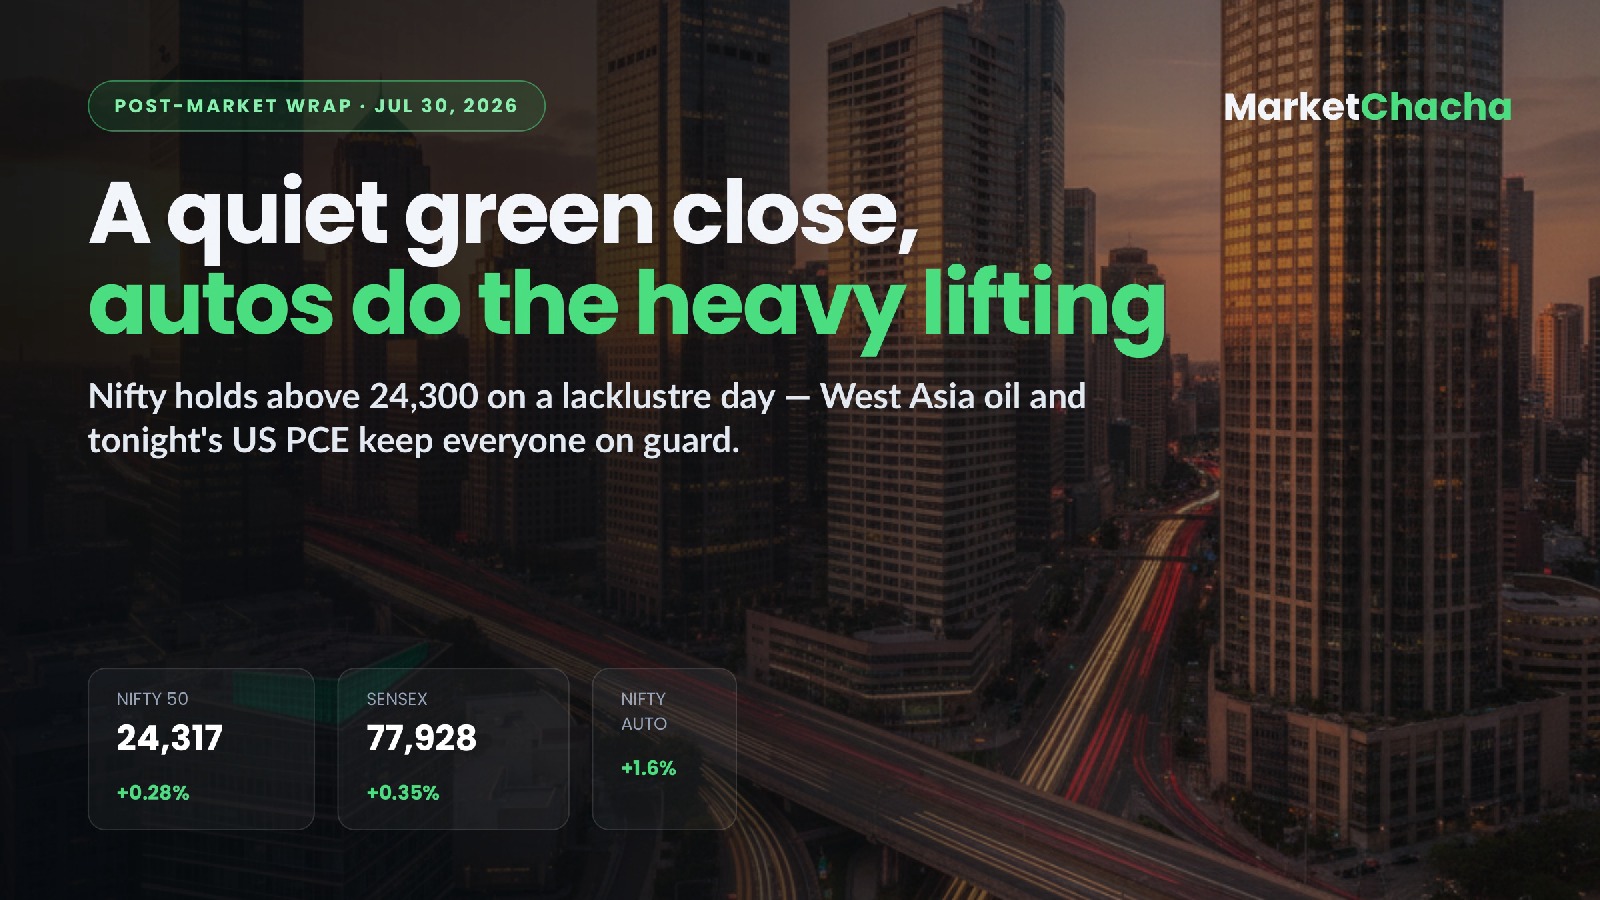
Indian equities eked out a quiet, marginally positive close on Thursday, with the Nifty holding above 24,300 as autos and energy did the heavy lifting while realty, financials and the broader market lagged and traders stayed wary of the escalating US–Iran conflict.
How India closed
The Nifty 50 settled at 24,317.15, up 66.95 points (0.28%), and the Sensex rose 273.55 points (0.35%) to 77,928.15, as reported by Business Standard — a third straight up-day, but a lacklustre one as investors booked profits from Wednesday's ~800-point rally and watched West Asia. Breadth was soft: the Nifty Midcap 100 fell ~0.35% and the Smallcap 100 lost ~0.56%.
Sectors & stocks
- Nifty Auto led, up ~1.6%. Mahindra & Mahindra (up ~3% on Q1 profit growth), Coal India and Eicher Motors topped the Nifty50; oil & gas also firmed.
- Laggards: realty (Nifty Realty ~-1%), with Asian Paints, Adani Ports, Eternal, IndiGo, BEL and ICICI Bank sliding up to ~3% (Business Today).
- A packed Q1FY27 earnings day — Tata Steel, Bajaj Finance, Hyundai Motor India, Swiggy, Vedanta and IRFC among those reporting; Xtranet, Indo-MIM and Lohia Corp debuted, and Juniper Green Energy's ₹1,800-crore IPO opened.
Flows, currency & commodities
Business Standard flagged strengthening FII inflows and a firmer rupee as key supports; FPIs have turned net buyers in July after heavy year-to-date selling. The rupee opened ~95.60/$ versus 95.65 prior. Day-wise provisional FII/DII cash figures were not yet published at the time of writing. Brent crude eased about 2% to the mid-$80s (~$84/bbl) but stayed elevated on Middle East supply fears (Benzinga).
Global now
Europe opened higher — DAX +0.5%, CAC +0.4%, FTSE +0.1%. Asia closed mixed: Japan's Nikkei and Hong Kong's Hang Seng rose, while South Korea's Kospi, Australia's ASX and China's CSI 300 fell, with chip-stock weakness weighing on Seoul. US futures steadied after the Federal Reserve held rates on Wednesday (Benzinga).
Data on the radar
The heavy prints land tonight (IST): US Q2 GDP advance (~+2.3% est.), June core PCE — the Fed's preferred inflation gauge (est. +0.1% m/m, +3.3% y/y) — plus personal income/spending and weekly jobless claims (~201k est.). Eurozone Q2 GDP flash (~+0.1%) and July flash CPI (~3.0%) follow. In India, month-end fiscal-deficit and core-sector output data are due around now.
What to watch
With the Fed out of the way, the tone into Friday hinges on US core PCE and GDP for rate-cut expectations, and on crude and the US–Iran headlines that are steering the rupee and India's import bill. Watch whether FIIs keep buying and how the final leg of Q1FY27 earnings lands — autos set a firm tone, but broad-market breadth needs to improve for the index to break decisively above 24,400.
As of 4:20 PM IST, Jul 30, 2026. Sources: Business Standard, Business Today, Benzinga, Investing.com. Automated market wrap for discussion and education only — not investment advice. Verify before acting.
This article is for educational and informational purposes only. It is not financial advice, investment recommendation, or a solicitation to buy or sell securities. Investing involves significant risks. I am not a SEBI-registered investment advisor. Readers should consult their own financial advisor and conduct their own research before making any investment decisions.
Comments
Join the conversation
Sign in to join the conversation.
Follow replies, add your view, and take part in the discussion.
Sign in to commentLoading comments...