

Pre-Market Global Brief — Aug 26, 2026 | Nifty, Nasdaq, Nikkei, DAX & more
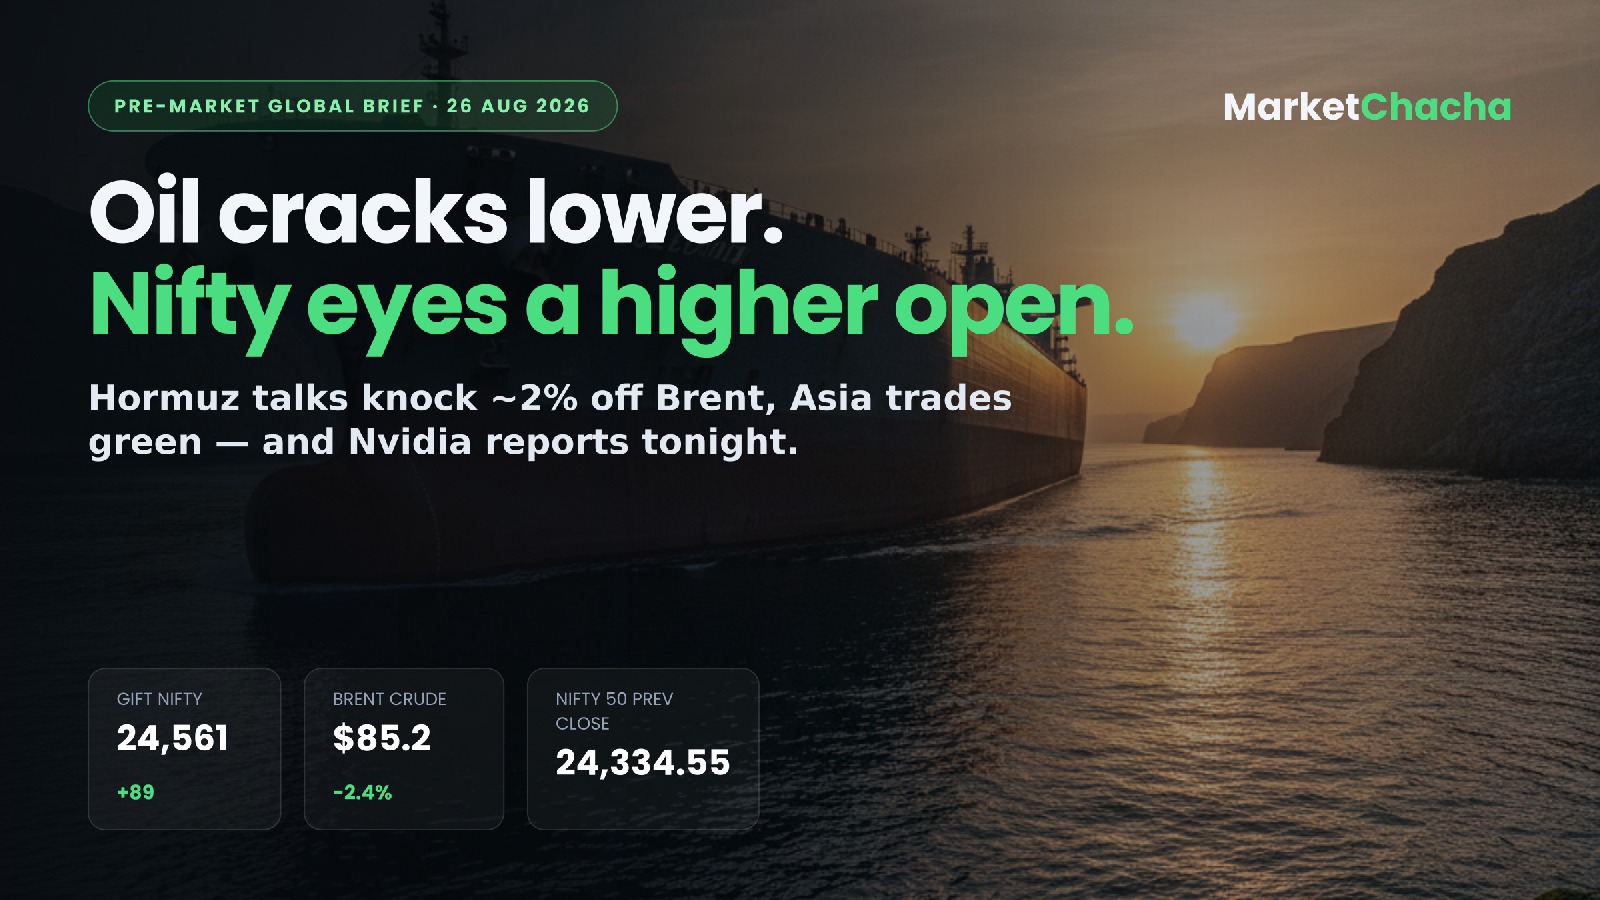
Overnight tone is risk-on, and the single driver is oil — reports that Iran and Oman are discussing an interim framework to reopen shipping through the Strait of Hormuz knocked Brent back toward $85, which lifted Wall Street, cooled US yields and hands India's open a tailwind.
US: prior close (Aug 25)
- S&P 500 closed at 7,677.28, up 0.32%; the Dow added roughly 160 points (+0.30%) and the Nasdaq Composite rose 0.66%, as reported by Eastern Herald and Upstox.
- Ceasefire hopes and softer crude did the work. Moderna jumped over 14% on melanoma vaccine data; Albemarle was the worst S&P performer after guidance was cut.
Asia, trading now
- Nikkei 225 ~66,206, +0.53%; Hang Seng ~25,780, +1.05% — both per Trading Economics.
- Shanghai Composite +0.5% (prior close 3,889.44) and Kospi +1.03%, per Upstox — chipmakers bid up ahead of Nvidia.
Europe: Tuesday close
Per Trading Economics: DAX 26,236 (+0.50%) on firm German GDP and confidence data, FTSE 100 ~10,868 (+0.11%) — a sixth straight gain — and Euro Stoxx 50 6,458 (+0.15%).
India lead
GIFT Nifty is quoted at 24,561, up about 89 points (Upstox; Business Standard has 24,558/+87), pointing to a positive open against Tuesday's Nifty 50 close of 24,334.55 (+0.48%) and Sensex 77,656.09 (+0.37%). FIIs were net buyers of ₹1,593.53 crore on Tuesday, DIIs ₹230.26 crore.
Commodities, currency, rates
- Brent around $85, down ~2.4% intraday (Upstox); Business Standard has September Brent at $85.43.
- Gold near $4,643/oz (Trading Economics); gold futures +0.46% (Business Standard).
- USD/INR ~95.11 and the dollar index ~98.9, per Trading Economics. US 10-year at 4.63%, easing from a 20-month high of 4.75% hit on Aug 21.
On the calendar today
- US, 6:00 pm IST: Q2 GDP (second estimate, prior 1.5%), Personal Income & Outlays — which carries the PCE deflator, the Fed's target gauge — and Durable Goods Orders. A hot PCE revives the higher-for-longer trade and pressures the rupee; a soft print is a straight positive for Indian rate-sensitives.
- Euro area: M3 money supply and bank lending. UK: CBI distributive trades.
- Tomorrow: US initial jobless claims, forecast ~207K vs 206K prior.
- India: no major scheduled macro release today — the next markers are weekly RBI forex reserves on Friday, then month-start auto sales and S&P Global manufacturing PMI.
- Tonight: Nvidia reports Q2 FY27 after the US close (MarketBeat) — the swing factor for Indian IT and global risk appetite on Thursday.
Stocks and events in focus
Hindustan Copper's OFS opens to retail today; Varun Beverages is entering the alcoholic beverages segment; Emami and ITC Hotels are in the news. In primary markets, Annu Projects (₹175 crore) and Sumax Engineering (₹53 crore) are in day two, and Gaja Alternative lists today.
What it means for the India open
Cheaper crude is the cleanest positive India can get — it eases the import bill, the inflation path and rupee pressure at once, so OMCs, paints, aviation and rate-sensitives are the natural beneficiaries while upstream oil names lag. With global cues green and FIIs buying, the bias is a firm start. But the day's real risk sits after the bell: US PCE at 6:00 pm and Nvidia overnight can reverse the mood before Thursday.
As of 9:00 AM IST, 26 August 2026. Sources: Business Standard, Upstox, Trading Economics, Eastern Herald, The Right Trader, MarketBeat. All prices and index levels are as reported by these sources, not live exchange data. Automated pre-market brief for discussion and education only — not investment advice. Verify before acting.
This article is for educational and informational purposes only. It is not financial advice, investment recommendation, or a solicitation to buy or sell securities. Investing involves significant risks. I am not a SEBI-registered investment advisor. Readers should consult their own financial advisor and conduct their own research before making any investment decisions.
Comments
Join the conversation
Sign in to join the conversation.
Follow replies, add your view, and take part in the discussion.
Sign in to commentLoading comments...