

US Market Brief — Sep 02, 2026 | Futures, movers & what to watch
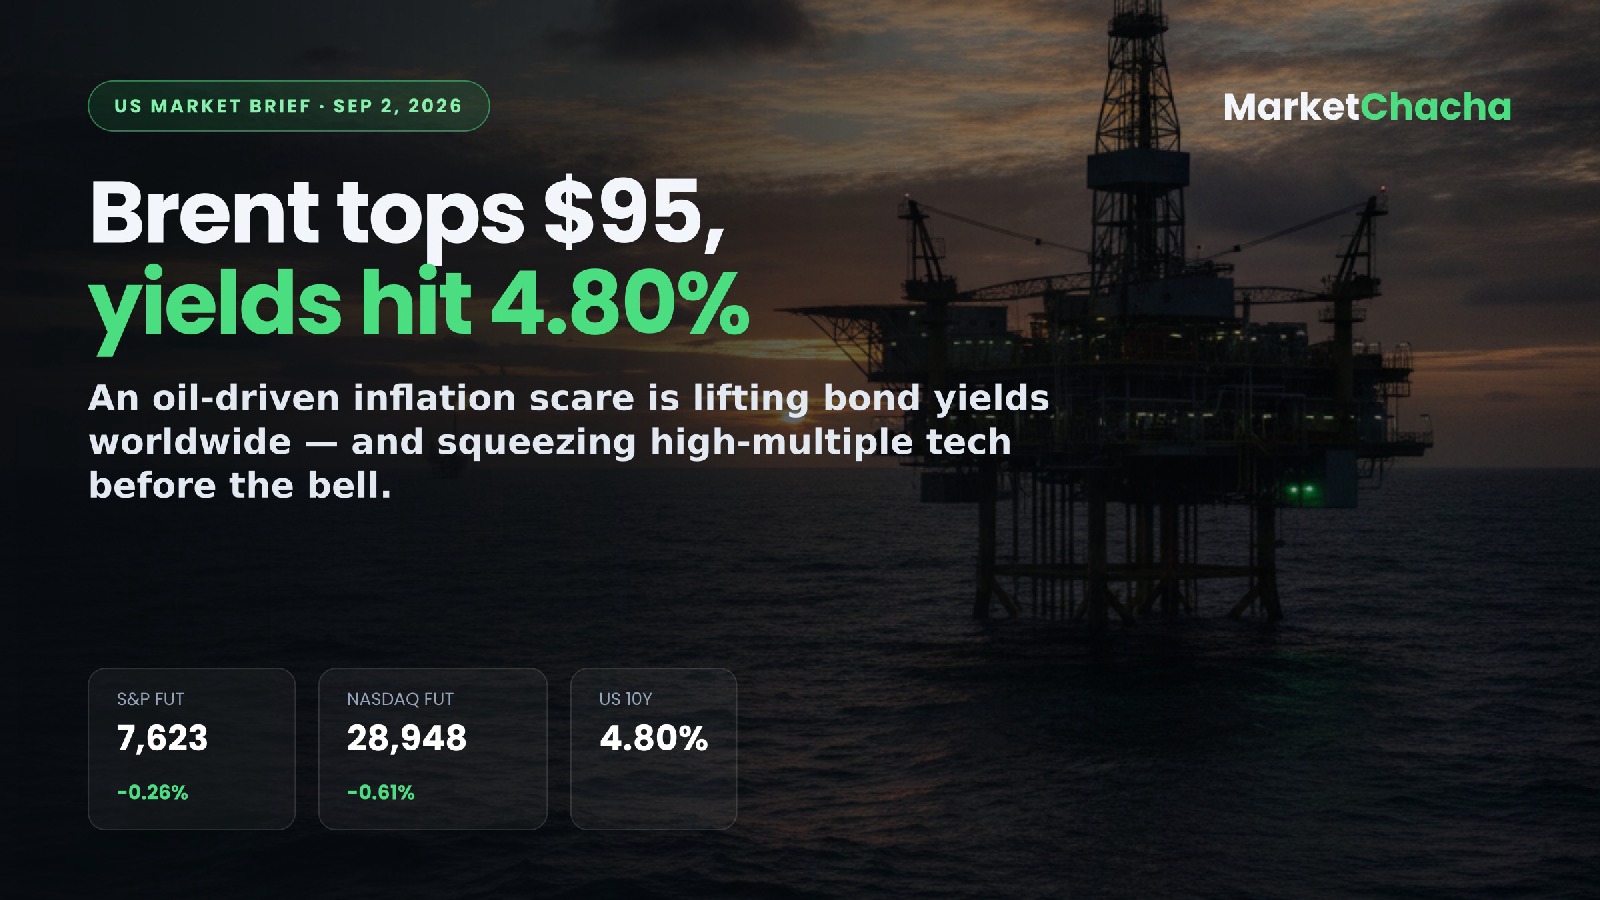
US futures are soft into the bell as an oil-driven inflation scare pushes bond yields to multi-year highs worldwide, with escalating US–Iran hostilities the single biggest overnight driver. Growth and high-multiple tech are taking the brunt.
Futures now
- S&P 500 futures 7,623.00, -0.26% · Dow futures 52,756.00, -0.14% · Nasdaq-100 futures 28,948.00, -0.61% — as reported by Yahoo Finance.
- Driver: Brent above $95 after tit-for-tat US–Iran strikes, with President Trump threatening to hit Iran "much harder" on retaliation (Yahoo Finance). VIX reported at 16.77, +2.63%.
Pre-market movers
- Dell (DELL) +9.7% — raised annual revenue and profit forecasts on AI-server demand; adjusted EPS $7.04 vs $4.91 expected, revenue ~$46.97bn (Investing.com, Investopedia).
- GitLab (GTLB) +22% — beat with ~20-21% revenue growth and raised full-year guidance.
- MongoDB (MDB) -13.6% — beat on Q2 ($771.8m revenue, +30%), but valuation and guidance caution dominated.
- HPE +4.7% on the Dell read-across; Uber +2.4% on plans to cut ~3,300 jobs (~10% of staff); Sirius XM +3.1% on a Deutsche Bank upgrade; Super Micro -1.5% with semis under rate pressure (Investing.com).
Earnings today
After the close: Broadcom (AVGO) — consensus ~$29.3-29.5bn revenue and ~$3.21-3.24 adjusted EPS — plus Snowflake (~$1.48bn, $0.45), HPE (~$11.93bn, $0.92), NetApp, Five Below, PVH and C3.ai. Before the bell: Brown-Forman, Ollie's Bargain Outlet, G-III Apparel, Sprinklr (Investing.com). No notable US listings flagged for today.
Macro today (full calendar)
- ADP employment (Aug), released: +38,000 vs 48,000 consensus, prior revised to +46,000 — slowest since January. Gains concentrated in education/health (+45k) and leisure/hospitality (+16k) (Fox Business, CNBC). A soft private-payroll print argues for easier policy, but today it is being read against the oil-inflation risk.
- MBA mortgage applications (w/e Aug 28), 7:00am ET — prior 30-year rate 6.78%, purchase index 154.4.
- Factory orders (Jul), 10:00am ET — consensus +0.7% vs -0.3% prior; with durable goods final (Jul), ex-transport prior +0.4%. A beat would say capex is holding up despite tighter financial conditions.
- EIA crude inventories, 10:30am ET — prior +0.095m barrels. A draw would add to the oil bid.
- Fed Beige Book, 2:00pm ET — the qualitative district read on hiring, pricing power and how firms are handling energy costs.
- 17-week bill auction, 11:30am ET (Investing.com, Trading Economics).
Ahead: Thursday brings initial jobless claims (cons. ~203k), trade balance and ISM Services; August non-farm payrolls land Friday.
Rates, dollar, commodities
- US 10-year 4.798-4.81% — described as the highest since January 2025 (Yahoo Finance) / since November 2023 (TheStreet); 30-year 5.27%.
- Oil: Brent above $95 (Yahoo Finance); WTI around $89, roughly -1% on the session (Investopedia).
- Gold ~$4,355/oz, about -0.9%; silver ~$64.26, -1.7% (TheStreet). Bitcoin ~$76,600, -1.6%.
- Dollar firm: EUR/USD 1.1573 (-0.2%), USD/JPY 159.70 (investingLive). DXY level: n/a.
Overnight global context
This is a global bond story, not just a US one. Germany's 10-year hit 3.37% (highest since 2011), France 4.24% (since 2008), the UK 5.26% (since 2008) and Japan 3.02% (highest since 1996), with European equities lower and the mood described as "edgy and nervous" (investingLive). Rising long-end yields everywhere are what is compressing US growth multiples pre-open.
What to watch at the open
Watch whether the 10-year holds above 4.80% — that level, not the ADP miss, is what semis and long-duration software are trading off this morning. Watch the oil tape into the 10:30am EIA number for confirmation the inflation scare has legs. And watch positioning into Broadcom tonight: with AI-server demand already validated by Dell, an in-line print may not be enough to lift the group.
As of 9:35 AM ET, 2 September 2026. Figures as reported by: Yahoo Finance, TheStreet, CNBC, Fox Business, Investing.com, investingLive, Trading Economics. Automated US market brief for discussion and education only — not investment advice. Verify before acting.
This article is for educational and informational purposes only. It is not financial advice, investment recommendation, or a solicitation to buy or sell securities. Investing involves significant risks. I am not a SEBI-registered investment advisor. Readers should consult their own financial advisor and conduct their own research before making any investment decisions.
Comments
Join the conversation
Sign in to join the conversation.
Follow replies, add your view, and take part in the discussion.
Sign in to commentLoading comments...