

Post-Market Wrap — Jul 23, 2026 | How India & the world closed
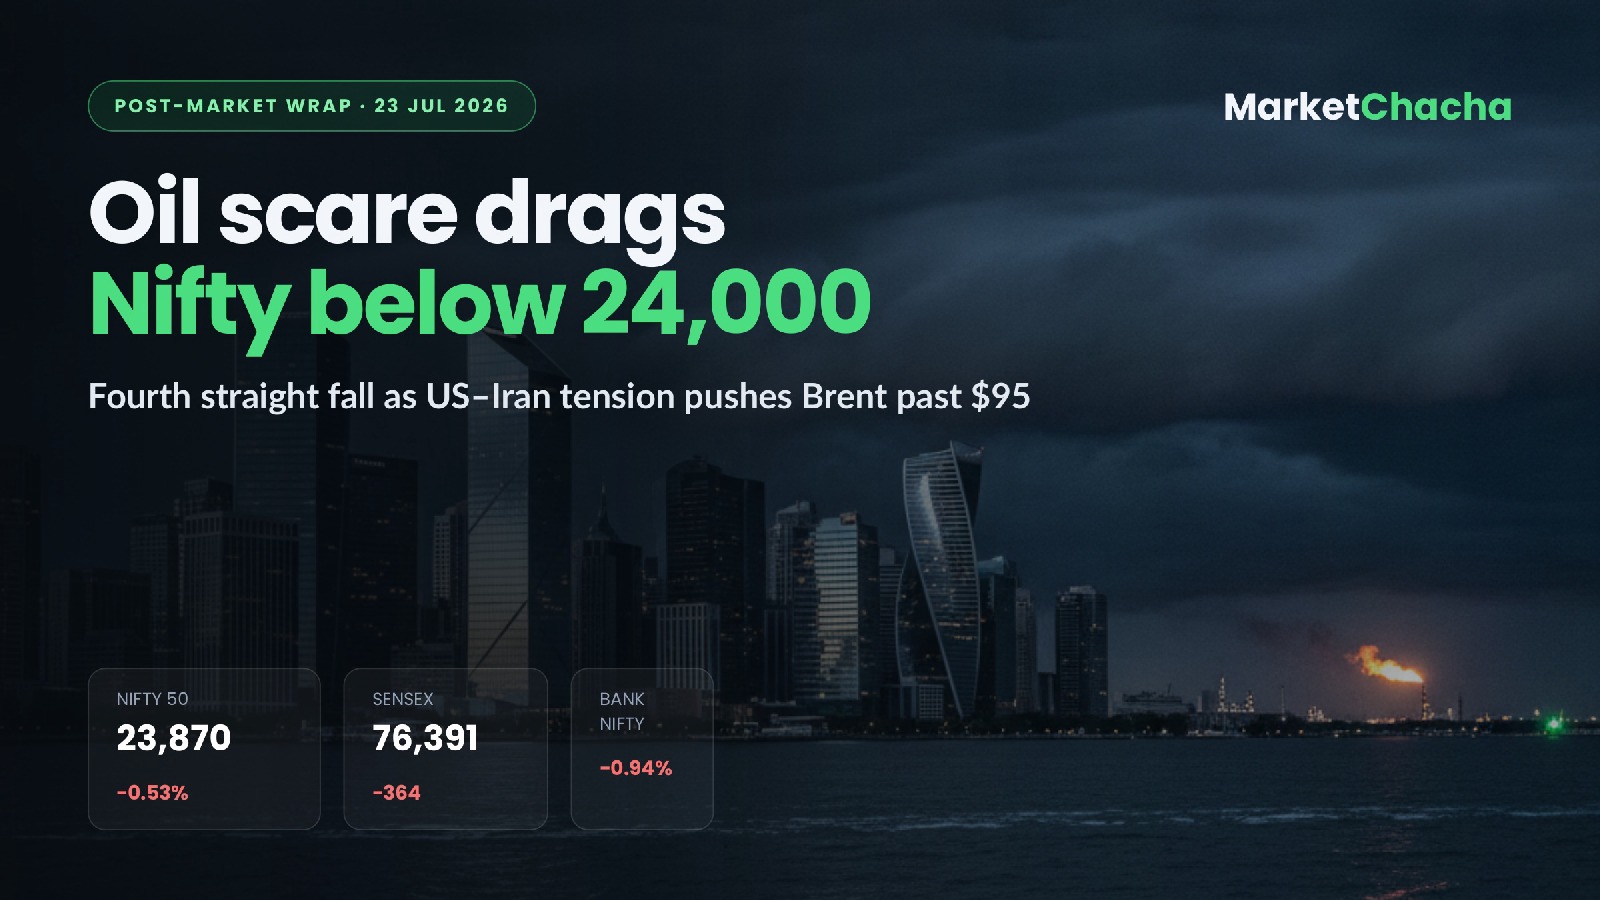
Indian equities closed lower for a fourth straight session, with the Nifty slipping decisively below 24,000 as a fresh spike in crude oil on renewed US–Iran tension kept buyers on the sidelines, per Business Standard.
How India closed
- Nifty 50: 23,869.60, down 127 pts (−0.53%) — as reported by Business Standard.
- Sensex: 76,391.39, down 364 pts (−0.47%), its fourth losing day in a row.
- Nifty Bank: down about 0.94%, among the day's weaker sectoral indices.
- Broader market: Nifty Midcap 100 −0.99% and Smallcap 100 −1.01% — small- and mid-caps lagged the front line.
The single biggest driver: Brent crude pushed past $95/barrel after reports of a tanker struck off Saudi Arabia and fresh US strikes on Iran, reviving fears of imported inflation and pressure on oil-importer margins.
Sectors & movers
Rate- and oil-sensitive corners led the slide: Nifty Realty fell about 1.81%, with PSU Banks, private banks, chemicals and oil & gas also weak. Auto and media held up better. Among Nifty 50 stocks, Business Standard flagged Adani Enterprises, Nestle India, Shriram Finance, Bajaj Finance, IndiGo, Axis Bank and Reliance as top drags, while M&M, TCS, Eternal, HCL Tech and Bajaj Finserv bucked the trend. It was a heavy earnings day — Infosys, Cipla, IndiGo, IEX, Coromandel, Cyient, Meesho and Motilal Oswal were among 63 firms reporting Q1 FY27.
Flows, currency & commodities
Today's provisional FII/DII figures are awaited at press time; in the prior session (July 22), FIIs net sold about ₹819 cr and DIIs about ₹418 cr in the cash market (Trendlyne). The rupee held near ₹96.6/$ (BookMyForex). Brent traded around $95.5/bbl, up ~1.6% (Reuters/Business Standard), while gold and silver futures eased.
Global now
Asia closed firmer, led by chip names on AI-spending optimism — Japan's Nikkei +0.99% and South Korea's Kospi +3.49%. In Europe, defence stocks outperformed early (Dassault, Thales, Indra higher). US futures were mixed after Wall Street's overnight dip (Dow −0.01%, S&P 500 −0.14%, Nasdaq −0.57%).
Data on the radar
India's focus stayed on Q1 FY27 earnings rather than macro prints today. Globally, tonight brings the ECB rate decision (widely expected to hold) plus Lagarde's press conference, and US weekly jobless claims. Tomorrow, flash July PMIs for the US, Eurozone and Japan will test the growth picture.
Sentiment & what to watch
The tone was risk-off at home — oil-led inflation worry plus foreign selling — even as global risk appetite looked steadier on the AI/chip trade. Watch the Street's reaction to Infosys, Cipla and IndiGo results, whether Brent cools or extends on US–Iran headlines, the ECB tone tonight, and whether the Nifty can defend 23,800 and reclaim 24,000. Friday's global flash PMIs set the next macro cue.
As of 4:03 PM IST, 23 July 2026. Sources: Business Standard, Trendlyne, BookMyForex, TradingKey. Automated market wrap for discussion and education only — not investment advice. Verify before acting.
This article is for educational and informational purposes only. It is not financial advice, investment recommendation, or a solicitation to buy or sell securities. Investing involves significant risks. I am not a SEBI-registered investment advisor. Readers should consult their own financial advisor and conduct their own research before making any investment decisions.
Comments
Join the conversation
Sign in to join the conversation.
Follow replies, add your view, and take part in the discussion.
Sign in to commentLoading comments...