

Post-Market Wrap — Aug 04, 2026 | How India & the world closed
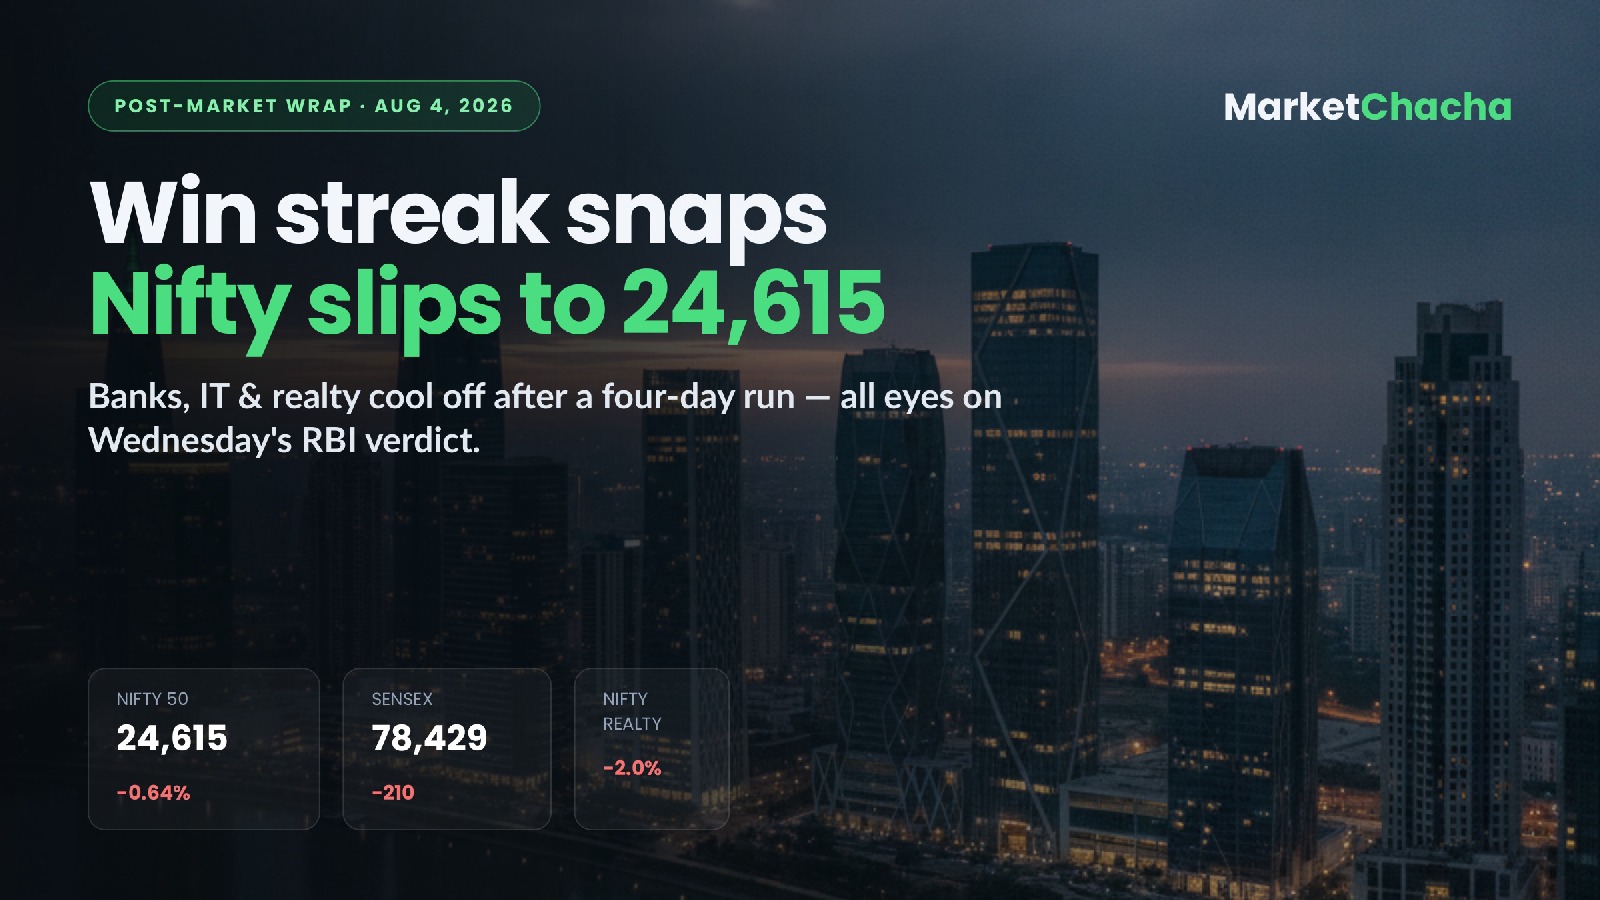
Indian equities snapped a four-day winning streak on Tuesday as profit-booking in banks, financials and IT dragged the benchmarks lower, with investors turning cautious just ahead of the RBI's rate verdict on Wednesday. The Nifty 50 closed at 24,614.90 (down 0.64%) and the Sensex at 78,428.95 (down 210 points, 0.27%), as reported by Business Standard.
How India closed
- Nifty 50: 24,614.90, down 159.40 pts (0.64%)
- Sensex: 78,428.95, down 210.08 pts (0.27%)
- Nifty Midcap 100: down 0.29% · Smallcap 100: up 0.23% — the broader market held up better than large-caps (Business Standard).
A structural quirk added to the noise: Tuesday's weekly F&O expiry was only the second session under the NSE's new Closing Auction Session (CAS) mechanism, and desks flagged a distortion between the 3:30 and 3:40 pm prints — part of why the Sensex (0.27%) and Nifty (0.64%) diverged so much (Geojit, via Business Standard).
Sectors & stocks
Nifty Realty was the worst performer, down over 2%; FMCG, Private Bank and Bank also lagged, while only Media and Metal ended higher. Top index drags were Grasim (about -3.4%), HDFC Life (about -3.3%, a two-year low despite an earnings beat, on profit-booking) and Hindustan Unilever; Federal Bank fell over 4% among lenders. The event stock was LIC, which tumbled roughly 8% as the government's offer-for-sale — up to a 6.5% stake at a floor of ₹382, about a 10% discount to Monday's close — opened for bidding (Business Standard, HDFC Sky).
Flows, currency & commodities
The rupee was steady near ₹95.3–95.4 to the dollar (Investing.com). Crude held firm — Brent quoted around $85 and WTI near $81 — while gold stayed bid, with MCX gold up about ₹644 on hopes of a Strait of Hormuz reopening (Business Standard, Investing.com). Latest confirmed institutional flows (Aug 3): FIIs net bought ₹922 cr and DIIs about ₹1,517 cr; Tuesday's provisional figures were not yet published at press time (Upstox).
Global now
Asia was mixed — Japan's Nikkei firmed while Hong Kong's Hang Seng slipped about 0.6%. Europe opened higher (Stoxx 600 up ~0.5%, DAX up ~0.6%). US futures pointed up after Monday's record Dow close, with Palantir (+16% pre-market on a blowout Q2) and Caterpillar (+6%) leading — a risk-on global tape that stood in contrast to India's pause (CNBC).
Economic data on deck
The main India event is Wednesday's RBI MPC decision: economists overwhelmingly expect the repo rate held at 5.25% with a neutral stance, so the Governor's commentary on inflation and liquidity is the real swing factor (Business Standard). July's HSBC India Services PMI had already cooled to 53.1, the softest since February 2022. Globally, this week's US calendar is heavy — Trade Balance (Jun) today, then ISM Services PMI and ADP payrolls (Wed), jobless claims (Thu) and the marquee US July nonfarm payrolls (Fri) (FinancialJuice).
What to watch
Wednesday's RBI verdict and tone will steer banks and other rate-sensitives — a dovish signal could revive the rally, a hawkish one could deepen the pullback. Also on the radar: Q1 results landing tonight (Bharti Airtel, ONGC, Pidilite, Marico and 130-plus others), the LIC OFS close on Aug 5, and whether the US data run keeps Wall Street's risk-on mood intact into Friday's jobs print.
As of 4:05 PM IST, Aug 4, 2026. Sources: Business Standard, Upstox, HDFC Sky, Investing.com, Business Standard (RBI), CNBC, FinancialJuice. Automated market wrap for discussion and education only — not investment advice. Verify before acting.
This article is for educational and informational purposes only. It is not financial advice, investment recommendation, or a solicitation to buy or sell securities. Investing involves significant risks. I am not a SEBI-registered investment advisor. Readers should consult their own financial advisor and conduct their own research before making any investment decisions.
Comments
Join the conversation
Sign in to join the conversation.
Follow replies, add your view, and take part in the discussion.
Sign in to commentLoading comments...