

US Market Brief — Sep 03, 2026 | Futures, movers & what to watch
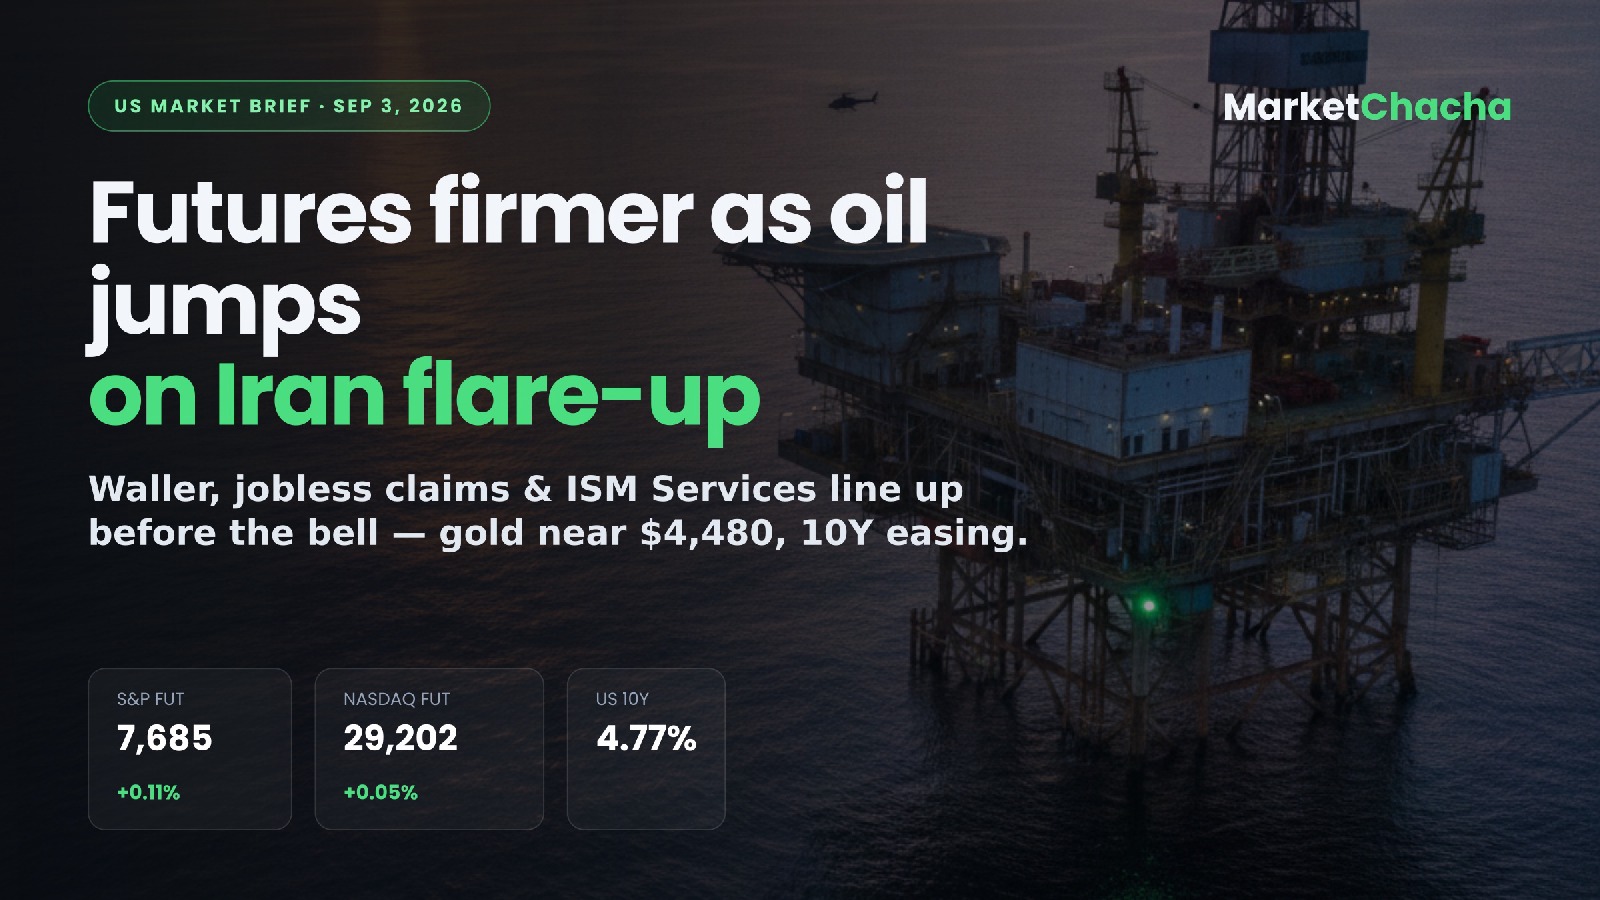
US futures point to a modest rebound at the open after a three-day slide, with traders leaning back into risk as Middle East tensions ease at the margin while oil holds its gains and the dollar softens. The ISM Services print and Fed's Waller are the twin swing factors before the bell.
US futures now
- Dow futures ~ 53,245, +0.23% (Yahoo Finance).
- S&P 500 futures ~ 7,684.75, +0.11% (Yahoo Finance).
- Nasdaq-100 futures ~ 29,201.50, +0.05% (Yahoo Finance).
- Overnight driver: markets recovered after Trump characterised Iran's retaliatory strikes on US allies in Jordan, UAE and Kuwait as a "love tap", capping the geopolitical premium built up over the last three sessions (TheStreet, Yahoo Finance).
Pre-market movers
- Snowflake (SNOW) — sharply higher on strong AI-driven earnings, per CNBC's Sept 3 premarket rundown.
- Broadcom (AVGO) — trading softer despite a solid Q3 report as guidance failed to clear the very high bar set by Nvidia last week (Yahoo Finance, Benzinga).
- Moderna (MRNA) — flagged by CNBC among biggest early movers.
- Mega-cap context: post-Nvidia's blowout ($96.2B revenue, +106% YoY) the AI-hardware trade remains the market's centre of gravity; watch NVDA, AVGO and CRM tape for follow-through (Investing.com).
Earnings today & calendar
- Lululemon (LULU) — after the close. Consensus Q2 EPS ~$1.80 on revenue ~$2.46B. Focus is on full-year guidance (UBS flags a possible cut to $9.70–9.90 from $10.95–11.15), China growth, and US full-price selling (TIKR).
- Also on tap after the bell: DocuSign (DOCU) and a handful of smaller names.
Macro today
- 8:30 AM ET — Initial Jobless Claims: est 205K vs prior 203K. A hotter print would keep the "labour cooling but not cracking" narrative intact and back the Fed's cautious tone (Investing.com).
- 8:30 AM ET — Trade Balance (Jul): est -$86.4B vs prior -$73.3B. A wider gap would trim Q3 GDP tracking a touch.
- 8:30 AM ET — Nonfarm Productivity (Q2 final): est +1.4% vs prior +0.8%; Unit Labor Costs est +1.3%. A soft ULC print would ease wage-driven inflation fears.
- 9:45 AM ET — S&P Global Services PMI (final): est 56.8 vs flash 54.6; Composite est 56.0 vs 54.5 (Investing.com).
- 10:00 AM ET — ISM Services PMI: est 54.2 vs prior 54.1. Watch the Prices Paid sub-index — last month's 70.3 is the hottest since early 2023 and a further push higher would revive stagflation talk.
- Fed's Waller speaks pre-open — market wants any nod on how he views the balance of jobs risk vs sticky services inflation into the Sept meeting.
- Also released overnight: Challenger reported 52,881 August job cuts, up 58% MoM but down 38% YoY — the lowest August since 2022 (TheStreet).
Rates, dollar & commodities
- US 10Y yield: 4.774%, down ~2 bp on the day, off yesterday's multi-month highs (Investing.com).
- DXY: ~98.96, -0.64% — dollar broadly weaker as yields drift lower (Trading Economics).
- Brent: back above $95/bbl, cited at ~$97.45 (+1.90%); WTI: ~$91.58 (+0.63%), also cited at $92.94 (+2.12%) — oil is holding its Iran-strike premium (Yahoo Finance, TheStreet).
- Gold: ~$4,478/oz, +1.45% — bid on softer dollar plus geopolitics (Yahoo Finance).
- Bitcoin: ~$77,708, +1.30%; VIX: 15.19, essentially flat (Yahoo Finance).
Overnight global context
- Asia mixed: Japan's Nikkei 225 slipped -0.17% to 64,214, while the broader Topix rose +0.5% to 4,102 — after Wednesday's -2.85% flush (Trading Economics).
- Europe cautious near session-lows: Euro STOXX 50 ~6,359 (-0.06%), DAX ~25,851 (+0.05%), CAC 40 ~8,261 (-0.23%) — one-month lows as geopolitics offsets easing yields (Trading Economics).
What to watch at the open
Watch ISM Services Prices Paid at 10:00 — another sticky print would re-price Fed cut odds and pressure duration. Second, the AVGO tape is the reference trade for whether the AI-hardware complex can keep bidding a market that has been leaning heavily on it. Third, keep an eye on oil and gold: a fresh Iran headline is the tail risk that can flip a modestly green tape red before lunch.
As of 09:24 ET, Sep 3, 2026. Sources: Yahoo Finance live blog, TheStreet, Investing.com — Thursday US data, Investing.com — US 10Y, Trading Economics — DXY, Trading Economics — Nikkei, Trading Economics — Europe, TIKR — Lululemon preview. Automated US market brief for discussion and education only — not investment advice. Verify before acting.
This article is for educational and informational purposes only. It is not financial advice, investment recommendation, or a solicitation to buy or sell securities. Investing involves significant risks. I am not a SEBI-registered investment advisor. Readers should consult their own financial advisor and conduct their own research before making any investment decisions.
Comments
Join the conversation
Sign in to join the conversation.
Follow replies, add your view, and take part in the discussion.
Sign in to commentLoading comments...