

Pre-Market Global Brief — Sep 08, 2026 | Nifty, Nasdaq, Nikkei, DAX & more
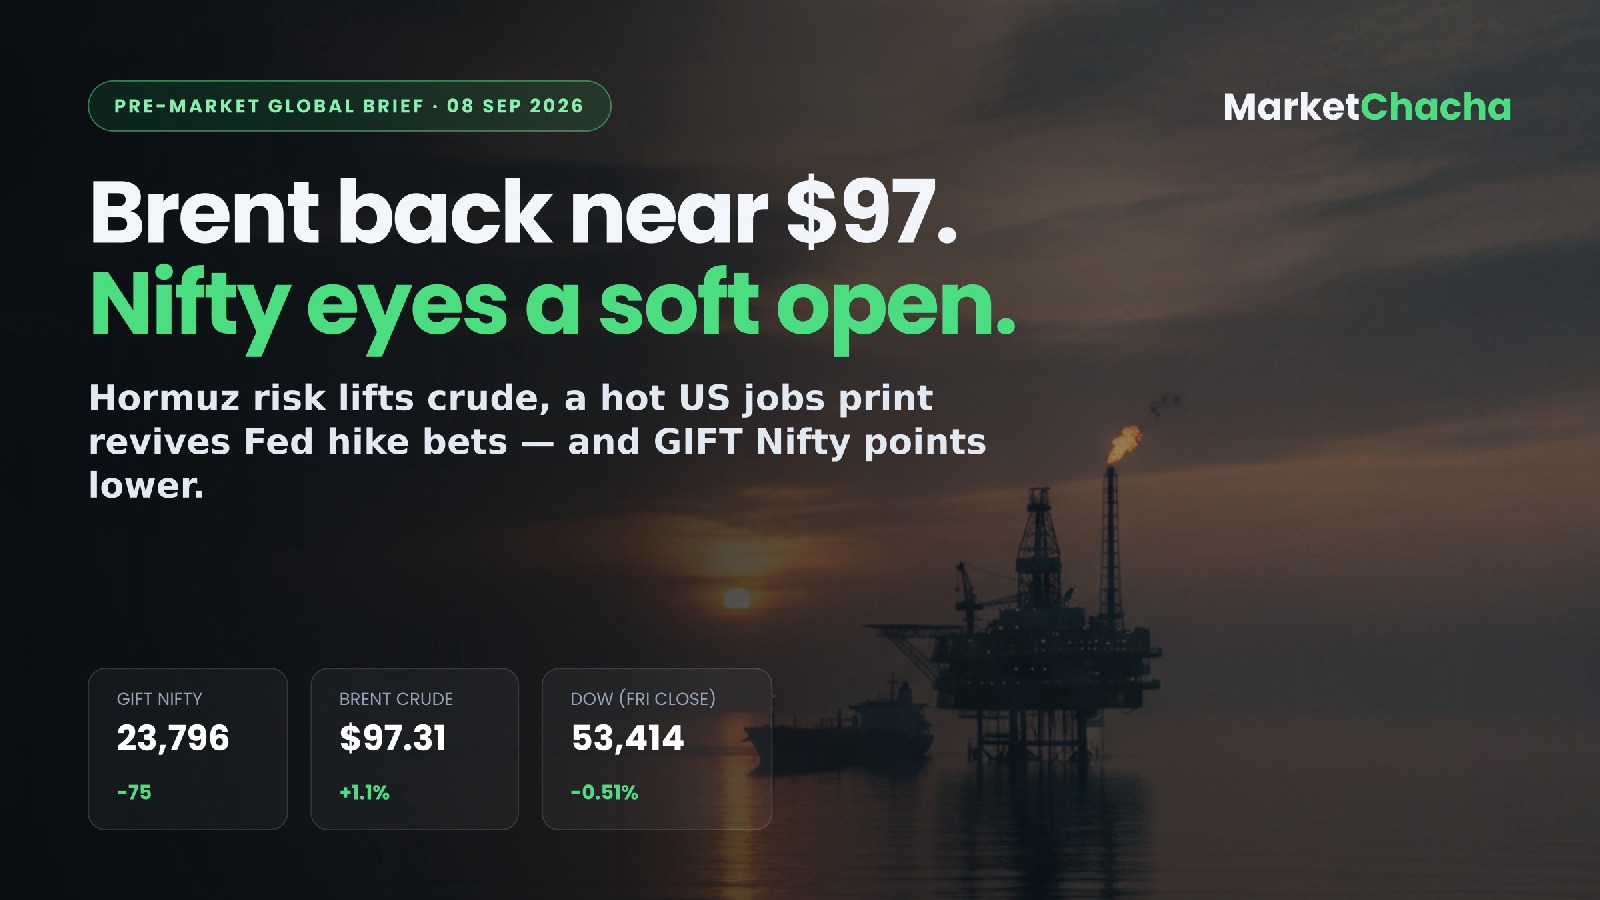
Asia is mixed and crude is grinding higher, but the single biggest driver for India's open is Brent back near $97 on Strait of Hormuz risk — GIFT Nifty is signalling a lower start after Nifty's 0.5% slide on Monday.
US: prior close (Friday 4 Sep — Monday was Labor Day)
- Dow 53,414.25, −271.85 (−0.51%); S&P 500 7,718.60, −29.11 (−0.38%); Nasdaq 26,506.99, −77.11 (−0.29%) — Yahoo Finance.
- Why: August non-farm payrolls came in at 162,000 vs a ~55,000 consensus, unemployment steady at 4.1%. Good news was bad news: the 10-year Treasury yield rose to 4.78% and traders now price roughly a 60% chance of a Fed rate HIKE at the 15–16 September FOMC (TheStreet, Reuters).
Asia now
- Nikkei 225 66,543 (+0.22%) · Kospi 7,128 (+1.90%) · Shanghai Composite 3,939 (+0.17%) · Hang Seng 25,320 (−0.37%) · ASX 200 −0.38% — Kaohoon International.
- The yen is at a seven-month high (~153.5/$) on Bank of Japan hike bets; dollar index 98.83 (Reuters).
Europe: Monday close
- FTSE 100 14,666 (+0.20%), CAC 40 +0.33%, DAX −0.04%; Euro Stoxx 50 futures +0.17% this morning.
India lead
- GIFT Nifty ~23,796, down about 75 points — a discount to Monday's close, pointing to a soft/negative open (Business Standard).
- Monday's close: Nifty 23,779.15 (−0.50%), Sensex 76,132.81 (−0.50%). Nifty IT fell over 2%; Pharma was the lone sectoral gainer.
Commodities, currency, yields
- Brent $97.31 (+1.1%), WTI $92.65 (+1.3%) — Iran has warned of retaliation against regional energy infrastructure after US strikes.
- Gold little changed near $4,400/oz; LME copper hit a record ~$14,533/tonne.
- USD/INR 94.39 (Monday, +4 paise); analysts flag 94.00–94.20 as support, with 95–96 in play if tensions escalate (HDFC Sky). US 10Y 4.78%.
Data due
- India: nothing major scheduled today. August CPI is due 14 September (Trading Economics forecast 4.7% vs 4.45% in July) — a hot print alongside $97 oil would harden the RBI's pause.
- US today: NFIB Small Business Optimism (Aug, cons. ~99.8) and July Consumer Credit (cons. ~$14.2bn). Japan: Reuters Tankan (Sep, cons. 18).
- Overnight: Japan Q2 final GDP, Euro Area Q2 GDP (3rd est.), China August FX reserves (cons. $3.419tn vs $3.438tn).
- Ahead: US CPI Friday 11 September plus China CPI/PPI, then the FOMC on 15–16 September. A hot US CPI would push yields and the dollar up and pressure Indian IT and rate-sensitives; a soft print is the main relief valve this week.
Other movers
- Tehran has announced an arrangement with Oman to jointly manage the Strait of Hormuz; markets are waiting on the US response.
- Primary market: Deepa Jewellers and Rays of Belief list today; Kanohar Electricals, Prasol Chemicals and Glass Wall Systems open 8–10 September.
What it means for the India open
Sentiment is risk-off with an energy tilt. Expect a lower start with oil marketing companies, paints, aviation and tyres in focus on the crude move, and IT still nursing Monday's 2% fall as US rate-hike odds climb. On the charts, 23,721 is the first support and the 100-DMA near 24,023 is the level bulls need to reclaim (5paisa); until then rallies are likely to be sold.
As of 09:00 IST, 8 September 2026. Figures as reported by: Yahoo Finance, TheStreet, Business Standard, Kaohoon International, Reuters/Business Recorder, HDFC Sky, Trading Economics, 5paisa. Levels are as reported by these publications, not a live exchange feed. Automated pre-market brief for discussion and education only — not investment advice. Verify before acting.
This article is for educational and informational purposes only. It is not financial advice, investment recommendation, or a solicitation to buy or sell securities. Investing involves significant risks. I am not a SEBI-registered investment advisor. Readers should consult their own financial advisor and conduct their own research before making any investment decisions.
Comments
Join the conversation
Sign in to join the conversation.
Follow replies, add your view, and take part in the discussion.
Sign in to commentLoading comments...