

Post-Market Wrap — Sep 07, 2026 | How India & the world closed
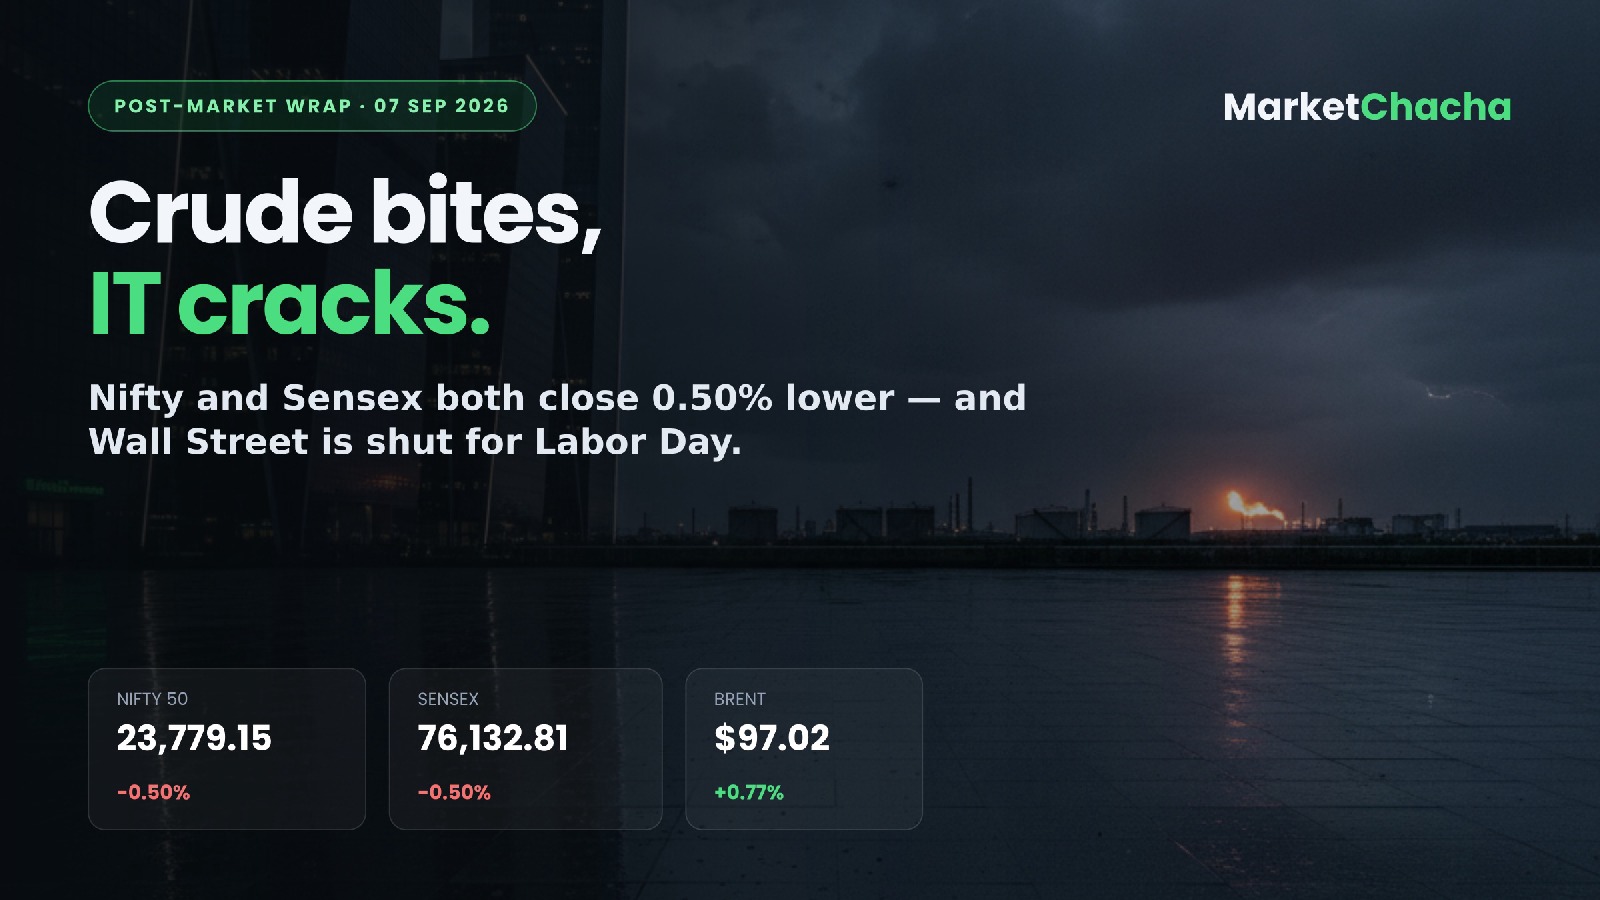
India closed lower for a second straight week's start, with the Nifty 50 and Sensex both down 0.50% as a jump in crude past $97 and revived bets on a US rate hike knocked IT and cyclicals.
How India closed
- Nifty 50 — 23,779.15, down 118.55 pts (-0.50%)
- Sensex — 76,132.81, down 382.62 pts (-0.50%)
- Nifty Midcap 100 — down 0.46%; Nifty Smallcap 100 — up 0.02%
- Bank Nifty — n/a (no verified close available at the time of writing)
Reuters reported 14 of 16 major sectors ended lower. Breadth was better below the surface: smallcaps held flat even as the frontline fell.
Sectors and stocks
Laggards: IT was the worst hit, down roughly 2% — a stronger-than-expected US jobs report lifted rate-hike odds, and higher-for-longer US rates squeeze the discretionary tech budgets Indian IT depends on. Metal, PSU Bank, Realty and Media also fell. Leaders: Pharma and Healthcare closed higher.
- Nifty50 top losers: Infosys, SBI Life, HDFC Life. Bucking the trend: Bharti Airtel, Bharat Electronics, L&T.
- PVR Inox -6.5% on reports of a senior executive exit tied to alleged developer kickbacks.
- Zee Entertainment -4% after charges were filed against Essel Group chair Subhash Chandra over alleged fraud involving LIC Housing Finance.
- Indoco Remedies -3% following US FDA inspection findings at its Goa plant.
- Purple Style Labs listed weak, debuting at a 7% discount to its issue price.
Flows, currency, commodities
Today's provisional FII/DII numbers were not published at the time of writing. The latest available (4 September) showed FIIs net sellers of Rs 3,111.90 crore and DIIs net buyers of Rs 8,930.10 crore in cash. USD/INR was around 94.44, effectively flat (+0.01%). Brent $97.02/bbl (+0.77%) and WTI $91.80 (+0.35%) on US-Iran tension around the Strait of Hormuz — the single biggest external pressure on Indian equities today. Gold $4,398.90/oz (-0.76%).
Global now
US markets are shut for Labor Day, so there is no Wall Street cash session or meaningful futures signal tonight — a thin, low-conviction global tape. In Europe, the FTSE 100 was slightly lower near 10,817 (-0.13%), with Unilever and BAT weak while Shell and BP gained on firm crude. In Asia, the Nikkei 225 jumped 1.96% to 66,330 on AI and semiconductor strength (Kioxia +7.2%, SoftBank +6.1%).
Data: today and ahead
No major Indian macro print landed today. The last release was forex reserves at $740.8bn (week to 28 Aug), up from $729.33bn. Ahead: 8 Sep — China August trade balance (consensus $120.1bn), Eurozone Q2 GDP third estimate (+0.4% q/q), US NFIB and consumer credit. 9 Sep — China August CPI (cons. 0.9% y/y) and PPI (3.6%). 10 Sep — US PPI (cons. +0.3% m/m) and initial jobless claims (cons. 205k). 11 Sep — US August CPI (cons. +0.4% m/m, 3.4% y/y; core 2.4% y/y) plus India's next forex reserves. India's own CPI/WPI land 14 Sep (CPI consensus 4.45%), trade and passenger vehicle sales 15 Sep. The FOMC decides 16 Sep.
Sentiment and what to watch
Risk-off, but orderly — a rates-and-oil derating rather than panic, with domestic flows still cushioning foreign selling. Watch whether Brent holds above $95: sustained crude at these levels feeds straight into India's import bill, the rupee and the inflation path the RBI is watching. Watch the IT complex on Tuesday, since it is the cleanest read on how the market is pricing a September Fed hike. And watch Friday's US CPI — a hot core print would harden rate-hike expectations into the FOMC and keep pressure on exporters and high-multiple midcaps.
As of 4:00 PM IST, 7 September 2026. Sources: Business Standard, Reuters, The Week, Trading Economics, 5paisa, Yahoo Finance. All prices and index levels are as reported by these sources, not live exchange data. Automated market wrap for discussion and education only — not investment advice. Verify before acting.
This article is for educational and informational purposes only. It is not financial advice, investment recommendation, or a solicitation to buy or sell securities. Investing involves significant risks. I am not a SEBI-registered investment advisor. Readers should consult their own financial advisor and conduct their own research before making any investment decisions.
Comments
Join the conversation
Sign in to join the conversation.
Follow replies, add your view, and take part in the discussion.
Sign in to commentLoading comments...