

Pre-Market Global Brief — Sep 16: GIFT Nifty up 51 into a Fed set to hike to 4%
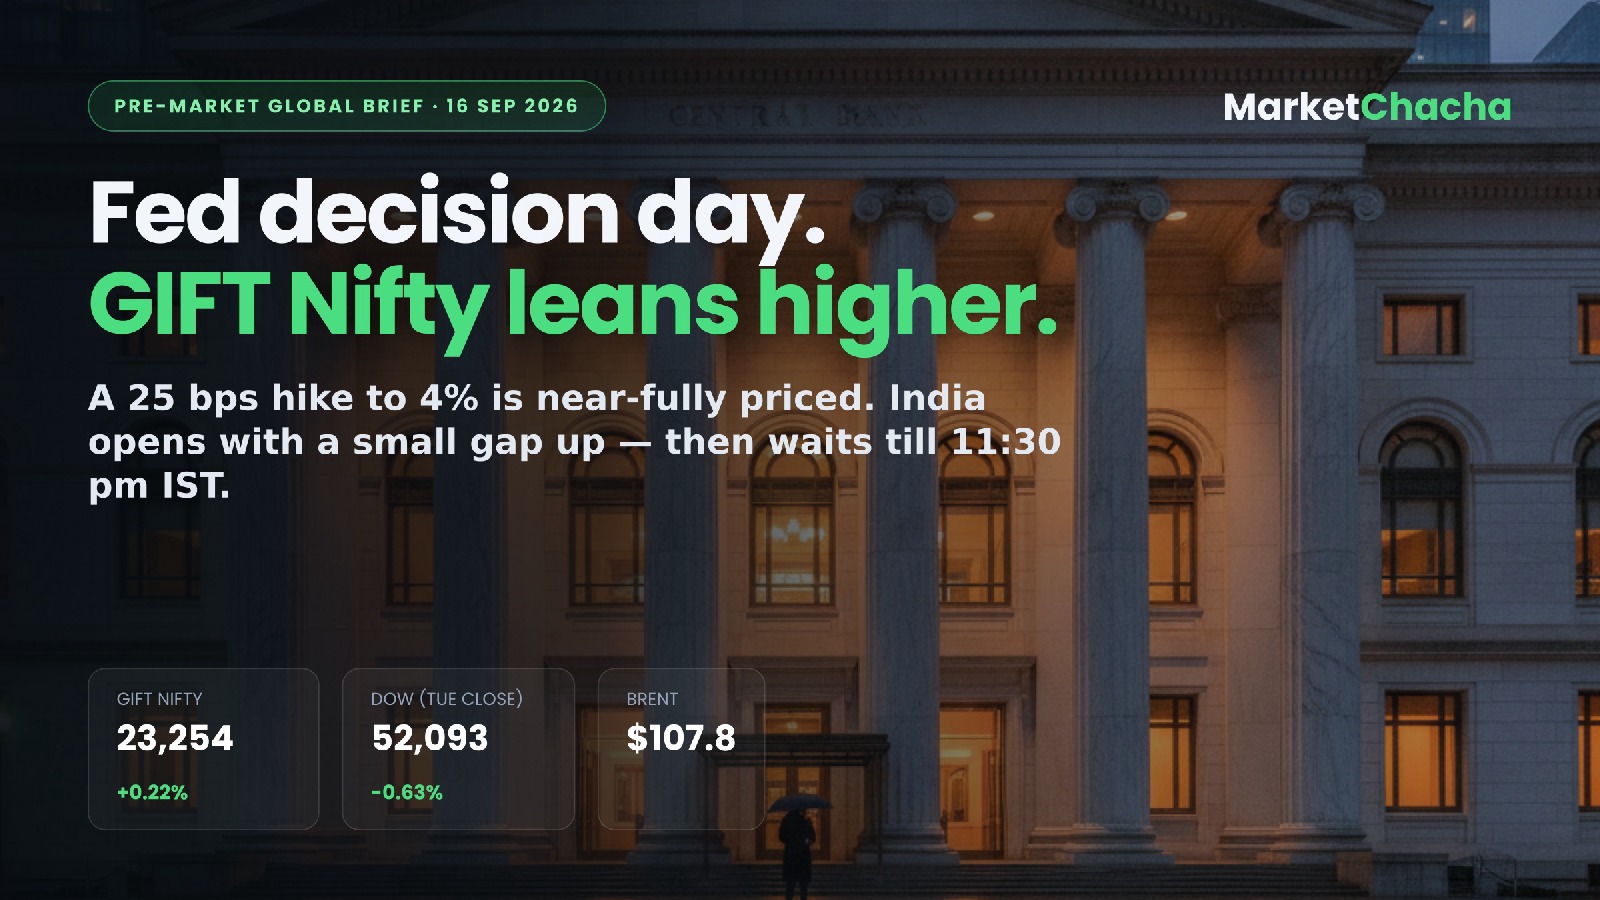
Wall Street drifted lower for a third day and Asia is mixed this morning, but the single thing that decides India's day isn't on screen yet — the Fed's rate decision at 11:30 pm IST, where a hike to 4% is close to fully priced. GIFT Nifty is still pointing a little higher after Nifty's five-month low.
India lead: a small gap up, then a long wait
GIFT Nifty was at 23,254, up 51 points (+0.22%) at 08:47 IST, implying a gap-up open of roughly 34 points, per NiftyTrader. That follows Tuesday: Nifty 50 closed 23,118.60 (−1.19%), its lowest in five months, Sensex 74,003.82 (−777.94, −1.04%)(Trading Economics, HDFC Sky). Financials fell ~1.8% and autos ~2.0%, while Nifty IT rose 2.2% — HCLTECH +3.95% and INFY +3.79% led, BEL fell 5.3%. Full list on movers.
US prior close: caution, not panic
Yahoo Finance data for Tuesday: Dow 52,093.10 (−0.63%), S&P 500 7,585.73 (−0.45%), Nasdaq Composite 25,981.57 (−0.78%). Pre-Fed positioning, not a fresh AI scare: NVDA actually rose 0.57%, while MSFT (−1.64%) and AVGO (−1.58%) dragged.
Asia now, Europe last night
- Asia (live, ~08:45 IST): Nikkei 225 63,396 (−0.14%), Hang Seng 24,643 (−0.10%), Shanghai 3,866 (+0.05%), Kospi 6,657 (+0.45%).
- Europe (Tue close): DAX 25,402.28 (−0.15%), FTSE 100 10,658.10 (−0.37%), Euro Stoxx 50 6,236.50 (−0.38%).
Commodities, currency, yields
Brent $107.76, WTI $104.48 — off Tuesday's spike but still the core problem for India's import bill. Gold $4,367/oz. USD/INR 95.96, dollar index 99.65, US 10-year ~4.99% after touching 5%, India's 10-year 7.10% (Trading Economics). A 5% US yield plus a 96 rupee is what keeps FIIs selling.
Sentiment: mildly risk-off. Costly oil, a 5% US 10-year and a central bank about to tighten into it is not a mix that invites buying — though positioning looks defensive rather than distressed.
Data due today (full calendar)
- US FOMC, 11:30 pm IST — 3.75% now, consensus 4.00% (~93% priced on CME FedWatch, per Kiplinger); first hike since 2023. Dot plot with it; Chair Warsh speaks at 12:00 am IST. A hike plus a hawkish dot plot lifts the dollar and yields and pressures the rupee — bad for Indian financials, helpful for IT. A hold would be a big dovish surprise.
- US retail sales (Aug), 6:00 pm IST — consensus +0.8% MoM vs −0.6% prior. A beat hardens the hawkish case.
- UK CPI (Aug), 11:30 am IST — consensus 3.1% vs 2.9%. Euro area industrial production and wage growth, 2:30 pm IST; ECB's Lagarde, 10:30 pm IST; EIA crude stocks, 8:00 pm IST — the oil swing factor.
- India: M3 money supply (Aug 31) at 5:00 pm IST, prior 14.2%. Already out: August passenger vehicle sales +33.2% YoY vs +31.2%. Earlier this week: August CPI 4.82%, and a trade deficit that narrowed to $26.86bn from $31.98bn, far below the ~$33bn consensus.
What it means for the India open today
Expect a modestly higher start and then little conviction — few will carry size into the Fed. Watch oil and the rupee intraday: another leg up in Brent, or a push past 96 on USD/INR, would likely undo the gap-up. The real move is tomorrow morning's reaction, not today's open.
As of 08:50 IST, 16 September 2026. Sources: Trading Economics, Yahoo Finance, NiftyTrader, HDFC Sky, Kiplinger. Levels are as reported by these sources, not live exchange data. Automated pre-market brief for discussion and education only — not investment advice. Verify before acting.
This article is for educational and informational purposes only. It is not financial advice, investment recommendation, or a solicitation to buy or sell securities. Investing involves significant risks. I am not a SEBI-registered investment advisor. Readers should consult their own financial advisor and conduct their own research before making any investment decisions.
Comments
Join the conversation
Sign in to join the conversation.
Follow replies, add your view, and take part in the discussion.
Sign in to commentLoading comments...