

Pre-Market Global Brief — Sep 10, 2026 | Nifty, Nasdaq, Nikkei, DAX & more
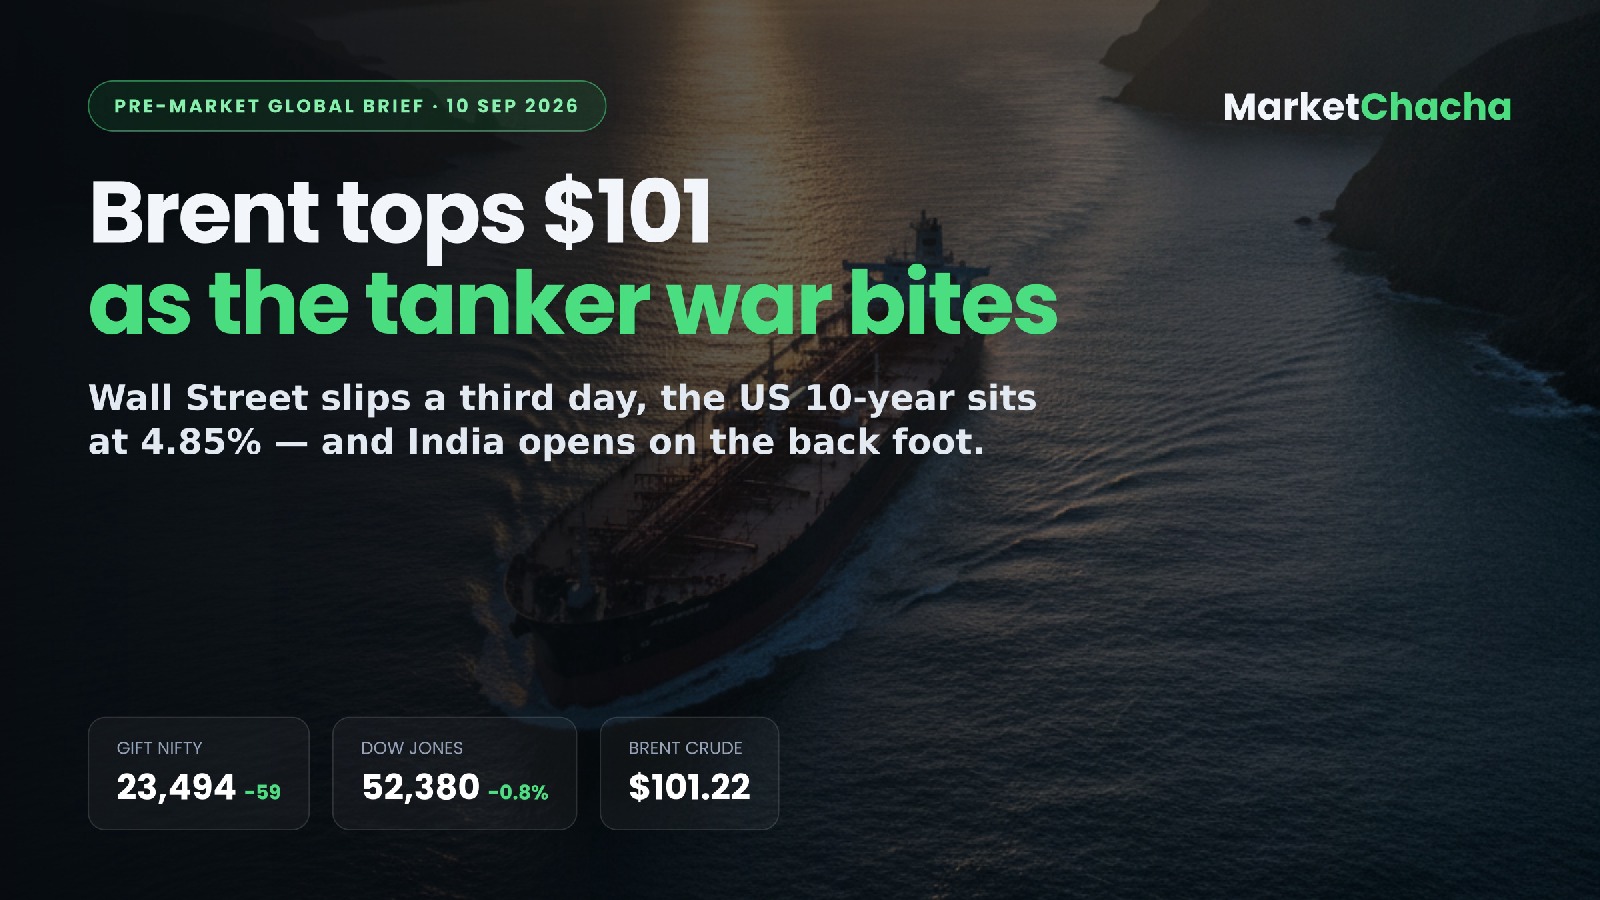
Overnight tone stayed risk-off as the US–Iran tanker conflict pushed Brent back above $101 a barrel — an oil shock that is lifting global bond yields, pressuring the rupee and setting India up for a soft open.
US: a third straight down day
- Dow Jones closed at 52,380.66, down 405.41 pts (-0.8%)
- S&P 500 at 7,636.36, down 37.16 pts (-0.5%)
- Nasdaq Composite at 26,253.34, down 168.07 pts (-0.6%)
Why: AP reports Brent jumped 3.4% back above $100 for the first time since July after US strikes on Iranian tankers disrupted flows through the Strait of Hormuz. Yahoo Finance reports traders now price roughly a 60% chance of a 25bps Fed rate HIKE this month — inflation, not growth, is the market's problem right now. Movers per TheStreet: Meta +5.4% (Muse AI agent launch), nCino +12.5%, Signet +10%; Casey's -16.5%, Booking -4.3%, UnitedHealth -4.2%. Dow and S&P futures were marginally higher this morning (+0.25% / +0.17%, Business Standard).
Asia right now
- Nikkei 225 ~64,510, -0.97% — oil-led inflation fears plus a near seven-month high yen hurting exporters (Trading Economics)
- Kospi -1.7%, giving back Wednesday's 1.4% chip-led rally (Business Standard / Trading Economics)
- Hang Seng ~25,241, -0.30%; Shanghai Composite ~3,952 — China's August CPI came in at +0.8% y/y and PPI at +3.8% y/y, both energy-inflated (Trading Economics)
Europe: prior close
Per Trading Economics, DAX 25,596 (-1.58%), FTSE 100 10,710 (-0.94%), Euro Stoxx 50 6,291 (-1.90%) — Europe took the deepest hit, being the most energy-import-exposed bloc.
India lead: GIFT Nifty points lower
Business Standard reports GIFT Nifty at 23,494, down 59 points, signalling a negative open. That follows a third straight fall: Nifty 50 closed 23,431.50 (-203.60, -0.86%) and Sensex 74,764.23 (-813.35, -1.08%), with Nifty IT down over 3% and metals the only real outperformer. Flows on Sep 9 (5paisa): FIIs net sold Rs 583 cr, DIIs net bought Rs 1,509 cr.
Commodities, currency, yields
- Brent $101.22 (-0.43% this morning); WTI ~$96.04 after a 3.24% surge (Business Standard / Trading Economics)
- Gold ~$4,424/oz, +1.58% — classic haven bid
- USD/INR ~95.11, +0.28%; DXY 98.78, flat. Trading Economics notes RBI intervention on Tuesday was seen as insufficient
- US 10Y 4.85%, up 1bp and near multi-decade highs
Economic data due today
- ECB rate decision, ~5:45 pm IST — prediction markets were pricing near-certainty of a +25bps hike to a 2.50% deposit rate. A hike confirms the global tightening turn; a hold would be a big dovish surprise and risk-positive for EMs.
- US PPI (Aug) + weekly jobless claims, 6:00 pm IST (Kiplinger). A hot PPI hardens the Fed-hike case — bad for Indian IT, rate-sensitives and the rupee. A soft print is the single best thing that could happen to Dalal Street today.
- US wholesale trade (Jul) and existing home sales (Aug), 7:30 pm IST.
- US CPI (Aug) lands tomorrow — expect positioning caution into the close.
- India: no top-tier print today. RBI's weekly forex reserves are due around end-week; CPI, WPI and trade data are slated for Sept 14–15 — note Sept 14 is a market holiday (Ganesh Chaturthi).
What it means for the India open today
India imports over 85% of its crude, so $101 Brent is a direct hit to the import bill, the rupee and the inflation path — that is one channel doing all the damage. Expect pressure on OMCs, paints, aviation and tyres, relative resilience in upstream oil and metals, and continued weakness in IT as US rate-hike odds climb. With five IPOs opening today (Veegaland Developers, Maharaja & Speedex, Om Galaxy, Raksan Transformers, Panchtatv Bharat), watch whether the SME/primary bid holds up as a sentiment tell.
As of 8:45 AM IST, 10 September 2026. Figures as reported by the sources cited: Business Standard, AP, Trading Economics, TheStreet, Kiplinger, 5paisa. This is attributed journalism, not a live quote feed. Automated pre-market brief for discussion and education only — not investment advice. Verify before acting.
This article is for educational and informational purposes only. It is not financial advice, investment recommendation, or a solicitation to buy or sell securities. Investing involves significant risks. I am not a SEBI-registered investment advisor. Readers should consult their own financial advisor and conduct their own research before making any investment decisions.
Comments
Join the conversation
Sign in to join the conversation.
Follow replies, add your view, and take part in the discussion.
Sign in to commentLoading comments...