

Pre-Market Global Brief — Sep 04, 2026 | Nifty, Nasdaq, Nikkei, DAX & more
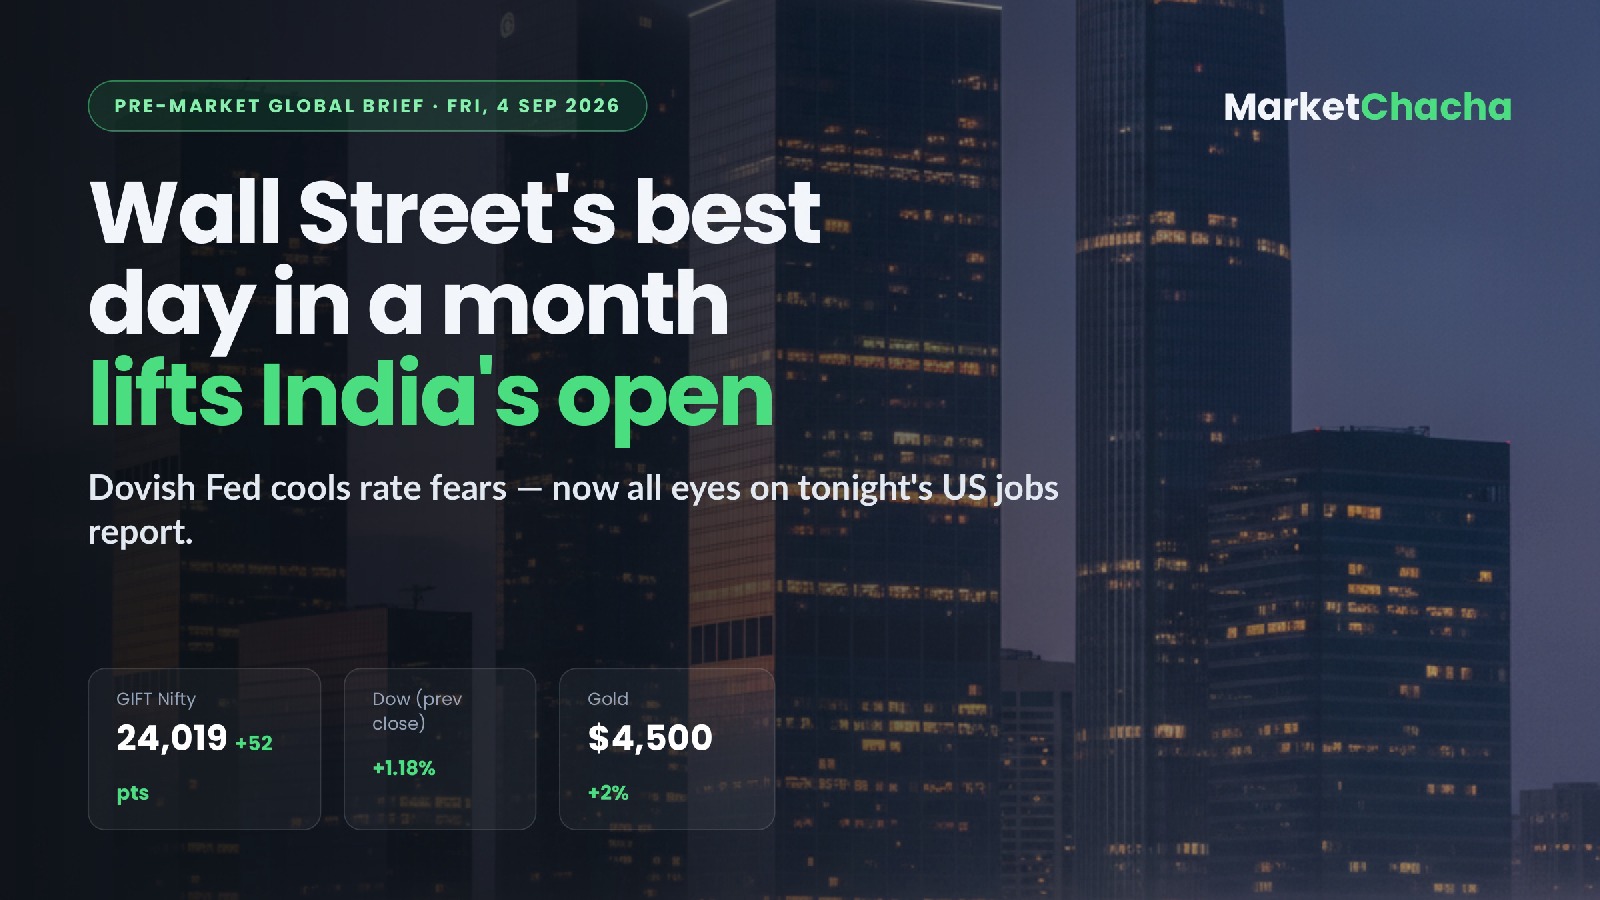
A dovish tilt from the US Federal Reserve has flipped the global mood risk-on — Wall Street just posted its best day in a month and Asia is rallying, setting up a firm, gap-up start for the Nifty. The one thing that can rewrite the day: tonight's US jobs report.
US prior close (Sep 3) — best day in a month
Comments from Fed Governor Christopher Waller that he could support holding rates steady if disinflation continues cooled rate-hike fears and pulled Treasury yields lower. As reported by Business Standard and Yahoo Finance: Dow +1.18% to 53,686, S&P 500 +1.06% to 7,667, Nasdaq +1.4% to 26,218.
Asia live now
Green across the board ahead of US payrolls, per Reuters: Nikkei ~+0.8%, Chinese blue-chips ~+1%, Kospi ~+1.1%, Hang Seng near 25,300. The yen has firmed ~2.6% on the week (~155.7/$) as the dollar retreats.
Europe (Sep 3 close)
Mixed, before the US turn: DAX -1.09%, CAC 40 -0.79%, FTSE 100 +0.29%, FTSE MIB +0.10% — weighed by firm oil and Middle-East tension (Business Standard).
India lead
GIFT Nifty ~24,019, up ~52 points, signalling a positive open for Nifty and Sensex (Business Standard).
Commodities & currency
- Brent ~$95-96, WTI ~$90 — elevated on Iran/Strait of Hormuz worries (Trading Economics, Convex).
- Gold surging ~$4,480-4,500/oz (+2%) as the dollar and yields slip (Forbes, Trading Economics).
- USD/INR ~94.4-95.0; Dollar index (DXY) ~99.0 and softening; US 10Y yield ~4.74% (Investing.com, Trading Economics).
Global sentiment
Risk-on — the driver is Waller's dovish signal easing Fed-hike fears, offset only by pre-jobs caution and sticky oil.
Economic data due today
US Non-Farm Payrolls — 6:00 PM IST (the day's marquee event). Forecast ~+55-56K vs a shock -23K prior; unemployment seen steady at 4.1%; average hourly earnings ~+3.0% y/y (Investing.com). A soft print cements bets on a Fed pause/cut — dollar-negative and bullish for Indian equities and IT; a hot beat could revive yields and pressure the rupee. No major India macro release is scheduled today.
What it means for the India open
Expect a positive start led by rate-sensitive banks, IT and metals as global risk appetite returns and yields cool. But upside may stay capped into the afternoon — most desks will keep powder dry until the 6 PM US jobs number, which sets the tone for next week. Elevated crude is the standing risk for oil-marketing and paint/aviation names.
As of 08:45 IST, 4 Sep 2026. Sources: Business Standard, Yahoo Finance, Reuters/Investing.com, Trading Economics, Forbes, Investing.com. Automated pre-market brief for discussion and education only — not investment advice. Verify before acting.
This article is for educational and informational purposes only. It is not financial advice, investment recommendation, or a solicitation to buy or sell securities. Investing involves significant risks. I am not a SEBI-registered investment advisor. Readers should consult their own financial advisor and conduct their own research before making any investment decisions.
Comments
Join the conversation
Sign in to join the conversation.
Follow replies, add your view, and take part in the discussion.
Sign in to commentLoading comments...