

Post-Market Wrap — Sep 16, 2026 | How India & the world closed
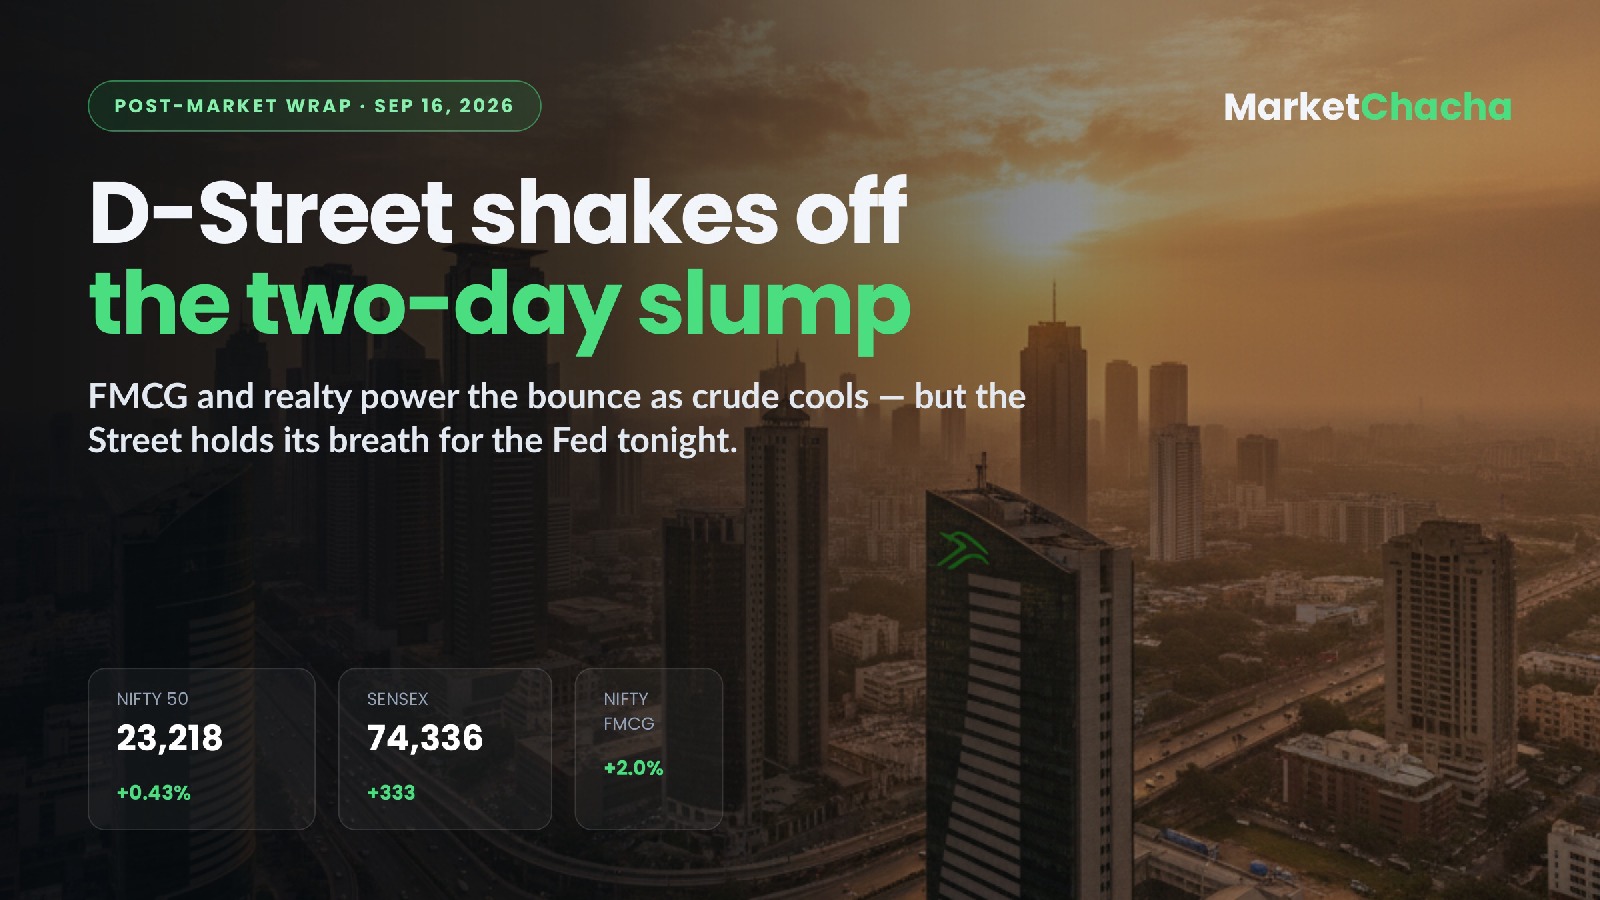
Indian equities snapped a two-day slump on Wednesday, with the Sensex closing up 332.63 points (0.45%) at 74,336.45 and the Nifty 50 adding 99 points (0.43%) to settle at 23,217.60, as festive-season buying in consumer stocks and a pause in the crude rally lifted sentiment — even as traders stayed cautious ahead of the US Federal Reserve's decision due tonight (as reported by Business Standard).
How India closed
- Nifty 50: +99 pts / +0.43% to 23,217.60
- Sensex: +332.63 pts / +0.45% to 74,336.45
- Broader market lagged the benchmarks: Nifty Midcap ended roughly flat (about -0.01%) and the Smallcap 100 slipped ~0.18%, extending its losing streak to a fifth session. BSE breadth stayed negative (1,621 advances vs 2,355 declines).
The bounce was a relief rally, not a trend change: benchmarks recovered after crude eased and Asian peers firmed, but participants kept positions light before the Fed.
Sectors & stocks — what moved and why
- FMCG led, up ~2%, snapping a four-day slide as festive demand put HUL, ITC, Dabur, Emami, Godrej Consumer and P&G Hygiene in focus (Business Standard).
- Realty rebounded +1.19%, snapping a seven-day losing streak (it had fallen ~11% over those sessions), led by Oberoi Realty (+2.55%) and Lodha (+1.62%). PSU Banks also supported.
- IT and Pharma lagged — the drag on an otherwise green tape. Divi's Labs fell for a fifth straight session.
- Stock stories: Tata Chemicals swung wildly, rebounding ~14% off its intraday low (up ~29% in two days) on heavy volume. On the weak side, MTAR Technologies, HFCL, Sterlite Technologies and HEG were locked in 5% lower circuits, and recent listing Pranav Constructions slid ~20% (down ~37% in two days) below its issue price. Kanohar Electricals debuted at a ~9% premium; the Hero Motors IPO was subscribed 1.01x on day one.
FII / DII
Same-day provisional cash-market FII/DII figures were not yet available at the time of writing (n/a). For context, Business Standard notes FIIs have been heavy sellers in index futures this month (~₹14,477 cr sold in September), keeping the tape defensive.
Currency & commodities
- USD/INR: the rupee edged lower to ~95.97 versus its previous close of 95.88, hovering near record-weak levels.
- Crude: Brent (November) eased ~0.5% to about $108.19/bbl as US inventories rose — still elevated, a key pressure point for India.
- Gold: MCX October gold rose 0.66% to ₹1,51,800.
- Rates: India's 10-year yield eased to 7.063%; the US 10-year sat near 5.01% and the dollar index around 99.6.
Global now
Asia closed higher — Japanese stocks recovered as lower oil eased pressure, and China gained on trade hopes and AI names. Europe opened cautiously firmer, with Euro Stoxx 50, DAX and FTSE futures up around 0.3% (Investing.com). All eyes are on the US Federal Reserve decision tonight (2:00 PM ET) — rate call, updated projections and Chair Powell's press conference — which set the tone for tomorrow's session.
Economic data
India's key prints landed earlier this week (Sep 14): CPI retail inflation rose to 4.82% in August (from 4.45% in July), a third straight month above the RBI's 4% target, with food inflation at 5.95%. WPI wholesale inflation climbed to 9.92% (from 9.78%), driven by fuel & power at 22.93%. Separately, the current account deficit widened to $11.2 billion in Apr–Jul 2026 on a bigger goods-trade gap. Tonight/tomorrow the global calendar is dominated by the FOMC decision, alongside US retail sales and weekly crude inventories.
Sentiment & what to watch
The read is cautiously risk-on — a technical bounce on cooler oil and festive optimism, but conviction is thin ahead of the Fed. Watch the FOMC outcome and Powell's tone tonight: a dovish signal could extend the rebound, while any hawkish surprise (with US 10-year yields already near 5%) would pressure rates-sensitive sectors. Domestically, keep an eye on the rupee near record lows, Brent holding around $108, and whether FMCG and realty can sustain leadership when the broader market is still soft.
As of 4:00 PM IST, Sep 16, 2026. Sources: Business Standard (market close), Business Standard (numbers to track), Business Standard (CPI), Business Standard (WPI), Investing.com (Europe/Fed). Automated market wrap for discussion and education only — not investment advice. Verify before acting.
This article is for educational and informational purposes only. It is not financial advice, investment recommendation, or a solicitation to buy or sell securities. Investing involves significant risks. I am not a SEBI-registered investment advisor. Readers should consult their own financial advisor and conduct their own research before making any investment decisions.
Comments
Join the conversation
Sign in to join the conversation.
Follow replies, add your view, and take part in the discussion.
Sign in to commentLoading comments...