

Pre-Market Global Brief — Aug 10, 2026 | Nifty, Nasdaq, Nikkei, DAX & more
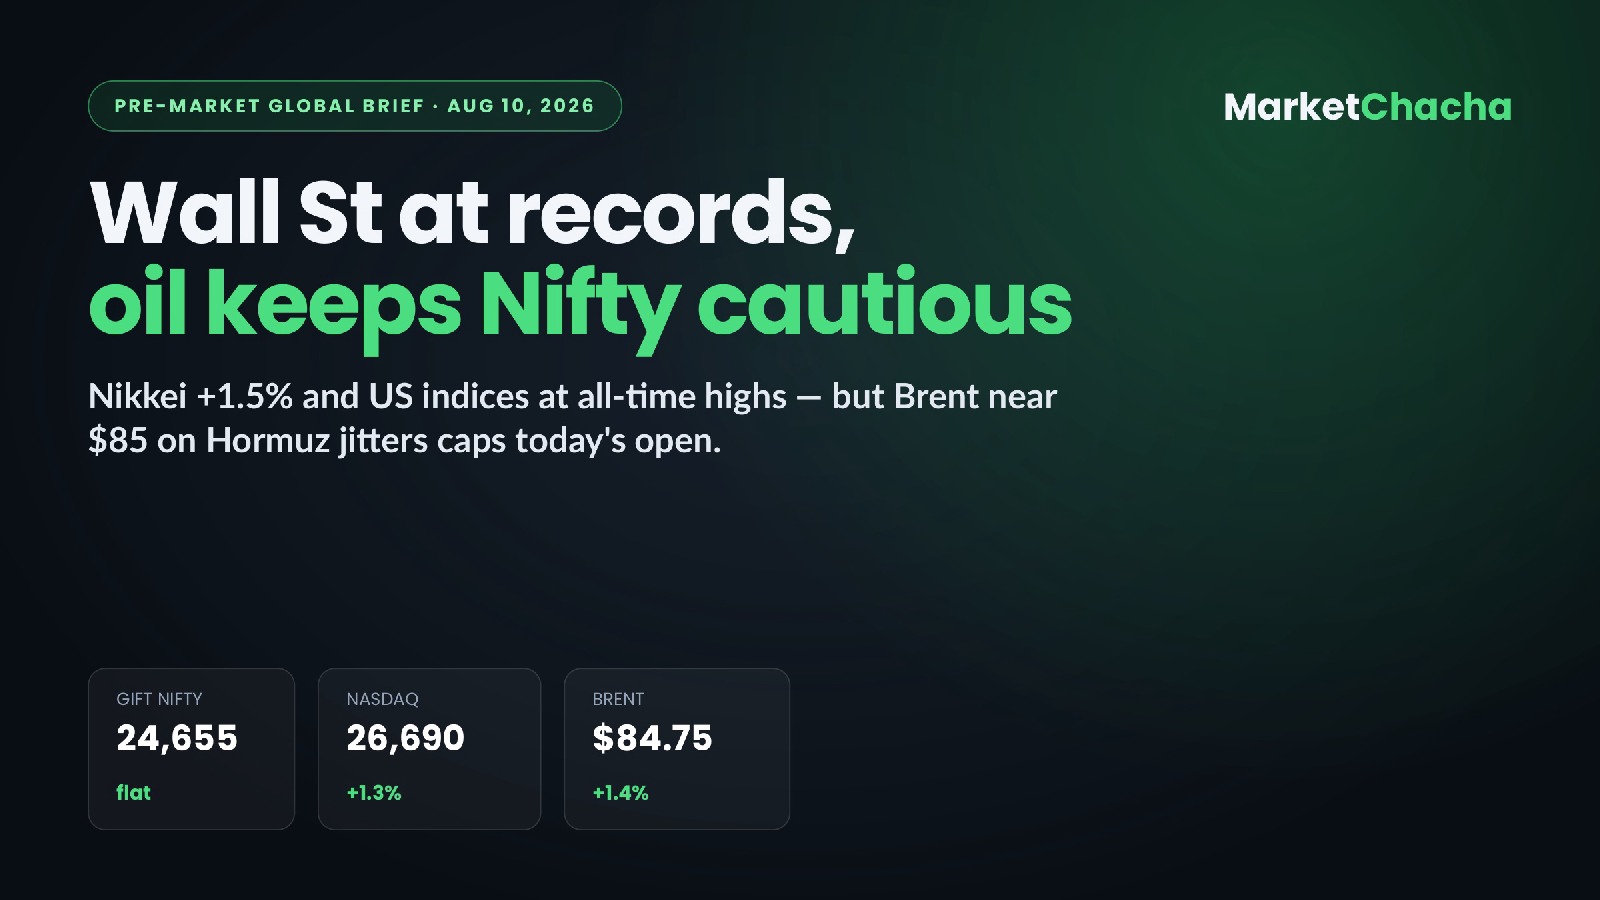
Overnight cues are supportive — Wall Street and Europe closed at fresh records on Friday and most of Asia is firmly higher this morning — but crude near $85 on Strait of Hormuz uncertainty is the swing factor keeping GIFT Nifty muted ahead of the open.
US: records after a soft jobs print
On Friday (Aug 7) the S&P 500 rose 0.62% to a record 7,757.64, the Nasdaq Composite added 1.30% to 26,690.62 and the Dow gained 0.28% to 54,036.93 (Business Standard, CNBC). The rally followed a weaker-than-expected July jobs report, which pushed traders to bet the Fed leaves rates on hold — lifting odds of a September cut.
Asia this morning
Most Asian markets advanced in early trade, tracking Wall Street. Around 8 am IST Japan's Nikkei 225 was up 1.46% and South Korea's Kospi 0.65% (Business Standard).
Europe (Friday close)
Europe also finished at records: the Euro Stoxx 50 rose 0.33% to 6,523.86 and the pan-European STOXX 600 notched a fourth straight record close, led by German tech (SAP, Infineon); the FTSE 100 also gained (MarketScreener).
India cues: GIFT Nifty
GIFT Nifty was quoted around 24,655, signalling a tepid, near-flat open for the Nifty50, which ended Friday at 24,570.65 (Business Standard). Global optimism is being offset by the oil overhang.
Commodities, currency & yields
- Oil: Brent August futures were around $84.75, up 1.44%, after Iran said it is finalising a Strait of Hormuz arrangement with Oman that only takes effect if US conditions are met; WTI was near $78.8 (Business Standard, Trading Economics).
- Gold: futures eased about 0.5% (Business Standard).
- Currency & rates: the rupee was around ₹95.3 to the dollar at Friday's close, and the US 10-year Treasury yield sits near 4.22–4.24% (exchangerates.org.uk, Trading Economics).
Economic calendar — the real trigger is Wednesday
Monday is light on tier-1 data. The pivotal releases land Wednesday, Aug 12, when both US July CPI and India's July CPI are due; US PPI follows Thursday. US headline CPI is seen +0.1% m/m with core +0.2% (about 2.5% y/y) per a Bloomberg survey (IndexBox); India's CPI was 4.38% in June. A hotter US print would lift yields and the dollar and pressure Indian equities and the rupee; a cooler one supports the September-cut trade and risk appetite.
Headlines & stock movers
- Oil / geopolitics: US–Iran talks on reopening the Strait of Hormuz remain the dominant global driver.
- Q1 earnings deluge: Bosch, Sun Pharma Advanced Research, Info Edge, Gland Pharma, KEC International, Hindustan Copper, Wockhardt and Zee Entertainment are among 40+ results due today (Business Standard).
- IPOs: Dhoot Transmission (₹3,067 cr) and Molbio Diagnostics (₹940 cr) open today; LEAP India and Technocraft Ventures enter day two.
What it means for the India open
Expect a muted-to-flat start. Strong global cues plus a heavy earnings and IPO slate favour stock-specific action over a broad index move. Crude above $84 is the key overhang for oil-sensitive names such as OMCs, paints and aviation, while all eyes turn to Wednesday's twin CPI prints for the next directional cue.
As of 8:46 AM IST, Aug 10, 2026. Sources: Business Standard, CNBC, Trading Economics, IndexBox, exchangerates.org.uk. Automated pre-market brief for discussion and education only — not investment advice. Verify before acting.
This article is for educational and informational purposes only. It is not financial advice, investment recommendation, or a solicitation to buy or sell securities. Investing involves significant risks. I am not a SEBI-registered investment advisor. Readers should consult their own financial advisor and conduct their own research before making any investment decisions.
Comments
Join the conversation
Sign in to join the conversation.
Follow replies, add your view, and take part in the discussion.
Sign in to commentLoading comments...