

Post-Market Wrap — Jul 17, 2026 | How India & the world closed
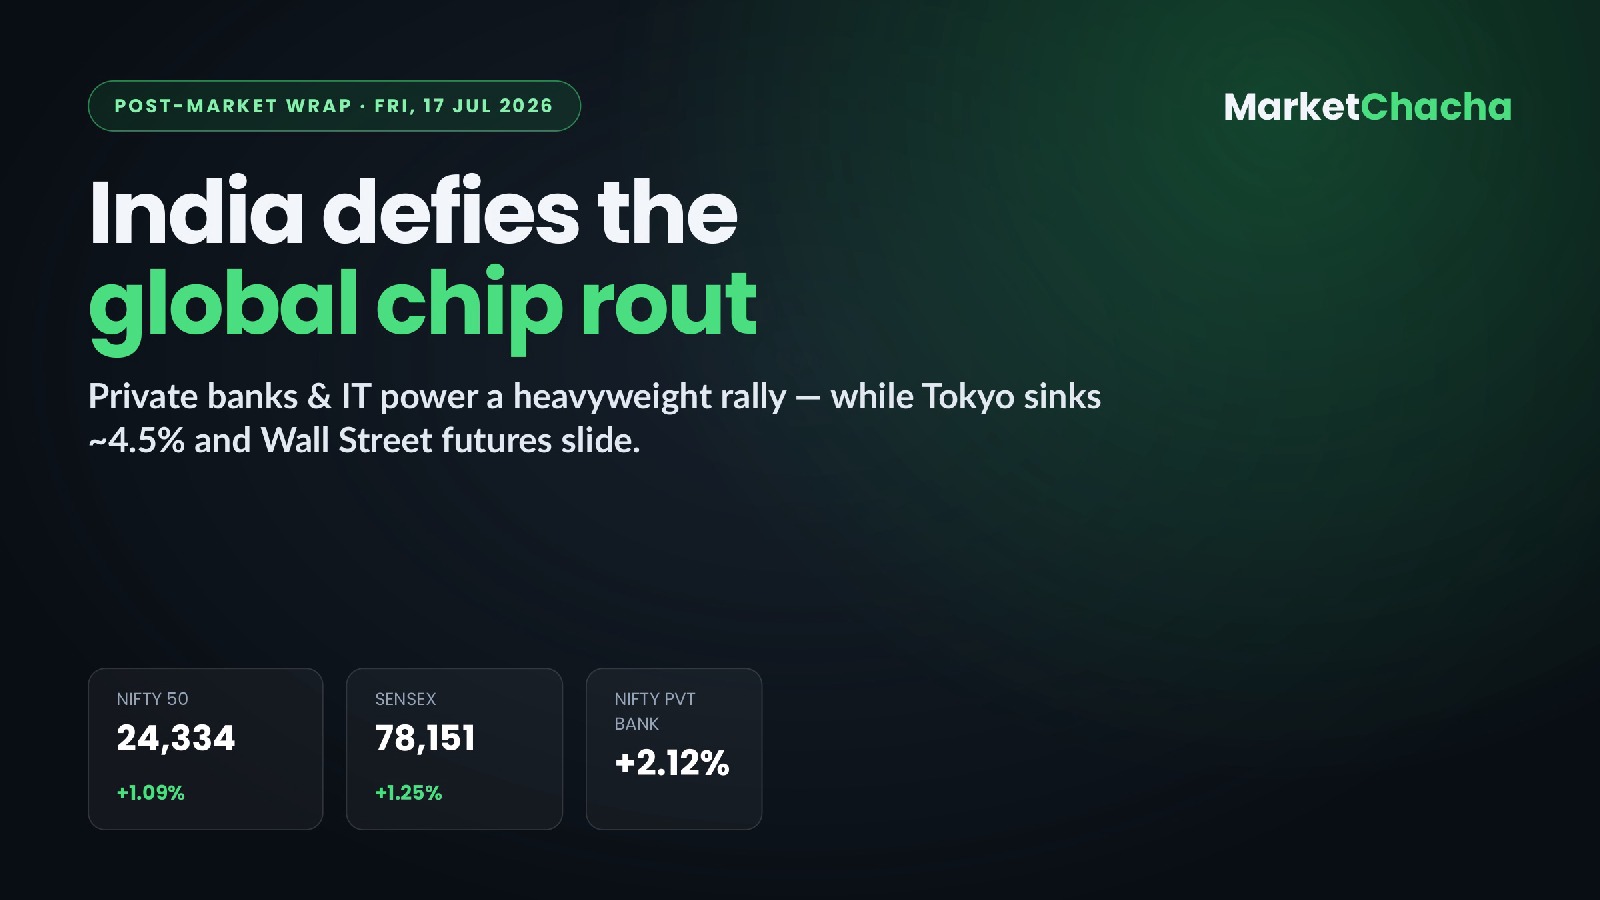
Indian equities decoupled hard from a global chip rout on Friday: the Nifty 50 closed up 261.55 points (+1.09%) at 24,334.30 and the Sensex added 964.58 points (+1.25%) to 78,151.45, powered by heavyweight buying in private banks, IT and Reliance — even as Tokyo cratered ~4.5% and Wall Street futures slid on AI-valuation jitters.
How India closed
- Nifty 50: 24,334.30, +261.55 pts (+1.09%)
- Sensex: 78,151.45, +964.58 pts (+1.25%)
- Nifty Private Bank: +2.12% (top sectoral gainer)
- Broader market lagged: Nifty Midcap 100 −0.41%, Smallcap 100 −0.21% — a narrow, large-cap-led rally with weak breadth.
Why: Index heavyweights did the lifting. Buying centred on private banks ahead of a heavy earnings weekend (HDFC Bank, ICICI Bank, Axis Bank), while Reliance rose ahead of its Q1 results. Crucially, India's IT pack rallied even as global chip stocks were dumped — a reminder that Indian IT is services, not semiconductors.
Sectors & stock stories
- Led: Nifty Private Bank +2.12%, Nifty IT +1.75%, Nifty Realty +1.34%, Nifty Auto +1.24%.
- Movers: Jio Financial jumped ~6% and Tech Mahindra ~2% on earnings; Infosys ran ~3% intraday. On the downside, CEAT was the top loser (−8%), Wipro shed ~2%, and ICICI Lombard slid ~10% post-Q1.
FII/DII flows
Provisional cash-market FII/DII figures for today's session were still being tallied at post time. The most recent confirmed read (Jul 15) showed FIIs net sellers of ~₹740 cr and DIIs net buyers of ~₹2,928 cr — domestic institutions again cushioning foreign outflows. (Provisional; verify on NSE.)
Currency & commodities
- USD/INR: around 96.4.
- Brent crude: ~$85.3 (+1.1%), kept firm by fresh US–Iran strikes and a Strait of Hormuz threat.
- Gold: spot ~$3,989/oz (+0.3%); silver ~$55.6/oz (+0.3%).
Global markets now
- Asia (closed): Nikkei ~−4.5% (steepest since March), Hang Seng −1.64% near 24,600; Korea's Kospi shut for Constitution Day.
- Europe (open): STOXX 600 −0.7% with Frankfurt and Paris lower, FTSE roughly flat; Europe's tech sector −2.3% as ASML, ASMI and Soitec fell 4–6%.
- US futures: Dow −0.6%, S&P 500 −0.9%, Nasdaq-100 −1.9%. Thursday's cash close: S&P −0.51% (7,533.77), Nasdaq −1.47% (25,881.95), Dow −0.20% (52,552.97).
The trigger: a widening semiconductor unwind — TSMC's raised capex, an ASML price-hike report and leveraged AI-trade unwinding — hammered chipmakers worldwide (SK Hynix −13%, Arm/AMD/Micron −5%+ Thursday).
Economic data
- India: RBI's weekly forex reserves are due today; the prior print rose $7.26 bn to $674.19 bn (week to Jul 3).
- US tonight: housing starts (est 1.31 mn vs 1.177 mn), building permits, industrial production (est +0.2%), import prices (est −0.7% m/m) and the preliminary July University of Michigan consumer sentiment (consensus ~51 vs 49.5 prior).
Sentiment & what to watch
Risk-off globally on AI/chip de-rating and Middle-East oil risk — but firmly risk-on in India, a rare and notable divergence. Watch whether India can keep decoupling from the chip rout into Monday; how the market reads the Reliance, HDFC Bank and ICICI Bank Q1 numbers; tonight's US Michigan sentiment and housing starts; and any fresh Hormuz/Brent headlines. If the global tech unwind deepens, even resilient India may feel the pull.
As of ~4:00 PM IST, Fri 17 Jul 2026. Sources: Business Standard, Reuters/Investing.com, CNBC, FXStreet, Trading Economics. Automated market wrap for discussion and education only — not investment advice. Verify before acting.
This article is for educational and informational purposes only. It is not financial advice, investment recommendation, or a solicitation to buy or sell securities. Investing involves significant risks. I am not a SEBI-registered investment advisor. Readers should consult their own financial advisor and conduct their own research before making any investment decisions.
Comments
Join the conversation
Sign in to join the conversation.
Follow replies, add your view, and take part in the discussion.
Sign in to commentLoading comments...