

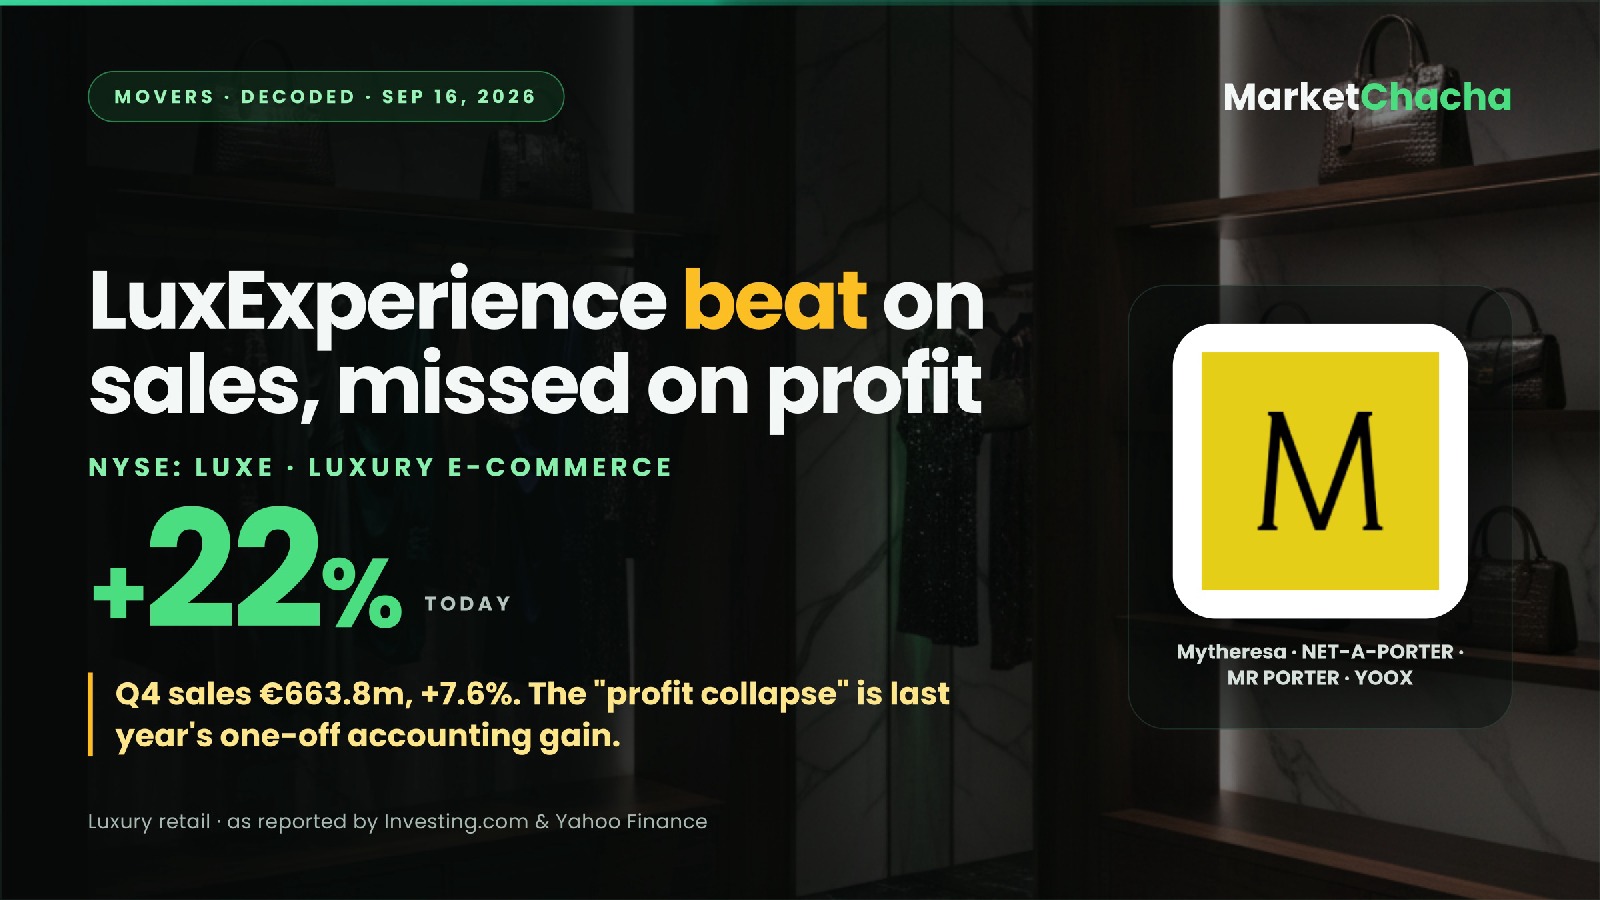
Why did LuxExperience (LUXE) jump ~22%? Its 96% ‘profit collapse’ was last year’s accounting ghost
What happened
LuxExperience (NYSE: LUXE) — owner of Mytheresa, NET-A-PORTER, MR PORTER and YOOX — reported Q4 and full-year FY26 before the US open. The stock ran from a $7.15 prior close to a $9.16 high, and sat near $8.77, up ~22.7%, late in Wednesday's session on about 2.07m shares (Yahoo Finance, 15:41 ET).
Q4 net sales were €663.8m, up 7.6% in constant currency, against the roughly €643.9m the street modelled. Adjusted EPS was −€0.18 versus −€0.07 expected (Investing.com). Sales beat, profit missed, stock up a fifth. That gap is the story.
Why it moved: the profit collapse is an accounting ghost
The scary line is a net loss of €26.3m against a €603.7m profit a year ago (Motley Fool). That looks like the business fell apart. It didn't.
Last year's quarter contained a bargain purchase gain — what accountants book when you acquire a business for less than the fair value of what you receive. The difference lands in the income statement as instant paper profit, and no cash moves. In October 2024 Richemont agreed to hand YOOX NET-A-PORTER to Mytheresa carrying €555m of cash and no financial debt in exchange for 33% of the enlarged company. Mytheresa wrote no cheque; Richemont flagged a roughly €1.3bn write-down of YNAP's net assets on its own books. Take on a cash-rich business for equity and you book an enormous gain on day one.
So €603.7m was ink. What investors actually bought was the operating line:
- Q4 adjusted EBITDA €13.6m, a 2.1% margin — up 270 basis points, third straight positive quarter
- Q4 SG&A cost ratio 17.6%, down 400bps
- Full-year adjusted EBITDA margin 0.4%, up 260bps from negative
- FY27 guidance: mid- to high-single-digit sales growth, 2–3% adjusted EBITDA margin
The business — which slice is working
- Mytheresa (full-price): €269.2m in Q4, +10.2% cc, EBITDA margin 6.3%. Average order value €875, up 13.1%. US sales +39.3%. The top 4.8% of customers drive 48.4% of GMV.
- NET-A-PORTER & MR PORTER: €273.9m, +5.6% cc, full-year gross margin 47.5% (+170bps).
- YOOX (off-price): €110.5m, +6.6% cc — and guided to a negative mid-single-digit EBITDA margin in FY27, with break-even only targeted for FY28.
That last bullet is what the headline hides. Mytheresa is the engine, NAP/MRP is the repair job, YOOX still burns cash and management says so. One quarter doesn't turn this into a clean luxury play.
Valuation
There is no P/E — the company lost $191.6m over twelve months, so there are no earnings to divide into the price. What exists: market cap about $1.12bn, P/S 0.39, EV/Sales 0.33, P/B 0.72 against stated book value of $9.94 a share with the stock at $8.77 (stockanalysis.com).
Peer check: Revolve Group (RVLV) carries a $1.47bn market cap on $1.31bn of revenue — P/E 20.4, P/S 1.12, P/B 2.74, EV/EBITDA 13.66. LuxExperience does $2.86bn of revenue, about 2.2x Revolve's, at a smaller market cap. Revolve converts sales into profit; LuxExperience so far does not. On its own history there's no usable five-year multiple range — it has traded under this name and structure only since 2025, and Mytheresa-era figures describe a company a third of today's size. The available reference points are 0.39x sales today and a 52-week range of $6.54–$11.38.
Who it touches
- Richemont (CFR) owns 33% of this company and took the €1.3bn write-down to offload YNAP. A YNAP that reaches break-even makes that disposal read very differently.
- Revolve and The RealReal — the listed US read-across on online fashion demand. Mytheresa's +39.3% US quarter is a live datapoint on the American luxury shopper.
- Brands wholesaling through these sites: 10.2% growth at full-price Mytheresa versus 6.6% at off-price YOOX says the top of the market is holding better than the discount end.
The one thing that flips it
Cash. The year ended with €442.7m and no bank debt, which sounds comfortable — but the full year produced a €108m operating cash outflow, and Q4's operating inflow was just €9m. A 2–3% EBITDA margin on roughly €2.5bn of sales is €50–75m of EBITDA. That's thin cover for a turnaround that must fund YOOX's losses through FY28, and the board authorised a $50m buyback on 3 September that draws on the same pot. If FY27 margin lands at the bottom of guidance, trading below book stops acting like a floor.
More of today's unusual moves: MarketChacha movers.
As of 15:41 ET, 16 Sep 2026. Sources: Investing.com, Investing.com (Q4 slides), Motley Fool via Yahoo Finance, stockanalysis.com, Richemont, SEC EDGAR (6-K and 20-F, filed 16 Sep 2026). For discussion and education only — not investment advice. Verify before acting.
This article is for educational and informational purposes only. It is not financial advice, investment recommendation, or a solicitation to buy or sell securities. Investing involves significant risks. I am not a SEBI-registered investment advisor. Readers should consult their own financial advisor and conduct their own research before making any investment decisions.
Comments
Join the conversation
Sign in to join the conversation.
Follow replies, add your view, and take part in the discussion.
Sign in to commentLoading comments...