

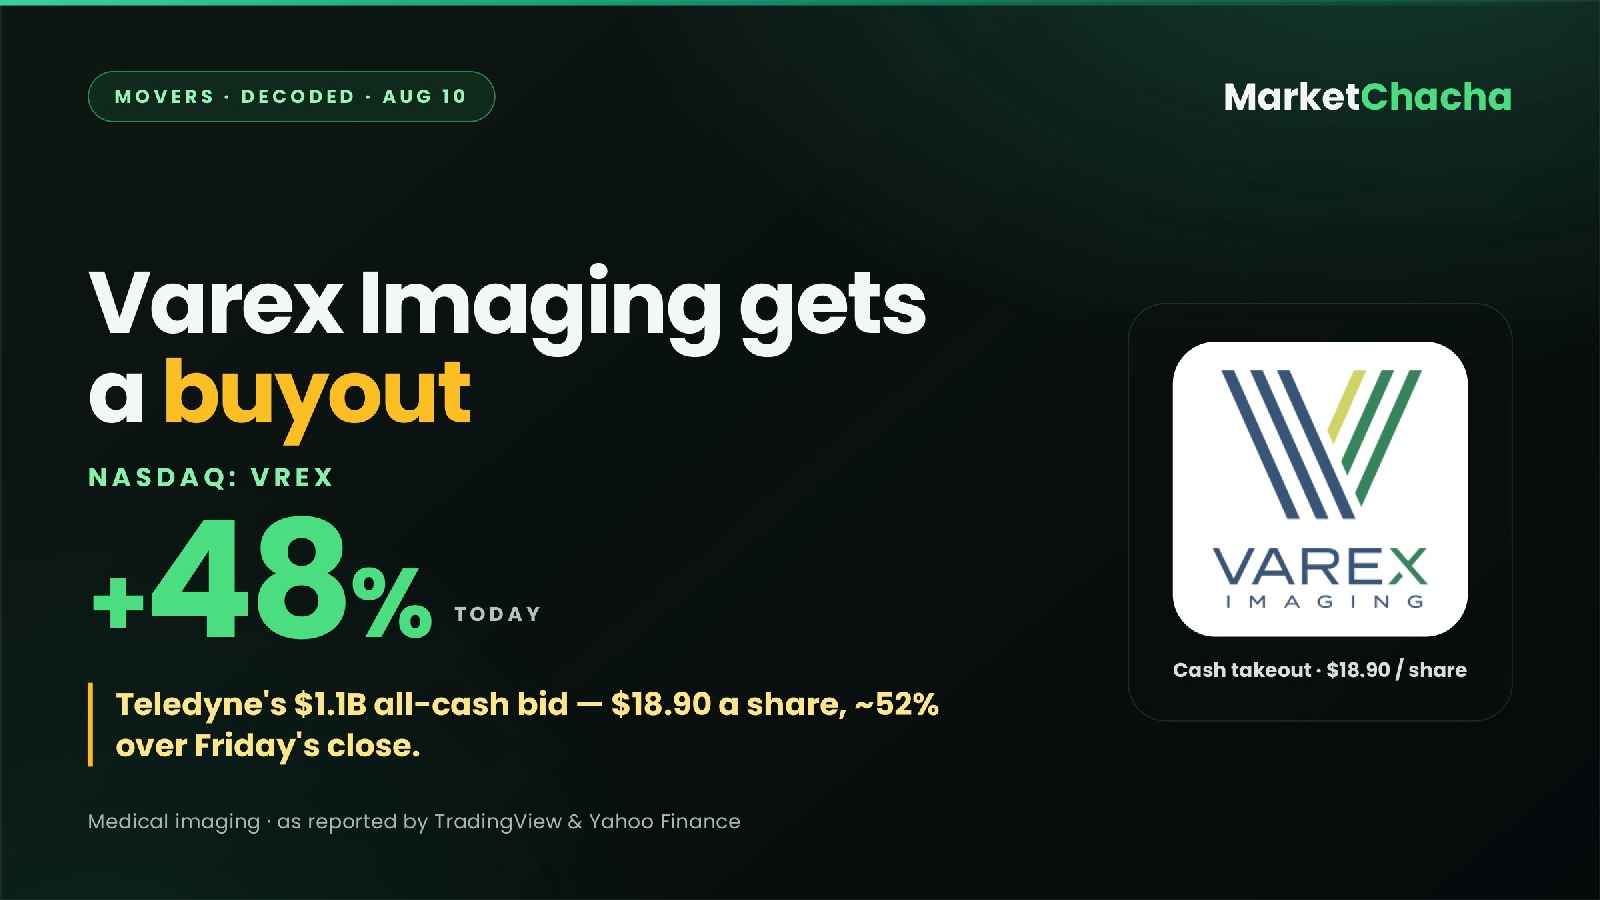
Why did Varex Imaging (VREX) jump ~48% today? Teledyne is buying it for $18.90 a share cash
What happened
Shares of Varex Imaging (Nasdaq: VREX) jumped about 48% today after Teledyne Technologies (NYSE: TDY) agreed to buy the whole company for $18.90 a share in cash — a deal worth roughly $1.1 billion including Varex's debt and stock awards. Both boards have signed off. The stock closed Friday at $12.41, so the offer is a premium of about 52% to that price (and roughly 88% above where Varex traded near $10 back in late May).
Why it moved
This is the cleanest kind of catalyst: a cash buyout at a fixed price. When an acquirer names a number, the target's stock snaps most of the way toward it almost instantly. Notice it jumped ~48% to around $18.4 — a shade under the $18.90 offer, not all the way to it. That small gap is the merger-arbitrage spread: the deal isn't expected to close until early 2027 and still needs antitrust clearances (a US HSR filing plus likely EU and Asia reviews) and a Varex shareholder vote. The discount is the market pricing in the time and the small chance it breaks.
Is it expensive?
Before the bid, Varex was actually cheap. At Friday's $12.41 it carried a P/E of about 13 (as reported by TradingKey/Yahoo) on a market cap near $777 million — below larger peer GE HealthCare, which trades around a 14–15 P/E. That low multiple on a supplier with a near-monopoly in one niche is exactly why an acquirer pounced. Teledyne's $18.90 lifts the valuation to roughly 21x last year's non-GAAP EPS of $0.90, or about 1.3x sales and ~9x EBITDA — full, but the going rate for a hard-to-replace component maker, not a wild overpay.
The business
Varex, spun out of Varian Medical in 2017, makes the guts of X-ray machines — not the scanners themselves. It runs two segments: Medical (FY25 revenue $593m) and Industrial ($252m), for total FY25 sales of about $845m. Its rare edge: it supplies both the X-ray tube (the source) and the detector (the capture) — and it's one of the only independent, production-ready makers of photon-counting CT detectors, the next-gen tech every big scanner brand is racing to adopt. So this isn't a one-product story; it's a supply-chain chokepoint.
Who it touches
- Teledyne (TDY) — the buyer; Varex folds into its Digital Imaging arm and instantly makes it a must-use supplier to the imaging giants.
- The five OEMs — GE HealthCare, Siemens Healthineers, Philips, Canon Medical and Fujifilm control ~90% of imaging systems and now buy a critical part from a defense-adjacent conglomerate.
- Rival component makers — Canon, Thales, iRay and Vieworks; consolidation reshuffles who OEMs can turn to.
- Other niche suppliers — a fat takeout premium for an unglamorous parts maker puts a spotlight on similar small-caps as targets.
What to watch
The one thing that flips this: the deal breaking. If antitrust regulators balk or Varex holders reject it, the stock loses its buyout floor and slides back toward its pre-bid ~$12. Until then, VREX basically trades as a bet on the deal closing, not on Varex's business. Teledyne has done this before — it swallowed FLIR for ~$8.2bn in 2021 and cleared antitrust in seven countries — which is partly why the market is pricing a high chance of completion.
As of ~12:40 PM ET, Aug 10, 2026. Sources: Teledyne/Varex release (via Yahoo Finance), TradingView News, ts2.tech. For discussion and education only — not investment advice. Verify before acting.
This article is for educational and informational purposes only. It is not financial advice, investment recommendation, or a solicitation to buy or sell securities. Investing involves significant risks. I am not a SEBI-registered investment advisor. Readers should consult their own financial advisor and conduct their own research before making any investment decisions.
Comments
Join the conversation
Sign in to join the conversation.
Follow replies, add your view, and take part in the discussion.
Sign in to commentLoading comments...