

Pre-Market Global Brief — Sep 02, 2026 | Nifty, Nasdaq, Nikkei, DAX & more
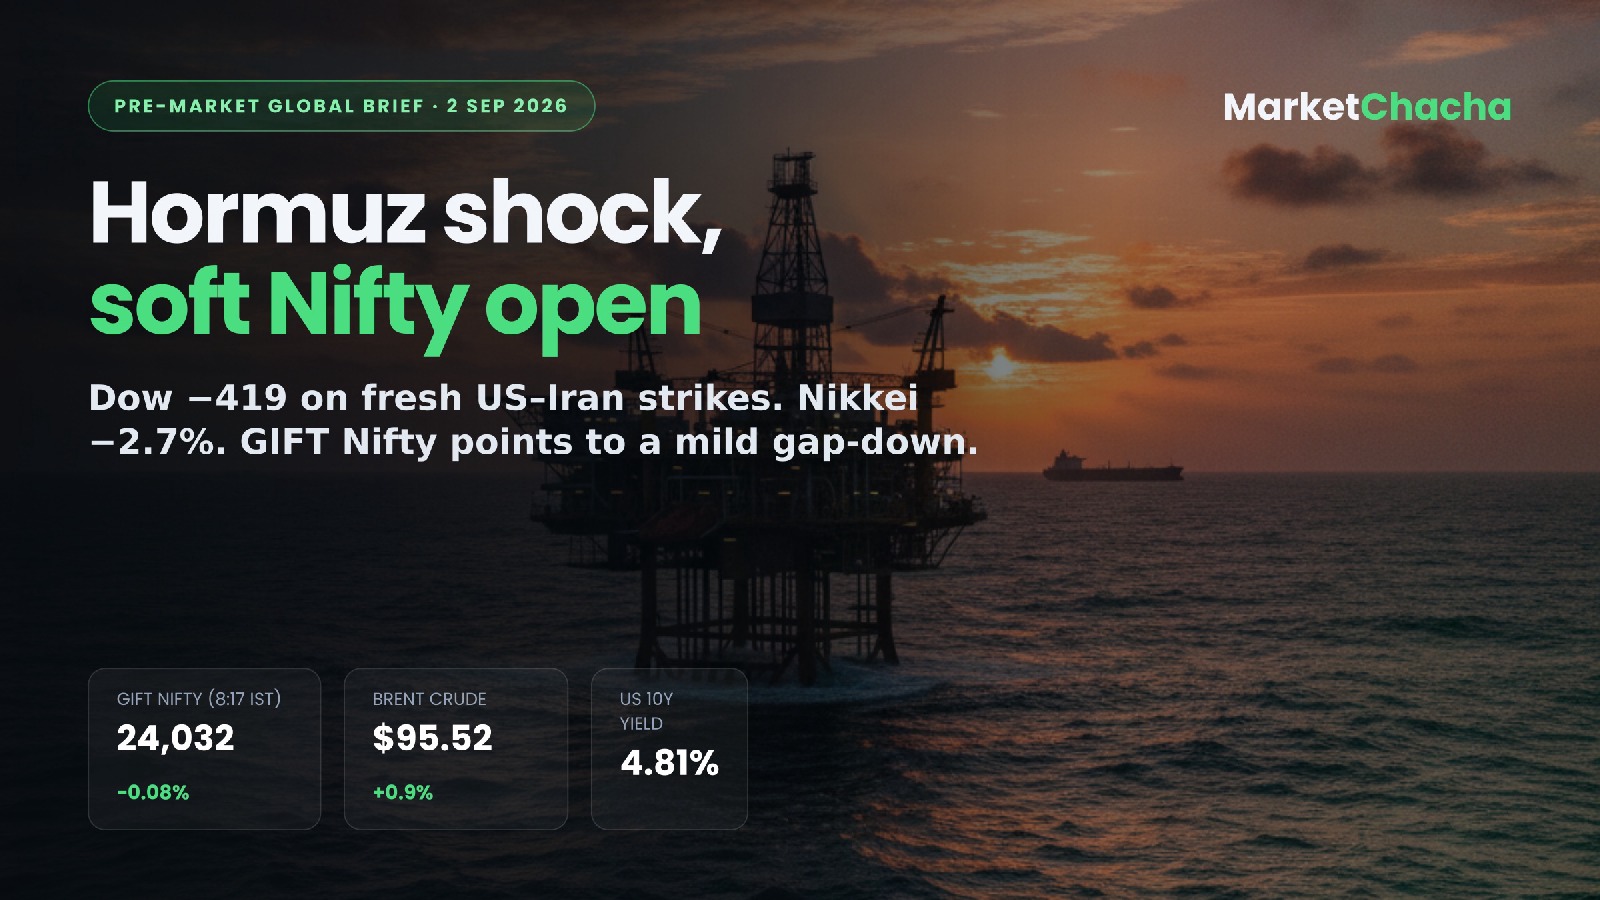
Fresh US–Iran strikes around the Strait of Hormuz have pushed Brent toward $96 and the US 10-year yield to a multi-month high, leaving Asia sharply lower — crude and bond yields, not earnings, are the single biggest swing factor for India's open today.
US: prior close (Tue, Sep 1)
- Dow 52,766.88, down 419 pts (−0.8%)
- S&P 500 7,631.47 (−0.7%)
- Nasdaq Composite 26,099.77, down 271 pts (−1.0%)
Why: US airstrikes on Iranian missile launchers on Larak Island lifted oil and Treasury yields, and revived fears the Fed could hike this month. Selling was concentrated in megacap tech, which is why the Nasdaq fell roughly triple the S&P's loss. (Alain Guillot recap; 24/7 Wall St.)
Asia now
- Nikkei 225 64,410, −2.73% — a four-week low. Extra local pain: Japan's 10-year JGB yield touched 3% for the first time since 1996 on BOJ hike bets. Tokyo Electron and SoftBank both −4.6%.
- Hang Seng 25,334, −0.91% (Sep 1 close); Tencent −2.1%. China's official manufacturing PMI did improve to 51.5.
- Kospi closed 6,835.80, +0.23% on Sep 1 on strong August chip exports; Business Standard reports it slipping again today alongside the Nikkei.
- Shanghai Composite: n/a — no verified live level at the time of writing.
Europe: prior close
- DAX 25,997, −0.99% — lowest since late July
- FTSE 100 10,751, −0.68%
- STOXX 600 651.1, −0.6%
Eurozone August inflation hit 3.3%, the highest since September 2023, and traders now talk of an ECB "insurance hike" in September.
India lead
GIFT Nifty was at 24,032.50 (−18.50, −0.08%) at 8:17 AM IST, implying a mild gap-down of roughly 17 points. Nifty 50 closed at 24,055.80 (−0.10%) and the Sensex at 76,944.28 (−0.02%) on Tuesday.
Commodities, currency, rates
- Brent $95.52 (+0.92%), WTI $91.02 (+0.89%) at 0008 GMT — both jumped over $4 on Tuesday. Hormuz, which once carried about a fifth of world oil consumption, is effectively shut to commercial traffic.
- Gold $4,337.48/oz, −2.33% — falling despite the war headlines, because high real yields hurt a non-yielding asset.
- USD/INR 94.89; Dollar index 99.416; US 10-year 4.81%.
Sentiment: risk-off
It is a classic oil-shock risk-off: energy up, yields up, equities and gold down. Markets are pricing roughly a 70% chance of a Fed rate hike at the Sep 16 FOMC, up from about 40% a week ago.
Data due today (Wed, Sep 2)
- India: nothing major scheduled. Tuesday already delivered Manufacturing PMI at 52.9 (July 53.5 — weakest improvement in five years, with factory jobs falling for the first time in 2.5 years) and August GST collections up 14.8% to nearly ₹2 lakh crore.
- US: ADP private payrolls (prior 44k) — a hot print reinforces the hike trade and pressures Indian IT and FII flows.
- Global: RBNZ rate decision (2.50%), Bank of Canada decision (2.25%), Australia Q2 GDP.
- Ahead: India Services PMI and US ISM Services on Sep 3, US August jobs report Sep 4, US CPI Sep 11, FOMC Sep 16.
Stocks in news
- Annu Projects lists today
- Hero MotoCorp: August sales +2.65% YoY at 5.68 lakh units, though motorcycles slipped 1.5%
- NMDC: August production +20.8% YoY to 4.07 mt
- Gland Pharma: USFDA closed its sterile oncology inspection with zero Form 483 observations
- Wipro renewed its ABB digital workplace deal; Adani Green crossed 20,280 MW operational capacity
What it means for the India open
The setup is defensive but not panicky: GIFT Nifty is signalling only a small gap-down, so the damage so far is contained relative to a 2.7% fall in Tokyo. The real tell is crude — every dollar on Brent widens India's import bill and squeezes OMCs, paints, tyres and aviation while helping upstream names like ONGC and Oil India. Watch the rupee and the 10-year: if yields keep climbing into the ADP print, FII selling and the oil bill matter far more today than any domestic trigger.
As of 8:55 AM IST, 2 September 2026. Sources: Alain Guillot market recap, Business Standard, Trading Economics, Business Recorder, BazaarWatch, Vantage Markets, Business Today, LiteFinance economic calendar. All prices as reported by those sources, not live exchange data. Automated pre-market brief for discussion and education only — not investment advice. Verify before acting.
This article is for educational and informational purposes only. It is not financial advice, investment recommendation, or a solicitation to buy or sell securities. Investing involves significant risks. I am not a SEBI-registered investment advisor. Readers should consult their own financial advisor and conduct their own research before making any investment decisions.
Comments
Join the conversation
Sign in to join the conversation.
Follow replies, add your view, and take part in the discussion.
Sign in to commentLoading comments...