

Post-Market Wrap — Sep 09, 2026 | How India & the world closed
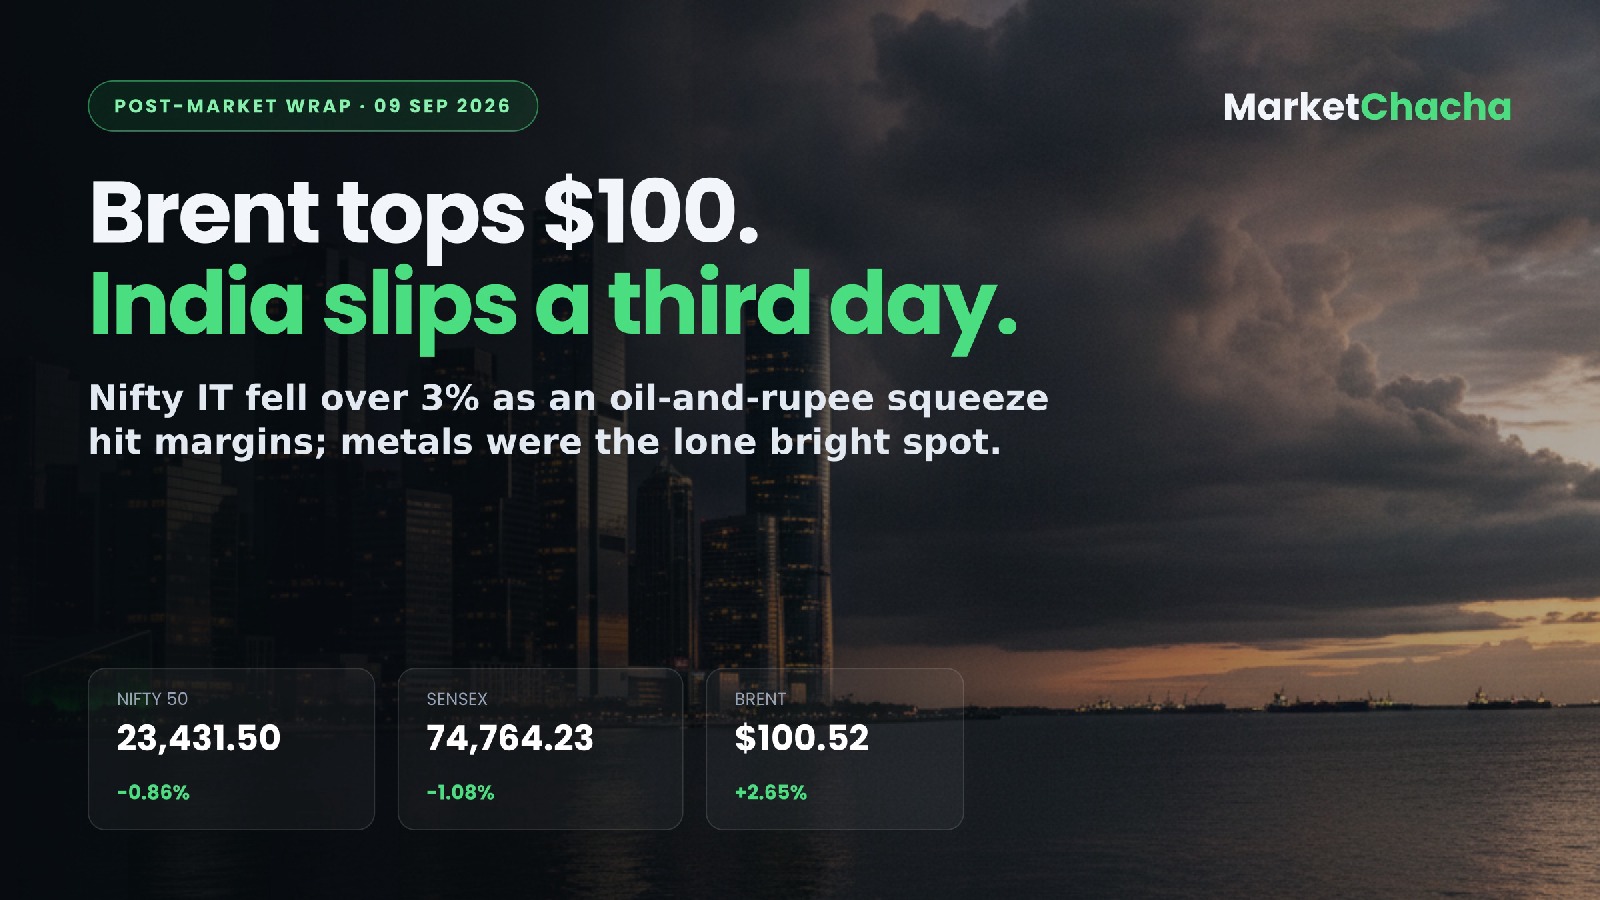
Indian equities fell for a third straight session as Brent crude pushed past $100 a barrel on escalating US-Iran tensions, reviving inflation and margin worries across import-sensitive sectors.
How India closed
- Nifty 50: 23,431.50, down 203.60 pts (-0.86%) — Business Standard
- Sensex: 74,764.23, down 813.35 pts (-1.08%), a third consecutive decline — Business Standard
- Nifty Midcap 100: -0.51% · Nifty Smallcap 100: -0.48% — broader market held up better than large caps — Business Standard
- Bank Nifty: n/a — no verified closing print available at the time of writing
Sectors: IT cracked, metals held
Nifty IT was the worst performer, settling over 3% lower, with Nifty Realty also lagging (Business Standard). The logic: a costlier oil bill pressures the rupee and the broader cost base, and IT is the classic proxy for global demand risk when a geopolitical shock lands. Nifty Metal outperformed, helped by firm global commodity prices.
Notable losers: Infosys, HCL Technologies, Tech Mahindra, Wipro and HDFC Life. On the other side: Sun Pharma, Adani Ports, Adani Enterprises, Tata Steel, Coal India, Trent and BEL featured among gainers through the session (India TV, Business Remedies). Primary-market activity stayed heavy — 10 IPOs were open for bids today with about Rs 6,950 crore at stake (Business Today).
Flows, currency, commodities
- FII/DII: today's provisional figures were not published at the time of writing. For the previous session (Sep 8), FIIs were net sellers of Rs 123 crore and DIIs net buyers of Rs 1,349.64 crore — India TV / PTI
- USD/INR: the rupee slipped about 21 paise to 94.95 from 94.74, on oil and importer hedging demand — PTI via Telangana Today
- Crude: Brent ~$100.52 (+2.65%), WTI ~$95.09 (+2.21%) — Trading Economics
- Gold: ~$4,392/oz (+0.84%) on a softer dollar — Trading Economics
Global right now
Europe is lower: the STOXX 50 was down about 0.7% and the STOXX 600 about 0.5%, with energy majors bid and Inditex off over 3% (Trading Economics). US futures are broadly flat after Tuesday's selloff — Dow futures -0.06%, S&P 500 futures +0.04%, Nasdaq futures +0.14%; the S&P 500 closed Tuesday at 7,679.51 (-0.58%) and the Dow shed over 600 points (Yahoo Finance, Trading Economics). Asia was mildly negative: the Nikkei 225 fell about 0.3% and the Hang Seng was down roughly 0.2% (Trading Economics).
Data on the tape
No major Indian macro print landed today. The domestic calendar picks up with forex reserves on Sep 11, WPI and CPI inflation on Sep 14, and trade balance plus the unemployment rate on Sep 15 (India Macro Indicators). Globally, the ECB decision lands Thursday, where a 25 bps hike is expected (Trading Economics), alongside US August PPI (Thu, 8:30 am ET) and US August CPI (Fri, 8:30 am ET) (FedRateCalc). The FOMC decision is Sep 16, with markets pricing roughly a 60% chance of a 25 bps hike this month (Trading Economics).
Sentiment
Risk-off, but orderly rather than panicky — the drawdown was concentrated in IT and rate-sensitives while metals, energy-linked names and the broader market cushioned the fall. Breadth was close to even through much of the day. The single variable driving everything is the oil price, and through it the inflation path.
What to watch tonight and tomorrow
Brent's hold above $100 is the swing factor: sustained triple-digit crude feeds straight into India's import bill, the rupee and margin assumptions for the next earnings cycle. Watch whether RBI intervention continues to cap USD/INR near current levels, and whether FII selling deepens once provisional flows publish. Overnight, the ECB decision and US PPI set the tone for Thursday's open, with Friday's US CPI the bigger risk event into the Sep 16 FOMC. If crude cools, the IT and consumption trades are the first to get relief.
As of 4:00 PM IST, 9 September 2026. Figures as reported by: Business Standard, India TV, Telangana Today (PTI), Trading Economics, Yahoo Finance, Business Today, India Macro Indicators, FedRateCalc. Automated market wrap for discussion and education only — not investment advice. Verify before acting.
This article is for educational and informational purposes only. It is not financial advice, investment recommendation, or a solicitation to buy or sell securities. Investing involves significant risks. I am not a SEBI-registered investment advisor. Readers should consult their own financial advisor and conduct their own research before making any investment decisions.
Comments
Join the conversation
Sign in to join the conversation.
Follow replies, add your view, and take part in the discussion.
Sign in to commentLoading comments...