

Pre-Market Global Brief — Aug 31, 2026 | Nifty, Nasdaq, Nikkei, DAX & more
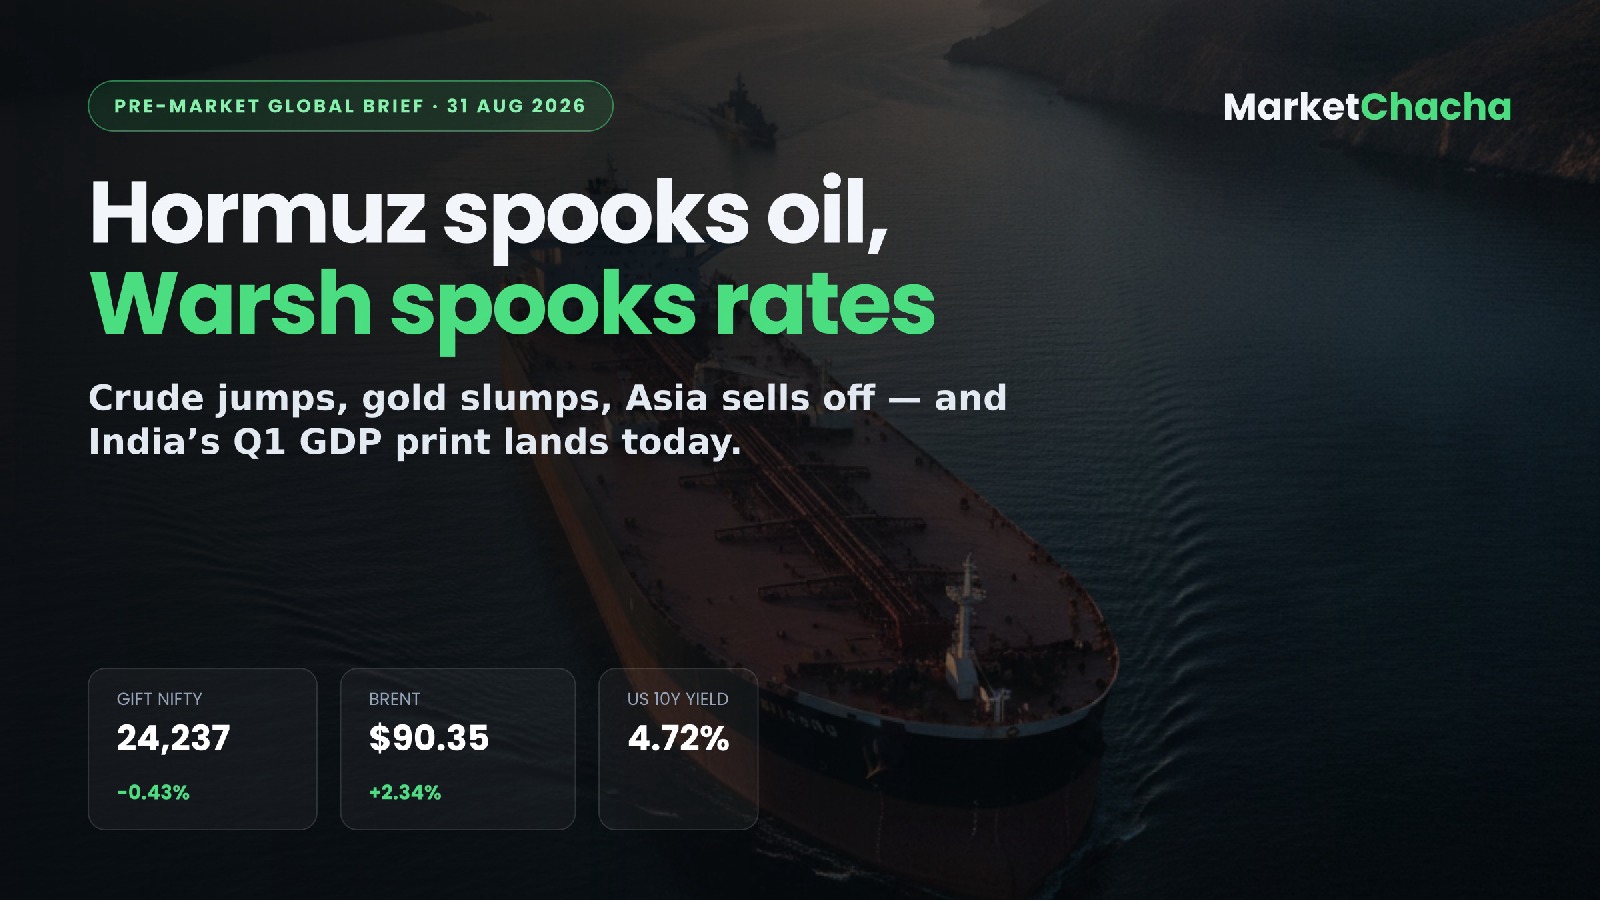
Risk-off morning: a fresh US-Iran flare-up at the Strait of Hormuz has crude back near $90 just as Fed Chair Kevin Warsh's hawkish Jackson Hole tone revives September rate-hike talk — a bad combination for an oil-importing India, and GIFT Nifty is pointing to a lower open.
India lead
- GIFT Nifty ~24,237-24,239, down ~104 points (-0.43%), signalling a weak start, per Business Standard and Business Today.
- Nifty 50 closed Friday at 24,176 (Sensex +331 pts, snapping a two-day fall) — Business Standard.
- Friday flows: FPIs net sold Rs 5,039.80 crore, DIIs bought Rs 5,183.93 crore; India VIX 10.68 (-3.5%) — Business Today.
Overnight: US and Europe
- Dow 53,559.99 (-0.02%), S&P 500 7,711.76 (-0.25%), Nasdaq 26,402.42 (-0.52%) on Friday — Warsh's inflation-first message did the damage (Business Today). US futures were down ~0.3% this morning.
- DAX 26,570 (+0.77%) — a record close, led by BMW (+4%) and autos. FTSE 100 10,824.26 (+0.29%). Note: London is shut today for the UK summer bank holiday, so European volumes will be thin.
Asia now
- Nikkei 225 65,550 (-1.29%), Hang Seng 25,349 (-0.92%), Shanghai Composite 3,935.14 (-0.43%) — Trading Economics. Kospi down ~2.4% (Business Standard), the region's worst, with Samsung Electronics -2.7% and SK hynix -3.5%.
- China's August NBS manufacturing PMI came in at 49.8 (forecast 49.7, prior 49.2); non-manufacturing steady at 49.0 — a second month in contraction (FXStreet). Better than feared, but not a growth signal.
Commodities, currency, rates
- Brent quoted $89.4-$90.4, up 1.4-2.3% in Asian hours (Business Today, Business Standard) after settling near $88.3 Friday; WTI ~$83.44 (Trading Economics). This is the single biggest India-specific risk today.
- Gold $4,454/oz, after a 3.18% Friday slide on hike odds (Trading Economics).
- USD/INR 95.49 (Aug 28), DXY 99.67, US 10-year 4.72% (Trading Economics).
Data due today
- India Q1 FY27 GDP — the day's main event. Consensus 7.2% vs 7.8% prior; house estimates span 6.9% (India Ratings) to 8.0% (SBI) on weak rains and softer services (Trading Economics, Business Standard). A sub-7% print would hit cyclicals and revive rate-cut hopes; 7.5%+ supports the domestic-growth trade.
- Germany flash CPI (est 3.0% vs 2.8%), US Chicago PMI (9:45 am ET), Dallas Fed manufacturing (est 0.7 vs 1.3), US August auto sales, Japan consumer confidence and housing starts.
- This week: Eurozone flash CPI and US ISM manufacturing plus JOLTS (Tue), ADP and durable goods (Wed), ISM services and jobless claims (Thu), and US non-farm payrolls Friday (est +12K vs -23K, unemployment 4.2%). A hot payroll would harden the hike case and pressure the rupee.
Stocks and events in focus
- Augmont Enterprises lists today — grey-market premium ~Rs 290 on a Rs 788 issue price, implying a ~36.8% premium (Business Standard).
- Purple Style Labs IPO opens; SME issues Ashutosh Fibre, Shanti Inorganics and Phychem Technologies also open.
- Oil marketers, paints, aviation and tyres are the obvious crude-sensitives; IT and exporters get some rupee cushion.
What it means for the India open
Expect a gap-down toward the 24,100s with 24,000 the level bulls must defend; Business Today flags a 24,000-24,400 range with 24,300-24,400 as the upside test. The market has two binary risks stacked in one session — Hormuz headlines through the day and the GDP print after the close — so positioning into the afternoon is likely to stay light. Crude above $90 is the thing to watch: it feeds straight into the import bill, the rupee and the inflation path.
As of 8:45 AM IST, 31 August 2026. Sources: Business Standard, Business Today, Trading Economics, FXStreet, TradingHours. All prices and index levels are as reported by these sources, not live exchange data. Automated pre-market brief for discussion and education only — not investment advice. Verify before acting.
This article is for educational and informational purposes only. It is not financial advice, investment recommendation, or a solicitation to buy or sell securities. Investing involves significant risks. I am not a SEBI-registered investment advisor. Readers should consult their own financial advisor and conduct their own research before making any investment decisions.
Comments
Join the conversation
Sign in to join the conversation.
Follow replies, add your view, and take part in the discussion.
Sign in to commentLoading comments...