

Post-Market Wrap — Sep 3, 2026 | How India & the world closed
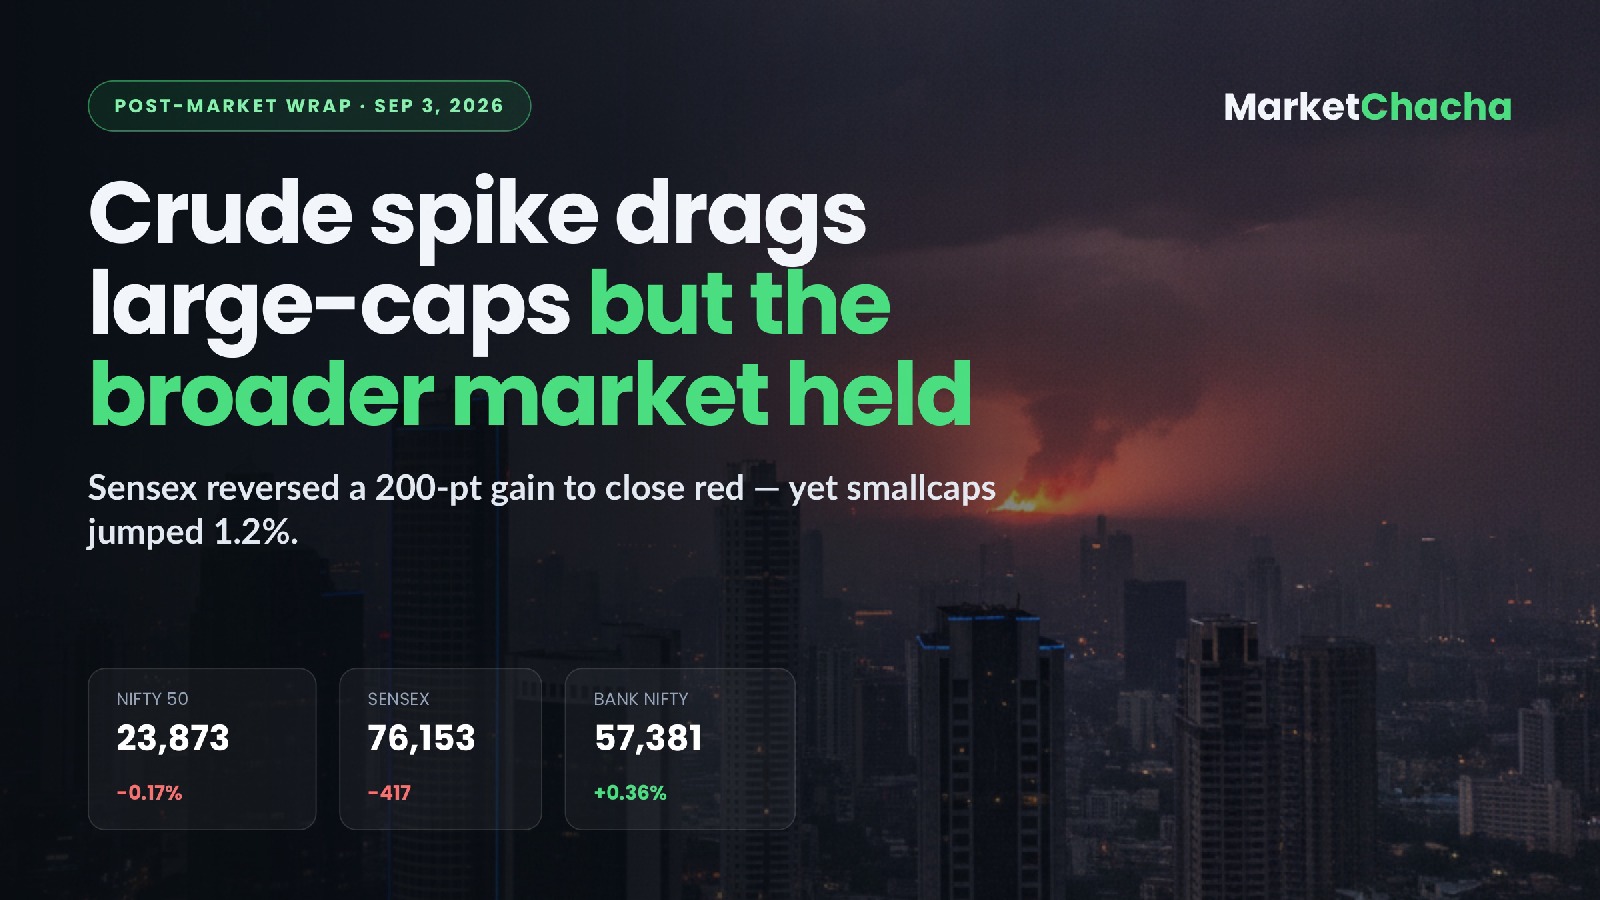
Indian large-caps reversed an early rally to close red on Thursday as a spike in crude oil and a jump in bond yields revived inflation and rate worries — but the broader market held firm, with the Nifty Smallcap 100 jumping over 1%.
How India closed (Sep 3)
- Nifty 50: 23,873.45, down ~41 pts (−0.17%) — Business Standard
- Sensex: 76,152.86, down 417.49 pts (−0.55%) — Business Standard
- Bank Nifty: 57,380.60, up ~0.36% — Liquide
- Nifty Midcap 100: +0.37% · Smallcap 100: +1.20% (ending a 3-day losing streak) — 5paisa
The benchmarks opened up 200+ points but faded as Brent pushed toward $96 on US–Iran / Strait of Hormuz tension and rising Treasury yields stoked "higher-for-longer" fears. Breadth stayed positive, so the pain was concentrated in heavyweights.
Sectors & stocks
Led: Realty, Financial Services, Energy and Metal. Lagged: IT, FMCG, Auto, Pharma and Consumer Durables. Private banks and realty counters outperformed. Among Nifty names, Adani Ports, Axis Bank and HDFC Bank were top gainers, while Bajaj Auto (−1.7%), Tech Mahindra and Trent were the biggest drags. (Sources: Business Standard, Liquide)
Flows, currency & commodities
- FII/DII (previous session, Sep 2, provisional): FIIs net bought ~₹6,688 cr; DIIs ~₹2,813 cr — 5paisa. Sep 3 provisional figures were not confirmed at press time.
- USD/INR: around 95.1–95.2, with the rupee under pressure from firmer crude — Vantage Markets.
- Brent crude: ~$96.2/bbl (+1.1%); Gold: futures near $4,526 (+2.5%) — Investing.com / Forbes.
Global snapshot
Asia (close): Nikkei −0.17% at 64,214; Hang Seng −0.39% at 25,213; Shanghai +0.02% at 3,942. Europe: DAX softer near 25,790, FTSE 100 marginally higher near 10,759. US (Thursday afternoon ET, as reported): equities traded higher, tech-led, with Nvidia and Meta among gainers. (Sources: Trading Economics, Sunday Guardian)
Data watch
Out today: India's HSBC/S&P Global Services PMI rose to 54.1 in August (from 53.3), still expanding but with new business near a four-year low — Reuters/Investing.com. The big global marker is the US August jobs report, due Friday Sep 4 at 8:30 am ET (evening IST) — a soft print would sharpen the Fed rate-path debate; watch weekly jobless claims too — BLS.
What to watch next
Crude and the Strait of Hormuz headlines remain the swing factor for Indian inflation and the rupee. If Brent stays elevated and yields keep climbing, large-cap heavyweights may stay heavy even as the broader market runs. Friday's US payrolls and the rupee at ~95 are the two things to track into next session.
As of ~4:00 PM IST, Sep 3, 2026 (India close). Sources: Business Standard, Liquide, 5paisa, Vantage Markets, Investing.com, Trading Economics, Reuters/Investing.com, BLS. Automated market wrap for discussion and education only — not investment advice. Verify before acting.
This article is for educational and informational purposes only. It is not financial advice, investment recommendation, or a solicitation to buy or sell securities. Investing involves significant risks. I am not a SEBI-registered investment advisor. Readers should consult their own financial advisor and conduct their own research before making any investment decisions.
Comments
Join the conversation
Sign in to join the conversation.
Follow replies, add your view, and take part in the discussion.
Sign in to commentLoading comments...