

Pre-Market Global Brief — Jul 27, 2026 | Nifty, Nasdaq, Nikkei, DAX & more
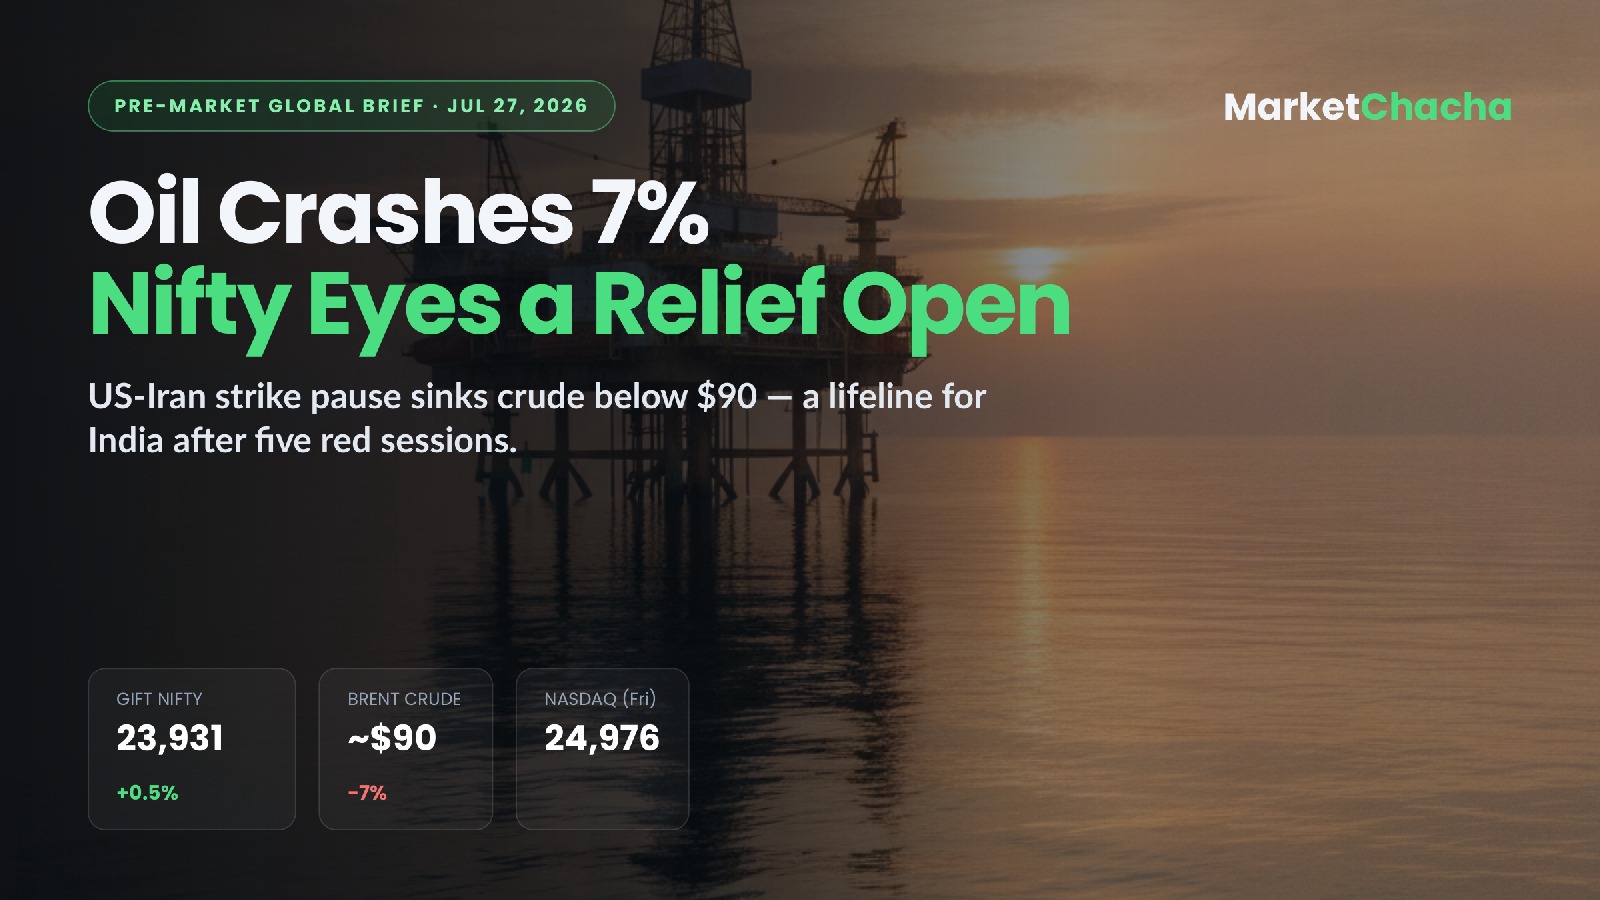
A risk-on relief mood is building into the open: the US and Iran paused strikes for a second straight day over the weekend and Tehran reciprocated, and the de-escalation sent crude tumbling — handing India's oil-sensitive market a chance to snap a five-session losing streak. GIFT Nifty is pointing to a green open even as Asia trades mixed.
US — prior close (Fri, Jul 24)
Wall Street ended a choppy week split. The Dow rose 0.46% to 51,947 and the S&P 500 edged up 0.05% to 7,412, but the Nasdaq slipped 0.64% to 24,976 as chip and memory names sold off (Intel fell ~6.5%, SanDisk ~11%). All three indices still booked weekly losses, the Nasdaq down ~2% on the week — per Yahoo Finance and TheStreet.
Asia — live now
Mixed after reversing early gains despite the oil drop. Japan's Nikkei 225 was ~0.15% lower and South Korea's Kospi ~1% down; China's CSI 300 opened near 4,784, per Business Standard and CNBC. Cheaper oil helps importers, but chip-linked weakness from Wall Street capped the upside.
Europe — prior close (Fri)
Strong finish on solid earnings and better PMIs: DAX +1.36% to 25,099, FTSE 100 +0.91% to 10,736, Euro Stoxx 50 +1.1% to 6,281 (Trading Economics).
India lead
GIFT Nifty ~23,931, up ~124 points (+0.5%), implying a positive Nifty open (Business Standard). It follows Friday's fifth straight fall — Sensex −331 pts to 76,060 and Nifty −102 pts to 23,767, dragged by autos and metals, though Nifty Bank held up.
Commodities, currency & yields
Brent slid below $90 (about −7%) and WTI eased in tandem as supply-disruption fears faded (Business Standard, Bloomberg). Gold ~$4,066/oz (Investing.com). The rupee closed near 96.57/$, close to record lows on Friday — a sustained oil drop is the single biggest relief lever for it. US 10Y yield ~4.67%; dollar index near 101.4.
Data due — today & this week
Today (US): Durable Goods Orders (Jun) forecast +1.6% vs −4.5% prior; core +0.9%; and the Dallas Fed manufacturing index (−12.0 est.). The week's marquee event is the FOMC decision on Wed, Jul 29 (11:30 PM IST) — markets lean toward a hold at 3.50–3.75%, with a slim hike risk — followed by US Q2 GDP and the Fed's preferred June PCE inflation print later in the week. At home it's a heavy Q1 FY27 earnings stretch (IDFC First Bank, DCB Bank today) with NSE monthly F&O expiry on Tue, Jul 28. A soft PCE would ease rate-cut worries and support emerging markets like India; a hot print could revive the dollar and pressure the rupee.
Headlines moving the tape
US–Iran strike pause and reciprocal Iranian restraint are the dominant driver; the Strait of Hormuz risk premium is unwinding. Q1 results season is the main stock-specific catalyst at home, while global tech sentiment stays shaky after the overnight chip sell-off.
What it means for the India open
The oil crash and calmer Middle East set up a positive, relief-led open that could break the five-day losing run, with OMCs, aviation and rate-sensitives the likely beneficiaries and the rupee getting breathing room. But gains may be kept in check ahead of Wednesday's Fed decision and by weak global tech cues, so expect a firm start that turns stock-specific as Q1 earnings roll in.
As of 08:45 IST, Mon 27 Jul 2026. Sources: Business Standard, Yahoo Finance, TheStreet, CNBC, Trading Economics, Investing.com. Automated pre-market brief for discussion and education only — not investment advice. Verify before acting.
This article is for educational and informational purposes only. It is not financial advice, investment recommendation, or a solicitation to buy or sell securities. Investing involves significant risks. I am not a SEBI-registered investment advisor. Readers should consult their own financial advisor and conduct their own research before making any investment decisions.
Comments
Join the conversation
Sign in to join the conversation.
Follow replies, add your view, and take part in the discussion.
Sign in to commentLoading comments...