

Pre-Market Global Brief — Sep 09, 2026 | Nifty, Nasdaq, Nikkei, DAX & more
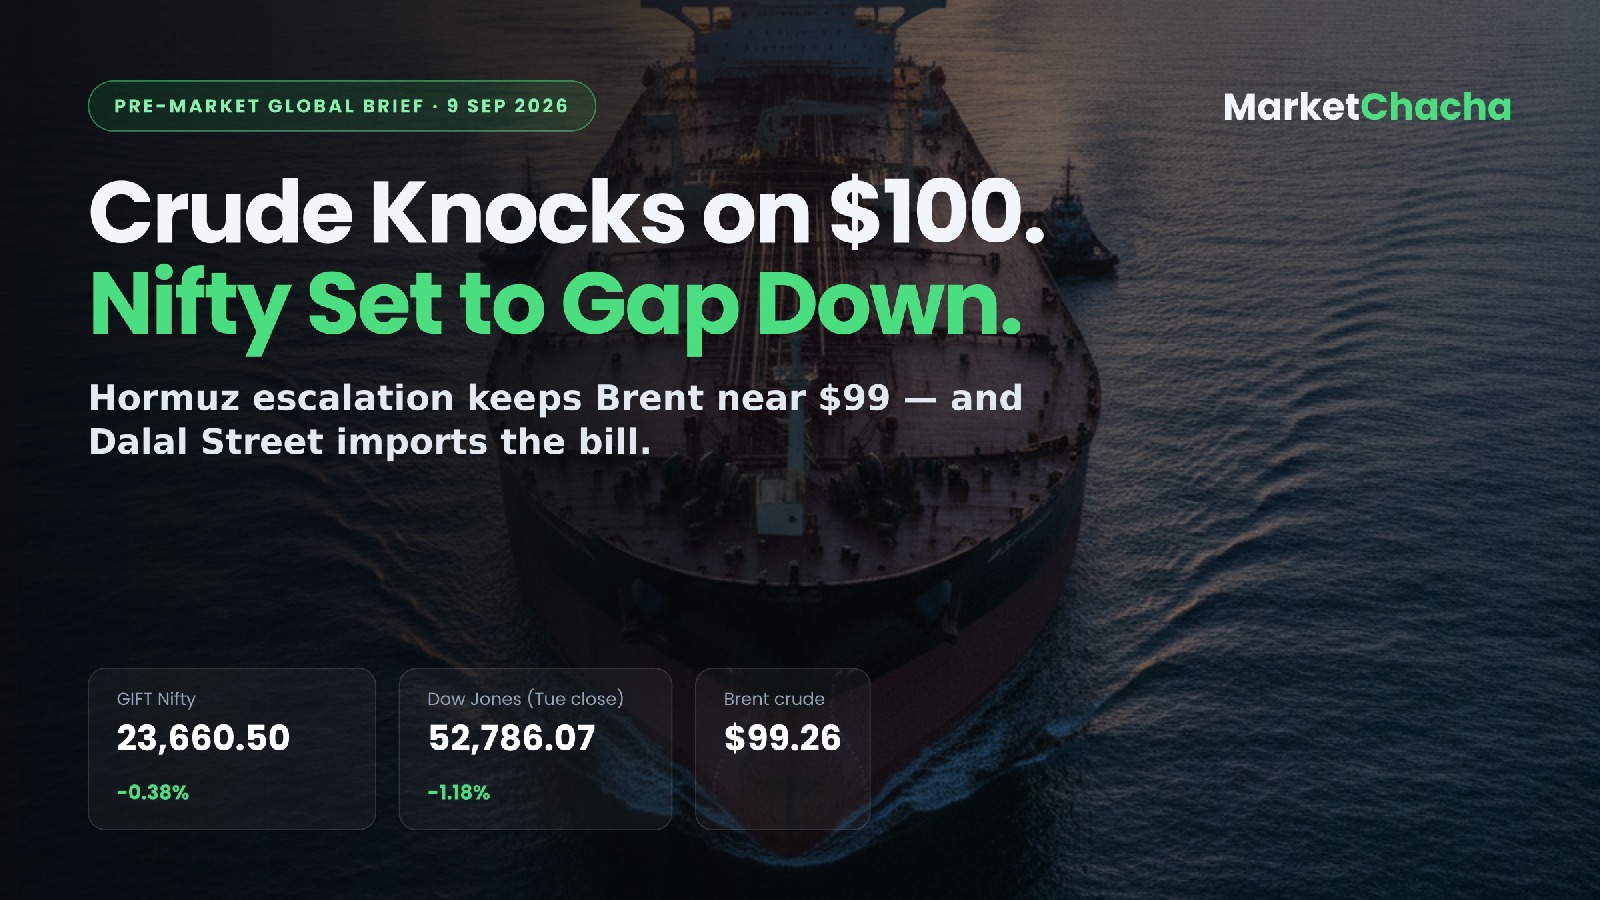
Overnight tone is defensively risk-off: Brent crude camped just under $100 a barrel after renewed US–Iran hostilities around the Strait of Hormuz is the single biggest driver for India's open, and GIFT Nifty is pointing to a gap-down start.
US prior close — oil re-ignited the rate-hike trade
- Dow Jones 52,786.07, −1.18%
- S&P 500 7,673.52, −0.58%
- Nasdaq Composite 26,421.41, −0.32%
Levels as reported by Business Today. Why: climbing crude revived inflation worries before Friday's US CPI. Trading Economics reports futures are pricing roughly a 60% probability of a 25 bps Fed rate hike this month (funds rate currently 3.50–3.75%) — a hike, not a cut, is the live debate. The US 10-year yield is near 4.8% (Business Standard).
Asia now, Europe last night
- Kospi is the standout, up roughly 1.4–1.8% on SK Hynix and Samsung strength; Nikkei 225 about +0.4%; Hang Seng and Shanghai broadly flat — Asia is mixed, not panicked (Business Standard, Business Today).
- Europe Tuesday: Euro Stoxx 50 6,384 (−0.31%), DAX 25,890 (−0.45%), STOXX 600 −0.3%; Novartis fell almost 9% on trial disappointment (Trading Economics).
India lead
GIFT Nifty 23,660.50, down 89.10 points (−0.38%) — implying a gap-down open (Business Today). Nifty 50 closed at 23,635.10 (−0.61%) and Sensex at 75,577.58 (−0.73%) yesterday (Goodreturns). Watch support at 23,500–23,450 and resistance at 23,750–23,900. FIIs sold ₹123.19 crore, DIIs bought ₹1,349.64 crore.
Commodities, currency, yields
- Brent $99.26; WTI near $93 (Business Standard; TheStreet/Yahoo Finance)
- Gold $4,435.70, −0.91% on Tuesday; futures softer again this morning
- USD/INR ₹94.88; Dollar index 98.15 (Goodreturns; Business Today)
Data due — the calendar readers miss
- China August CPI +0.8% y/y (forecast 0.8%, prior 0.5%) and +0.4% m/m (forecast 0.3%); PPI +3.8% y/y (forecast 3.7%, prior 3.5%) — already out, with the statistics bureau crediting rising energy prices. A reflating China is mildly supportive for metals and commodity exporters.
- US today: no noteworthy scheduled release (Kiplinger).
- Thursday 10 Sep: US PPI (August), weekly jobless claims, existing home sales, wholesale trade; ECB rate decision and press conference (deposit rate 2.25%); German final HICP.
- Friday 11 Sep: US August CPI plus preliminary Michigan sentiment — the week's real swing factor.
- India: no major macro print scheduled today; August CPI is the next domestic marker (July came in at 4.45%).
What a beat/miss means for India: a hot US CPI on Friday hardens the hike case, lifts the dollar and the 10-year, and typically means more FII selling and rupee pressure — painful with the rupee already near ₹95. A soft print does the reverse and would give beaten-down rate-sensitives room to bounce.
Stocks in focus
- OMCs (IOC, HPCL, BPCL) squeezed as crude tests $100; upstream ONGC/Oil India are the natural hedge.
- Sun Pharma — Moody's and S&P assigned investment-grade ratings, stable outlook, for its proposed $11.75 billion Organon acquisition.
- Suzlon Energy — 200 MW wind order from Ayana Renewable Power.
- Biocon — Brazil partnerships with Bahiafarma and Bionovis for Pertuzumab.
- Tata Power — Solaroof crossed 5 lakh rooftop installations; HCL Tech opened a ₹185 crore semiconductor lab in Bengaluru; TCS won a ₹122.6 crore Odisha automation contract; IHCL signed a 111-key Ginger property in Nava Raipur.
What it means for the India open today
Expect a soft start around 23,550–23,600 with energy costs, not earnings, setting the mood — every dollar on Brent widens India's import bill and squeezes the rupee, which is why oil marketers, paints, tyres and aviation are the pressure points and upstream oil the offset. The saving grace is that Asia is mixed rather than falling and DII buying has been absorbing FII supply, so this looks more like a grind lower than a rout. Positioning ahead of Friday's US CPI should keep conviction low and ranges tight; 23,500 is the level bulls need to defend.
As of 8:55 AM IST, 9 September 2026. Sources: Business Standard, Business Today, Goodreturns, Trading Economics, InvestingLive, Kiplinger, Yahoo Finance. All prices and index levels are as reported by these news sources, not live exchange data. Automated pre-market brief for discussion and education only — not investment advice. Verify before acting.
This article is for educational and informational purposes only. It is not financial advice, investment recommendation, or a solicitation to buy or sell securities. Investing involves significant risks. I am not a SEBI-registered investment advisor. Readers should consult their own financial advisor and conduct their own research before making any investment decisions.
Comments
Join the conversation
Sign in to join the conversation.
Follow replies, add your view, and take part in the discussion.
Sign in to commentLoading comments...