

Why did LiveWire (LVWR) nearly double today?
What happened
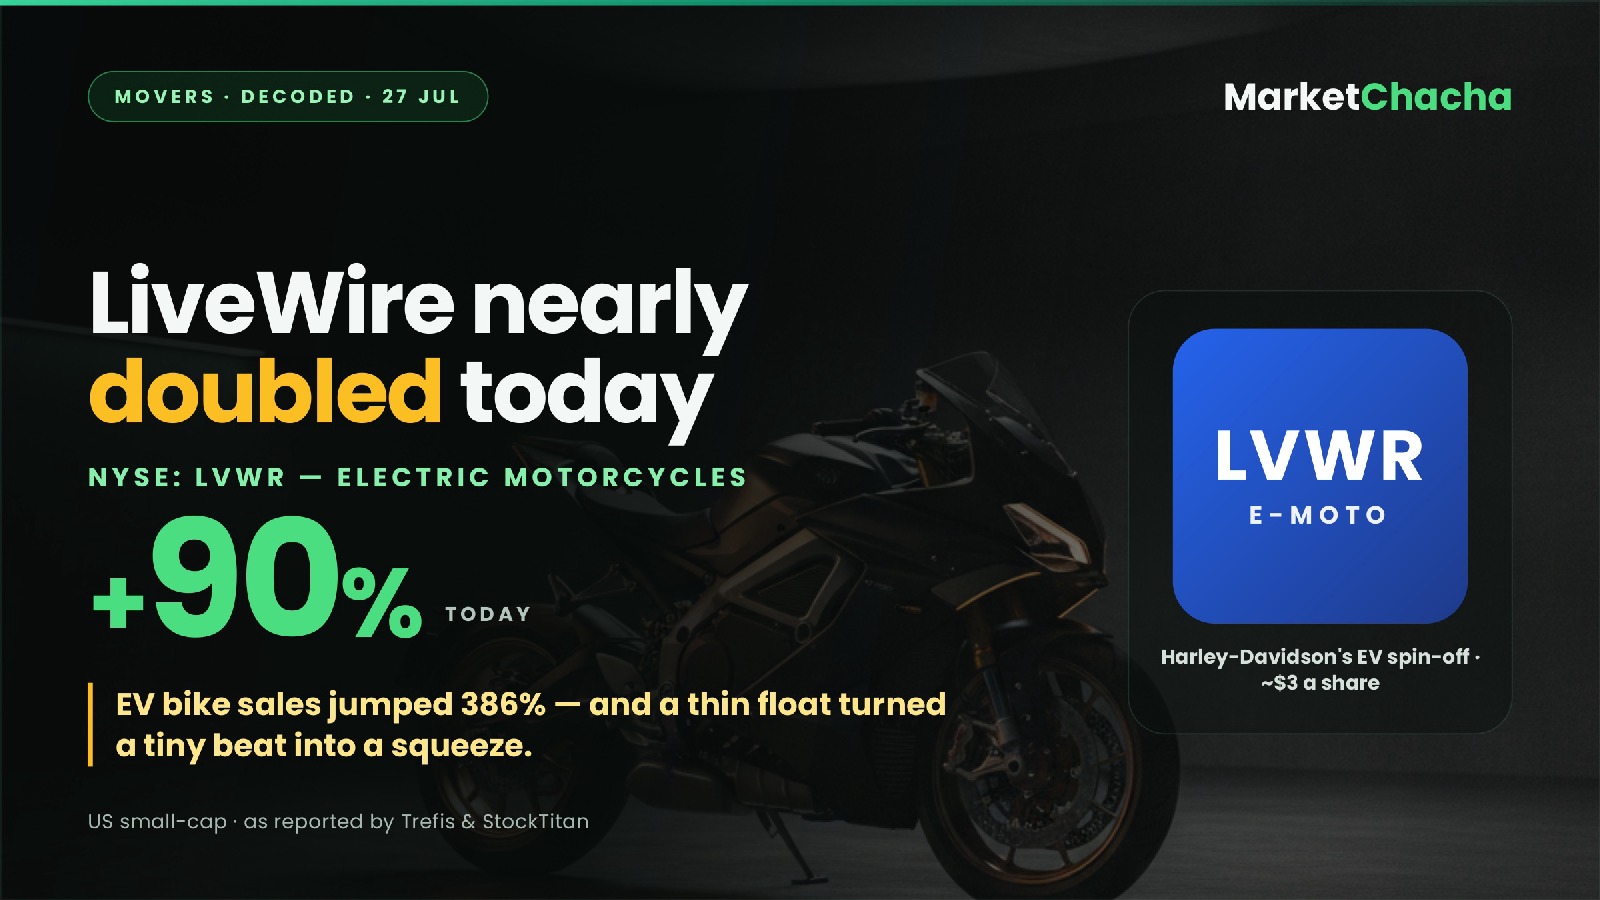
LiveWire, the electric-motorcycle maker spun out of Harley-Davidson, is having a wild session. The stock is up nearly 90% today (Trefis market-movers, July 27), extending a squeeze that began after Friday's Q2 results. A share that changed hands under a dollar last week is now trading around $3. This is a penny-sized micro-cap moving on huge volume, not a blue chip re-rating — but the numbers behind it are real, so it's worth understanding.
Why it moved
The trigger was LiveWire's Q2 2026 report. Revenue rose 55% year-on-year to $9.1 million, and the part the market cared about most: electric-motorcycle unit sales jumped 386% (to 267 bikes) as the cheaper S2 line and the STACYC kids' e-bike business both sold more. Management reaffirmed full-year guidance, said it has started production of the new S4 Honcho, and closed the acquisition of Dust Motorcycles to push into off-road. For a company the street had all but left for dead, "growth is accelerating and guidance held" was enough to light a fuse.
The size of the pop owes a lot to plumbing, not just fundamentals. Harley-Davidson still owns the majority of LiveWire, so the free float — the shares actually available to trade — is thin. When a rush of buyers (and short-sellers scrambling to cover) hits a tiny float, the price moves violently in both directions. That's the mechanism turning a solid-but-small revenue beat into a near-double.
The business
LiveWire isn't a pure motorcycle bet. It runs three pieces: premium electric motorcycles (the S2 Del Mar and now S4 Honcho), STACYC — electric balance bikes for kids, which has been its steadiest seller — and its own powertrain tech. Today's unit jump came from both the bikes and STACYC, so this is broader than one hero product. It still loses money everywhere: Q2 net loss was $18.2 million, and the company guides to a full-year operating loss of $70–80 million.
Is it expensive?
There's no P/E here — LiveWire doesn't earn a profit, so you value it on sales. At roughly $3 a share and about 205 million shares out, that's a market value near $600 million on a revenue base of only ~$35 million a year — around 17 times sales for a business burning cash. That's rich by any measure. For contrast, its own majority owner Harley-Davidson (NYSE: HOG) is profitable, trades on a P/E of about 13 and carries a ~$2.6 billion market cap (as reported by StockAnalysis). So today's move briefly values the tiny loss-making EV unit at a real fraction of the whole profitable parent — the tell that this is momentum, not a fundamentals re-pricing.
Who it touches
- Harley-Davidson (HOG): owns the majority stake, so a higher LiveWire mark flatters its holding — but it's small next to Harley's core cruiser business.
- Small-cap EV and short-squeeze names: thin-float momentum tends to travel in packs, so beaten-down EV micro-caps often twitch together on days like this.
- India read-across (thematic only): the story rewarding "EV two-wheeler units up sharply" echoes the debate around Ola Electric, Ather and the Bajaj Chetak / TVS iQube lines — different market, same question of whether volume growth can outrun the cash burn.
What to watch
The one thing that flips this fast: cash. With a guided $70–80 million operating loss this year and a share count that already funds losses through dilution, any equity raise into this spike would hit existing holders hard — and a squeeze that ran up on a thin float can unwind just as violently once forced buyers are done. Watch whether the next update shows the unit growth turning into a narrowing loss, or just more volume at a loss.
As of ~12:45 pm ET (10:15 pm IST), 27 Jul 2026. Sources: Trefis, StockTitan, GuruFocus. For discussion and education only — not investment advice. Verify before acting.
This article is for educational and informational purposes only. It is not financial advice, investment recommendation, or a solicitation to buy or sell securities. Investing involves significant risks. I am not a SEBI-registered investment advisor. Readers should consult their own financial advisor and conduct their own research before making any investment decisions.
Comments
Join the conversation
Sign in to join the conversation.
Follow replies, add your view, and take part in the discussion.
Sign in to commentLoading comments...