P

Personal Finance

c/personalfinance

Your money, end to end — budgeting, emergency funds, paying down debt, retirement (401k, IRA, NPS, PPF), taxes, and the first steps after your first salary. Plain-English explainers. Education only, never advice.

publicgeneralStarted Jul 202611 posts6 members
Log in to join

Join to post, ask questions, and follow the conversations that fit your market style.

Why join c/personalfinance?

Real conversations

Ask what you are missing and compare notes.

Focused and relevant

One community, one cleaner thread of discussion.

Learn and grow

Read first, then post when you have a view.

ranjeet_singh
4 weeks ago

Why is my paycheck smaller than my salary? Gross vs net pay, FICA and the W-4 explained

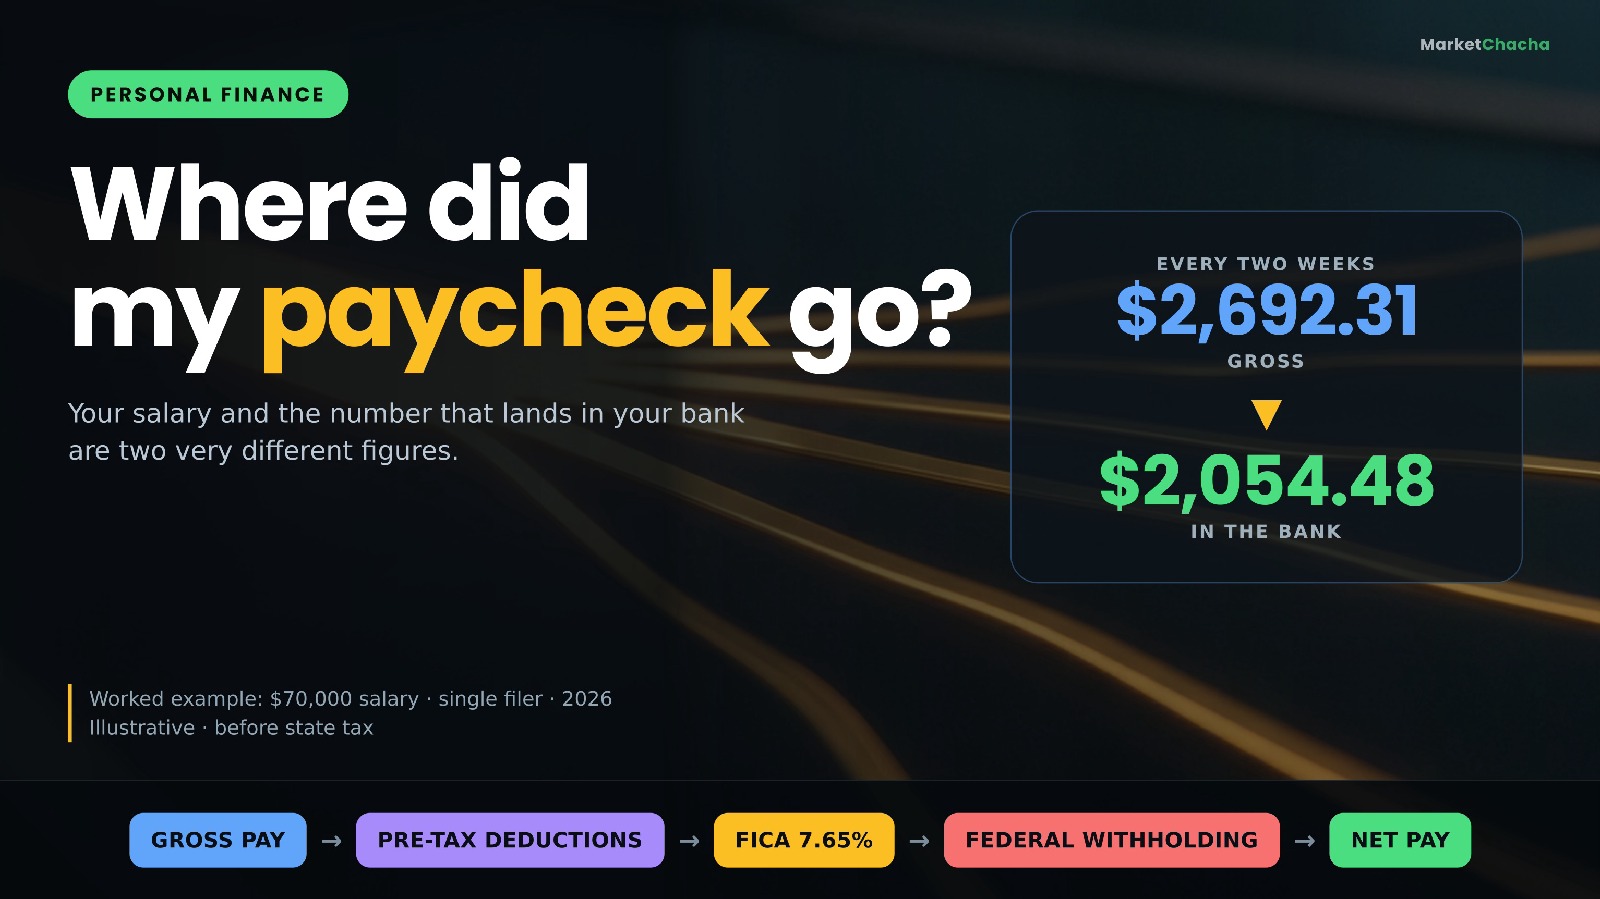
Your paycheck is smaller than your salary because four different things come out of it before the money reaches your bank: pre-tax deductions (retirement, health premiums), Social Security and Medicare tax (together called FICA, 7.65% of your wages), federal income tax withholding , and state and local tax where you live. Your salary is the number you negotiated; your take-home pay is what survives that list. For a single filer earning $70,000 in 2026 with modest benefits, roughly 76 cents of every dollar reaches the bank. Below: each deduction in order, a full example line by line, the one rule almost everyone gets wrong about “pre-tax” mone…
Why is my paycheck smaller than my salary? Gross vs net pay, FICA and the W-4 explained+2 more
0
ranjeet_singh
1 month ago

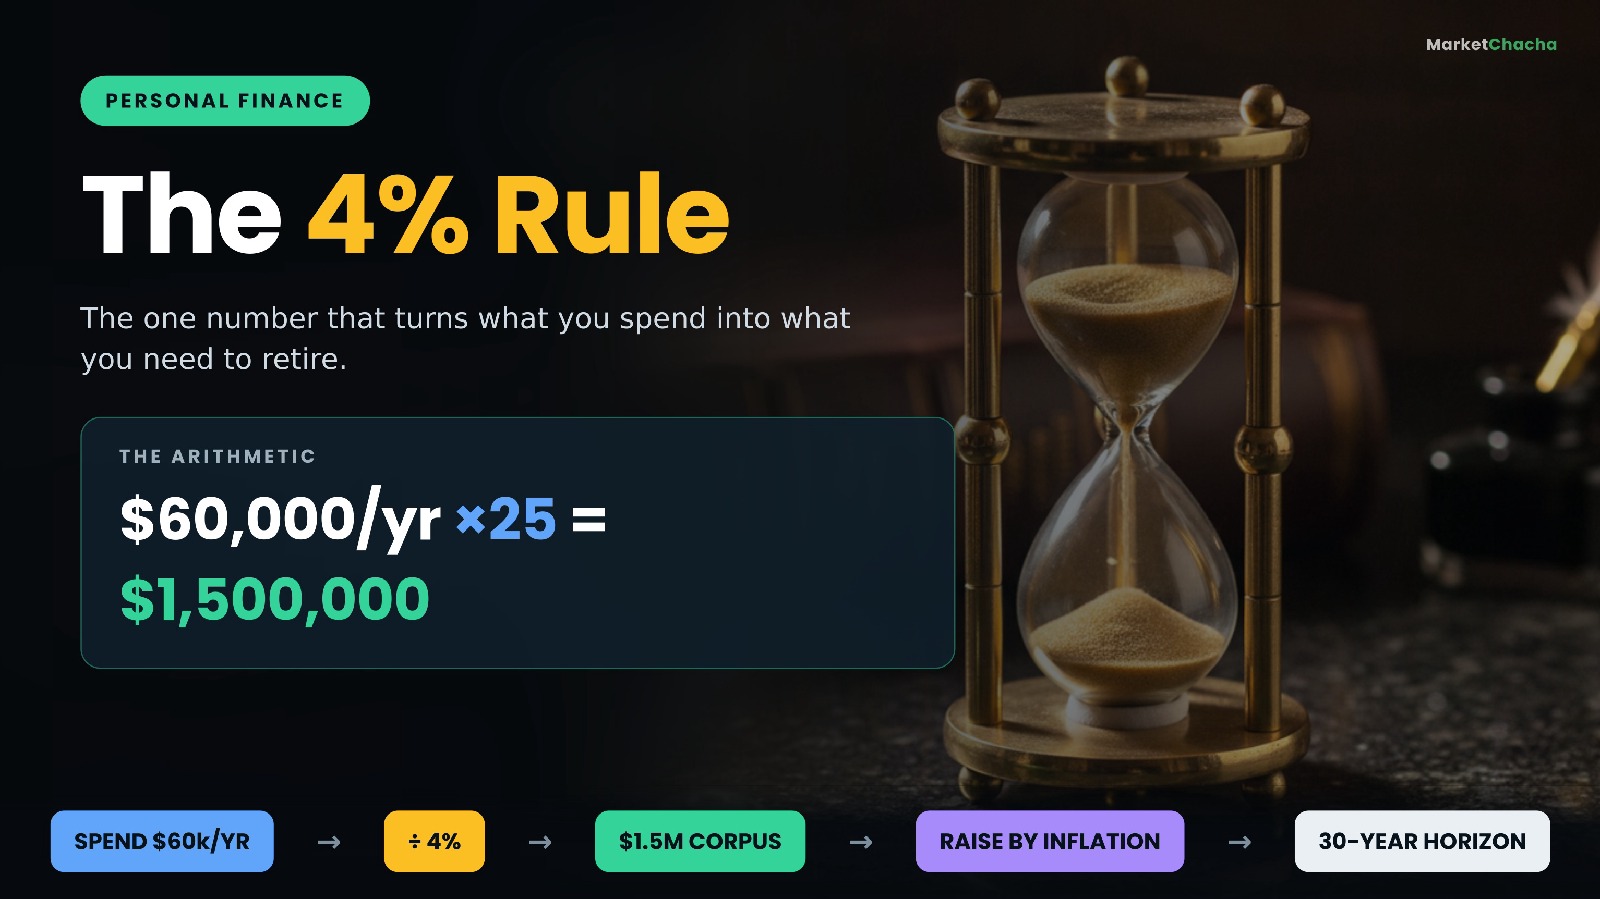
What is the 4% rule — and how much do you actually need to retire?

The 4% rule is a rough answer to the single hardest question in retirement planning: how much money do I need before I can stop working? It says that if you withdraw 4% of your portfolio in your first year of retirement, and then increase that same dollar amount each year only by inflation, a stock-and-bond portfolio has historically lasted about 30 years. Flip that around and you get the more famous version — the 25x rule : whatever you plan to spend from your portfolio each year, you need roughly 25 times that amount saved, because 1 ÷ 0.04 = 25. That is the definition. The rest of this guide covers where the number came from, the exact ari…

What is the 4% rule — and how much do you actually need to retire?+2 more
0
ranjeet_singh
1 month ago

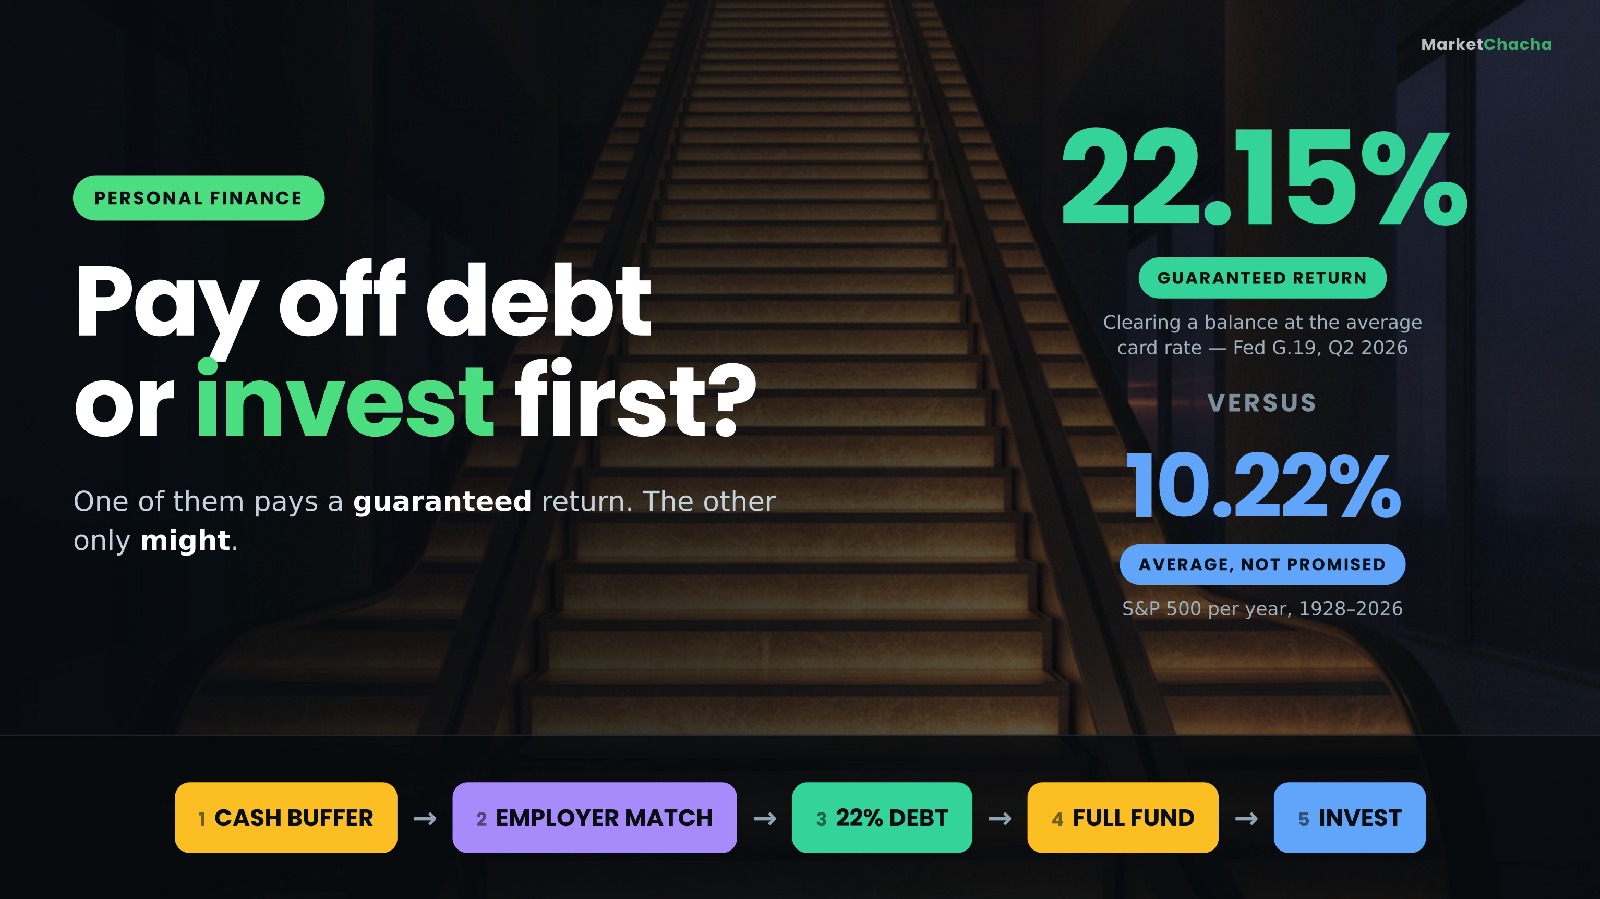
Should you pay off debt or invest first? The order to use your money, explained with the math

If you are carrying credit-card debt, pay it off before you invest. Clearing a balance at 22.15% is a guaranteed, tax-free 22.15% return, and nothing you can buy offers that with certainty. The one thing that jumps the queue is a full employer match on your 401(k), because 50 cents on every dollar is an instant 50% — bigger than the card rate, and gone forever if you skip that year. Everything else has an order too, and getting it right is worth more than picking good funds. This guide walks through that order step by step: what comes first, why, the arithmetic behind each decision, the places the rule genuinely bends, and how the same logic…

Should you pay off debt or invest first? The order to use your money, explained with the math+2 more
0
ranjeet_singh
2 months ago

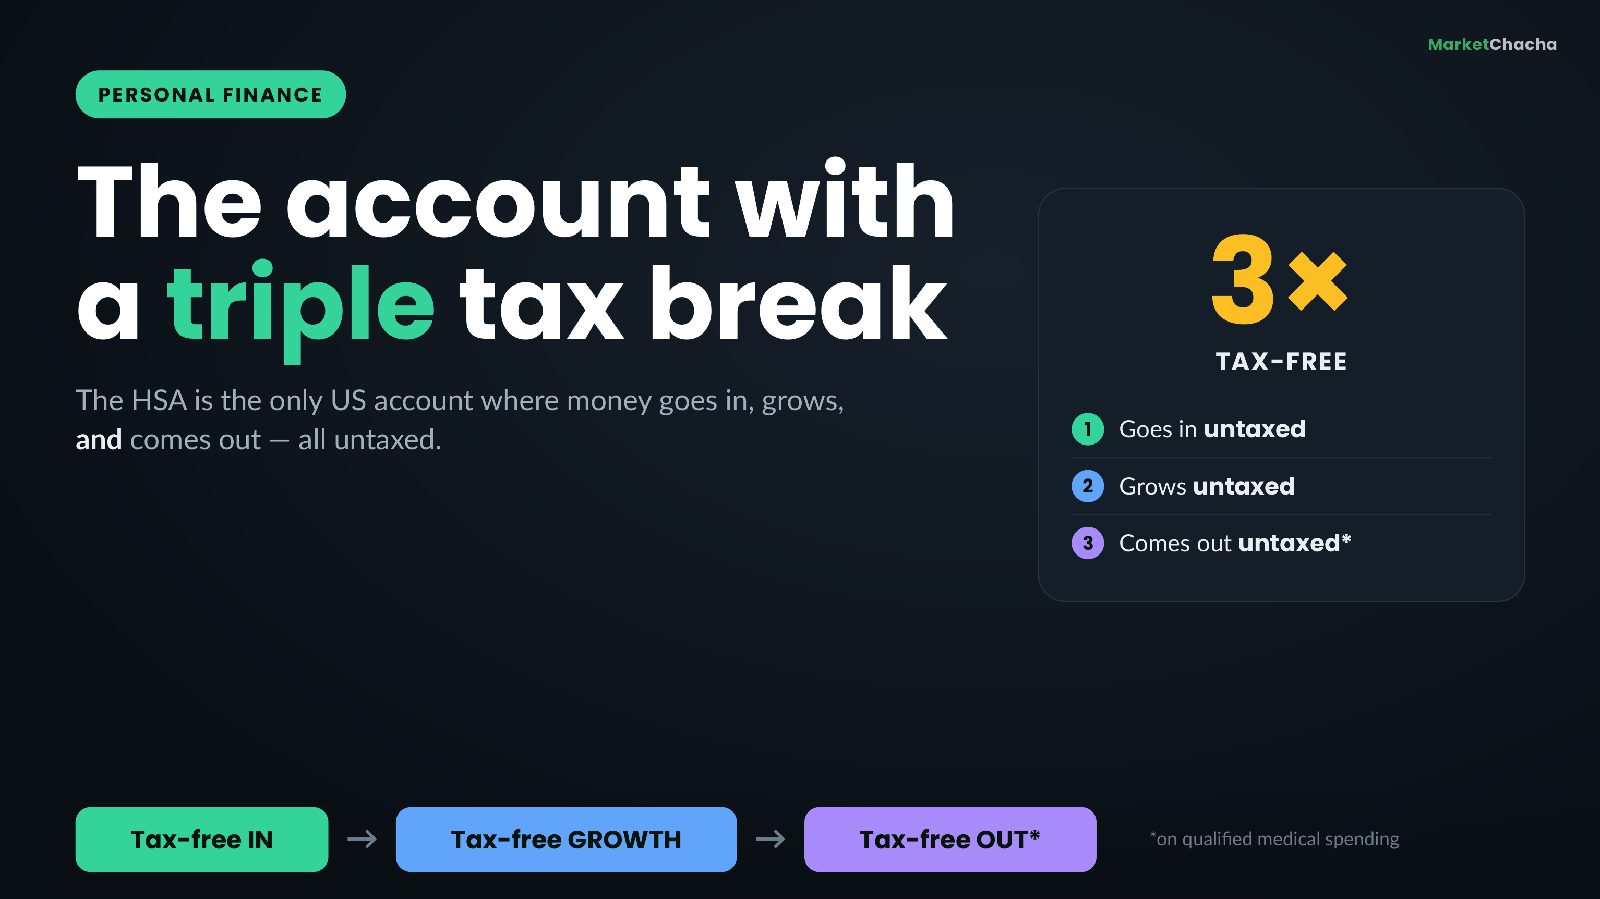
How does a Health Savings Account (HSA) work? The triple tax advantage explained

A Health Savings Account (HSA) is a tax-advantaged account you can open only if you have a qualifying high-deductible health plan (HDHP), and it is the single most tax-efficient account in the US system. It carries a "triple tax advantage" : the money goes in tax-free, grows tax-free, and comes out tax-free when you spend it on medical care. No other account — not a 401(k), not a Roth IRA — gets all three at once. This guide explains exactly how each of those three tax breaks works, walks through the arithmetic with a worked example, shows why an HSA can quietly become one of the best retirement accounts you own, tells you how to open…

How does a Health Savings Account (HSA) work? The triple tax advantage explained+2 more
0
ranjeet_singh
2 months ago

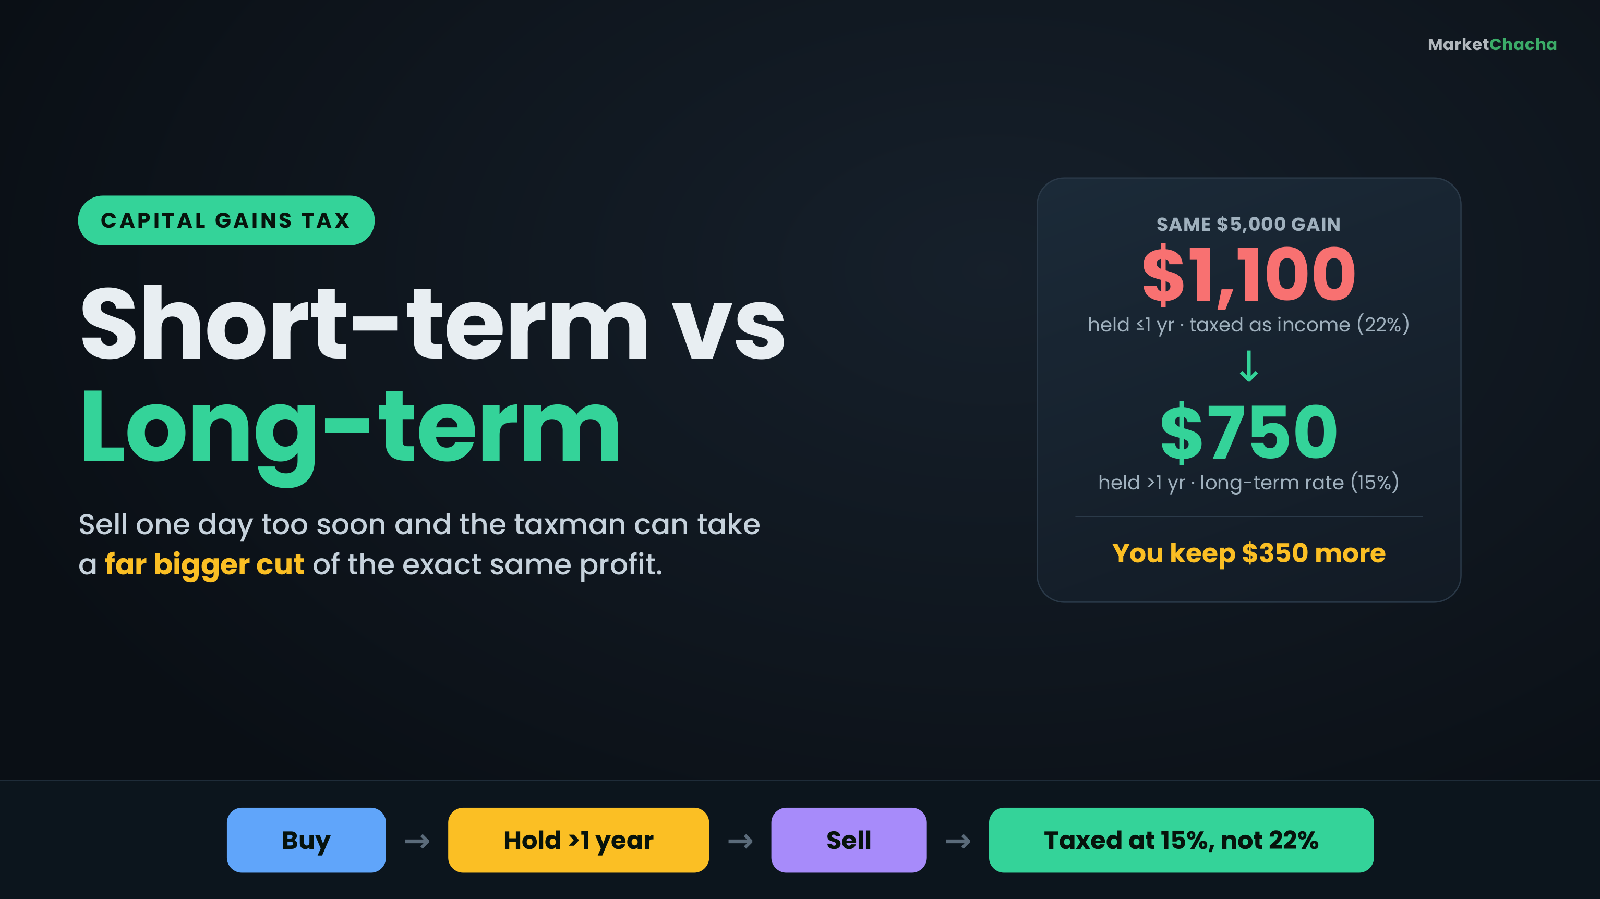
Short-term vs long-term capital gains tax: how are your investment profits actually taxed?

A capital gain is the profit you make when you sell an investment — a stock, a fund, a property — for more than you paid for it. How much tax you owe on that profit is decided mostly by one thing: how long you held the asset before selling . Hold it for one year or less and the gain is short-term , taxed at your ordinary income tax rate (10% to 37% in the US). Hold it for more than a year and the gain is long-term , taxed at a special, lower rate of 0%, 15% or 20%. That one distinction can mean hundreds or thousands of dollars on the exact same profit. This guide walks through what a capital gain actually is, the one-year line that changes yo…

Short-term vs long-term capital gains tax: how are your investment profits actually taxed?+2 more
1
ranjeet_singh
2 months ago

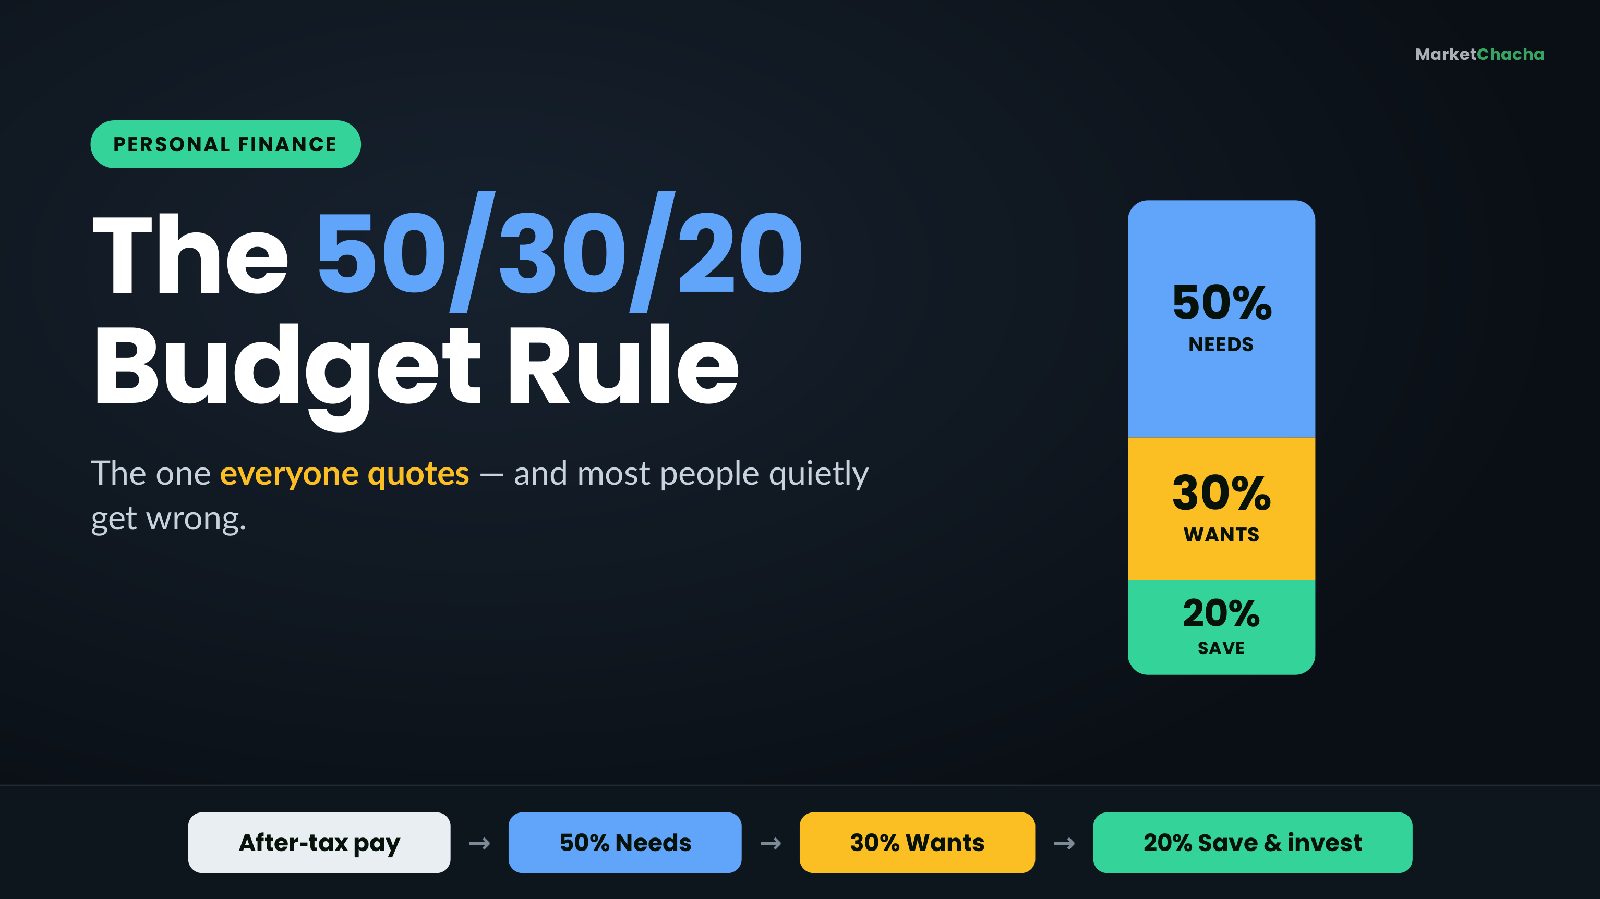
What is the 50/30/20 budget rule — and why do most people get it wrong?

The 50/30/20 rule is a simple way to split your take-home pay: send 50% to needs , 30% to wants , and 20% to savings and paying off debt . It was popularised by U.S. Senator (then Harvard bankruptcy professor) Elizabeth Warren and her daughter Amelia Warren Tyagi in their 2005 book All Your Worth: The Ultimate Lifetime Money Plan . The appeal is that you only have to track three buckets instead of forty line items — but that simplicity is exactly why most people quietly get it wrong. This guide walks through what the three buckets really contain, a full worked example with the arithmetic, how to set it up in ten minutes, where the rule breaks…

What is the 50/30/20 budget rule — and why do most people get it wrong?+2 more
0
ranjeet_singh
2 months ago

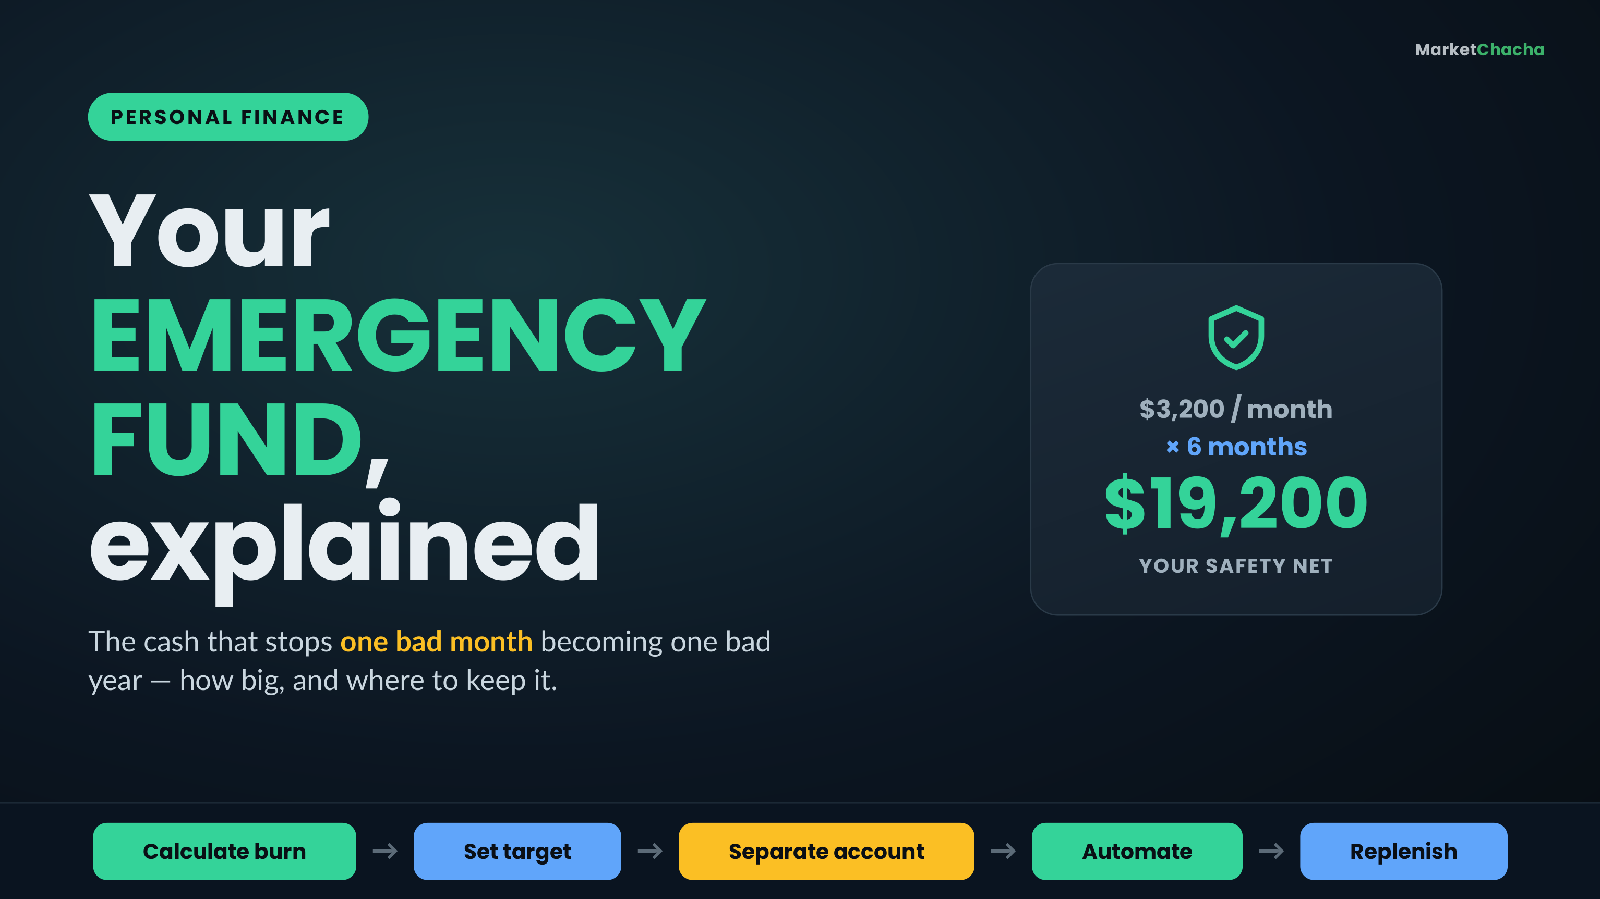
What is an emergency fund — how much do you actually need, and where should you keep it?

An emergency fund is a stash of cash you keep separate from your everyday money and can reach in a day or two, sized to cover your essential living costs for a few months. Its whole job is to absorb a sudden shock — a job loss, a medical bill, a car that dies, a broken boiler — so that shock doesn't force you into high-interest credit card debt or into selling your investments at the worst possible moment. The benchmark you'll hear everywhere is three to six months of essential expenses , but as you'll see, the right number is personal, and where you keep it matters almost as much as how big it is. This guide walks through what actually count…

What is an emergency fund — how much do you actually need, and where should you keep it?+2 more
1
ranjeet_singh
2 months ago

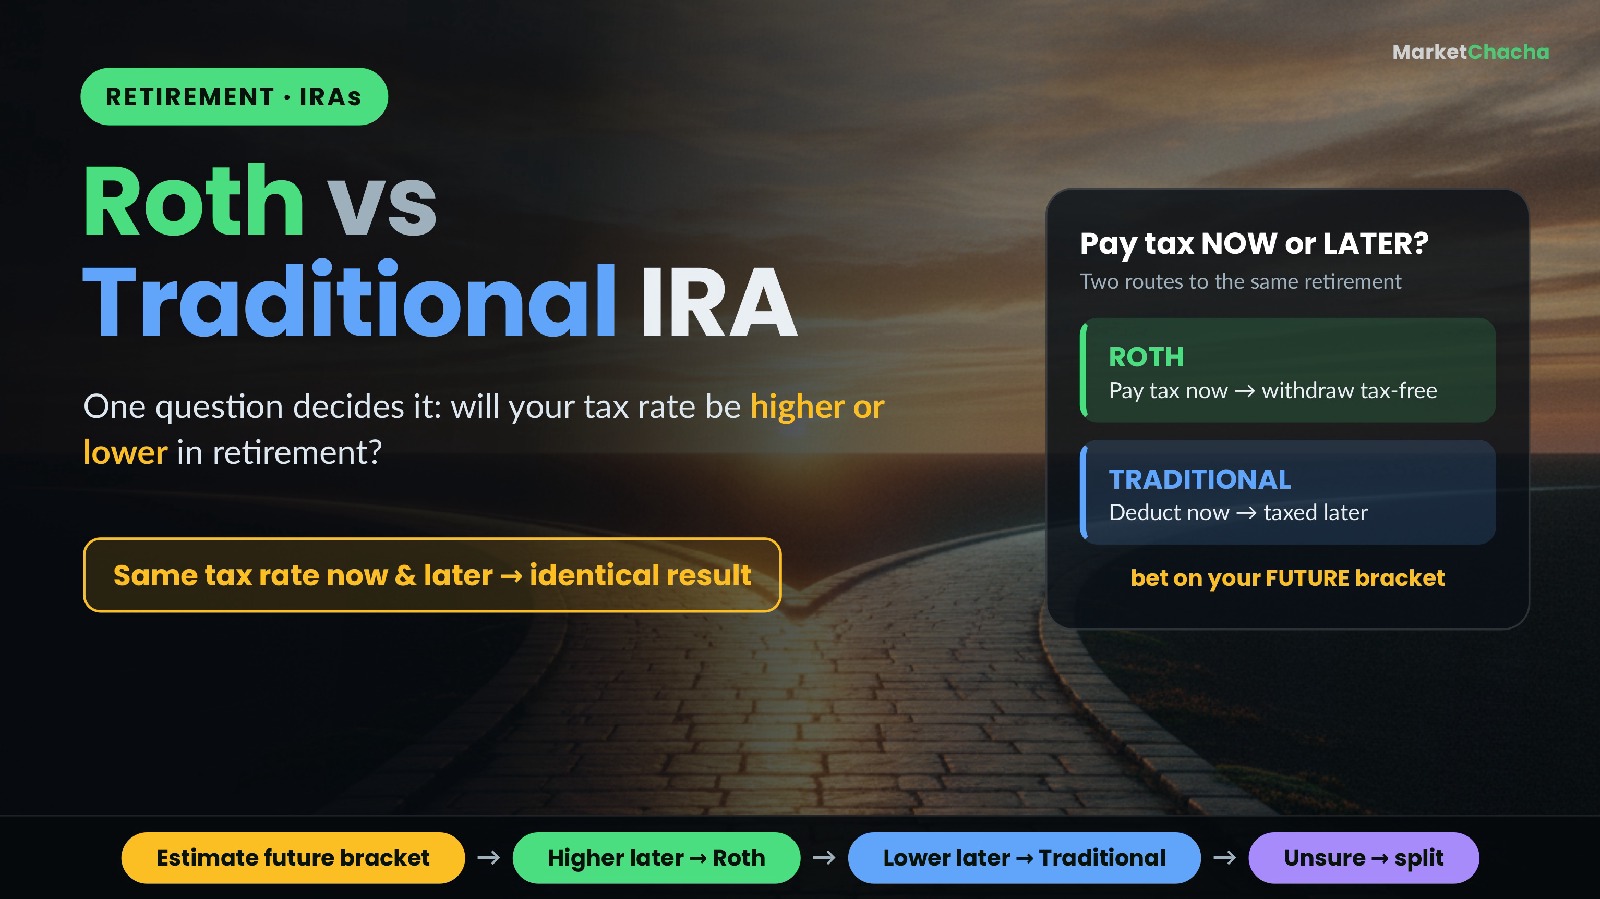
Roth vs Traditional IRA: which should you actually pick? (Beginner's guide with the math)

A Roth IRA and a Traditional IRA are both tax-advantaged retirement accounts you open yourself — the only real difference is when you pay the tax . With a Traditional IRA you usually get a tax deduction now and pay income tax later when you withdraw in retirement. With a Roth IRA you get no deduction today — you contribute money you have already paid tax on — but every dollar you withdraw in retirement, including all the growth, comes out completely tax-free. That single timing difference — tax now versus tax later — is the whole decision. This guide explains what each account is, the one question that actually decides which is better for you…

Roth vs Traditional IRA: which should you actually pick? (Beginner's guide with the math)+2 more
0
ranjeet_singh
3 months ago

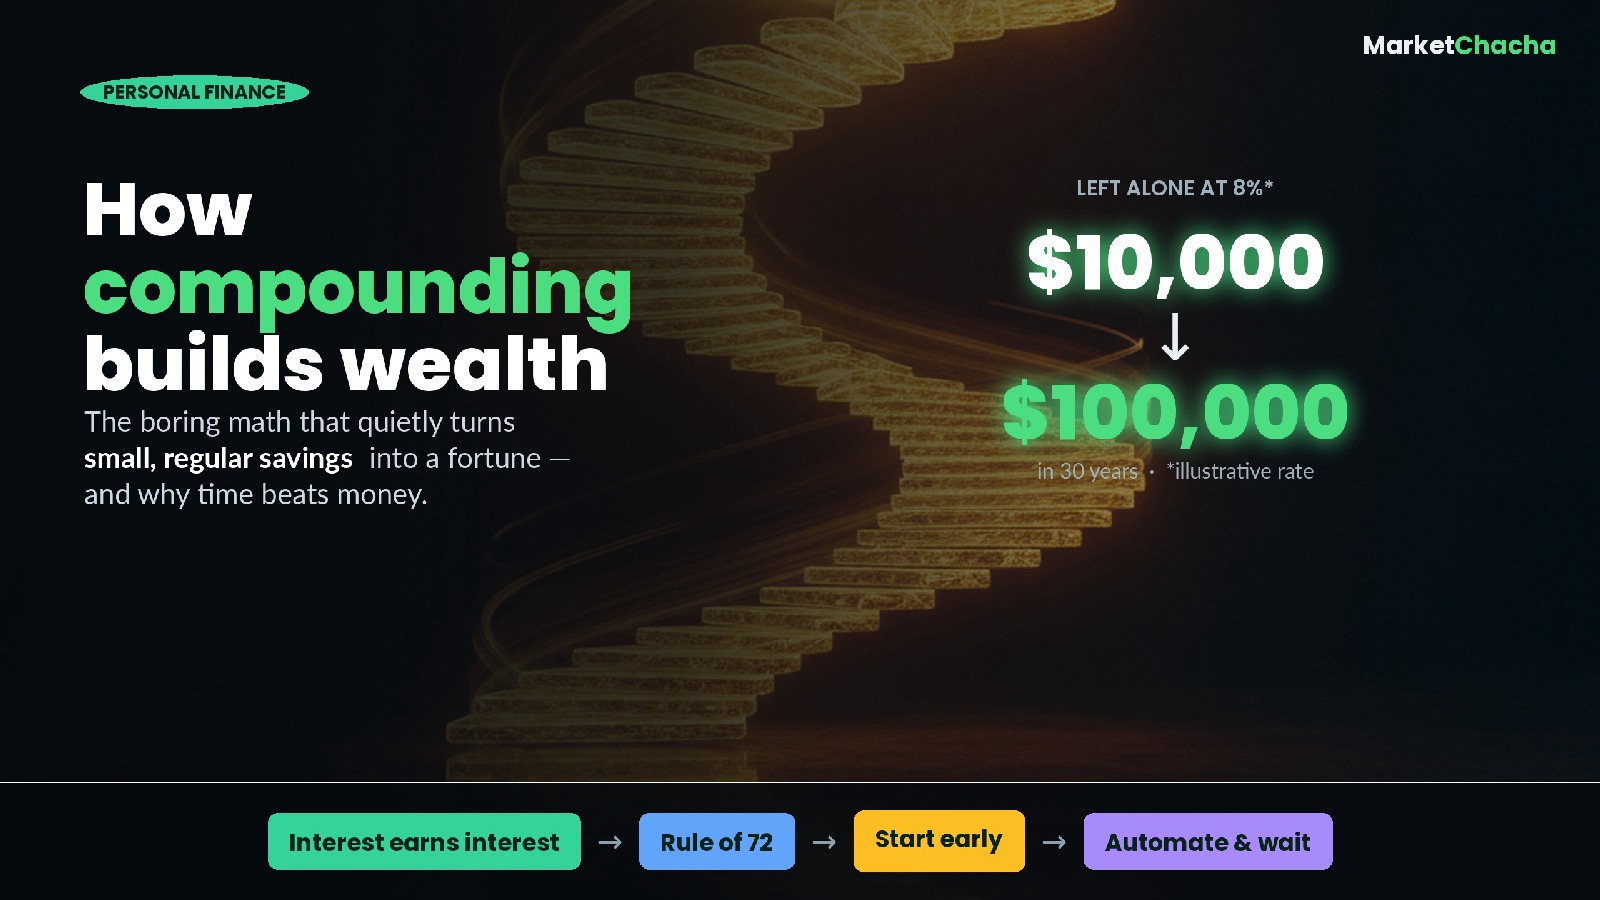
How does compounding actually build wealth? The simple math behind 'time in the market'

Compounding is the process where the returns your money earns start earning returns of their own. Instead of only your original savings working for you, last year's growth is added to the pile and grows too — so the balance builds slowly at first, then accelerates. Albert Einstein probably never actually called it the "eighth wonder of the world," but the math behind it is the single most important idea in personal finance, because it is what turns modest, boring, regular saving into real wealth over a lifetime. This guide explains exactly how compounding works, walks through the arithmetic step by step, shows why starting early beats…

How does compounding actually build wealth? The simple math behind 'time in the market'+2 more
1
ranjeet_singh
3 months ago

What is a 401(k) and how does the employer match actually work? (Beginner's guide)

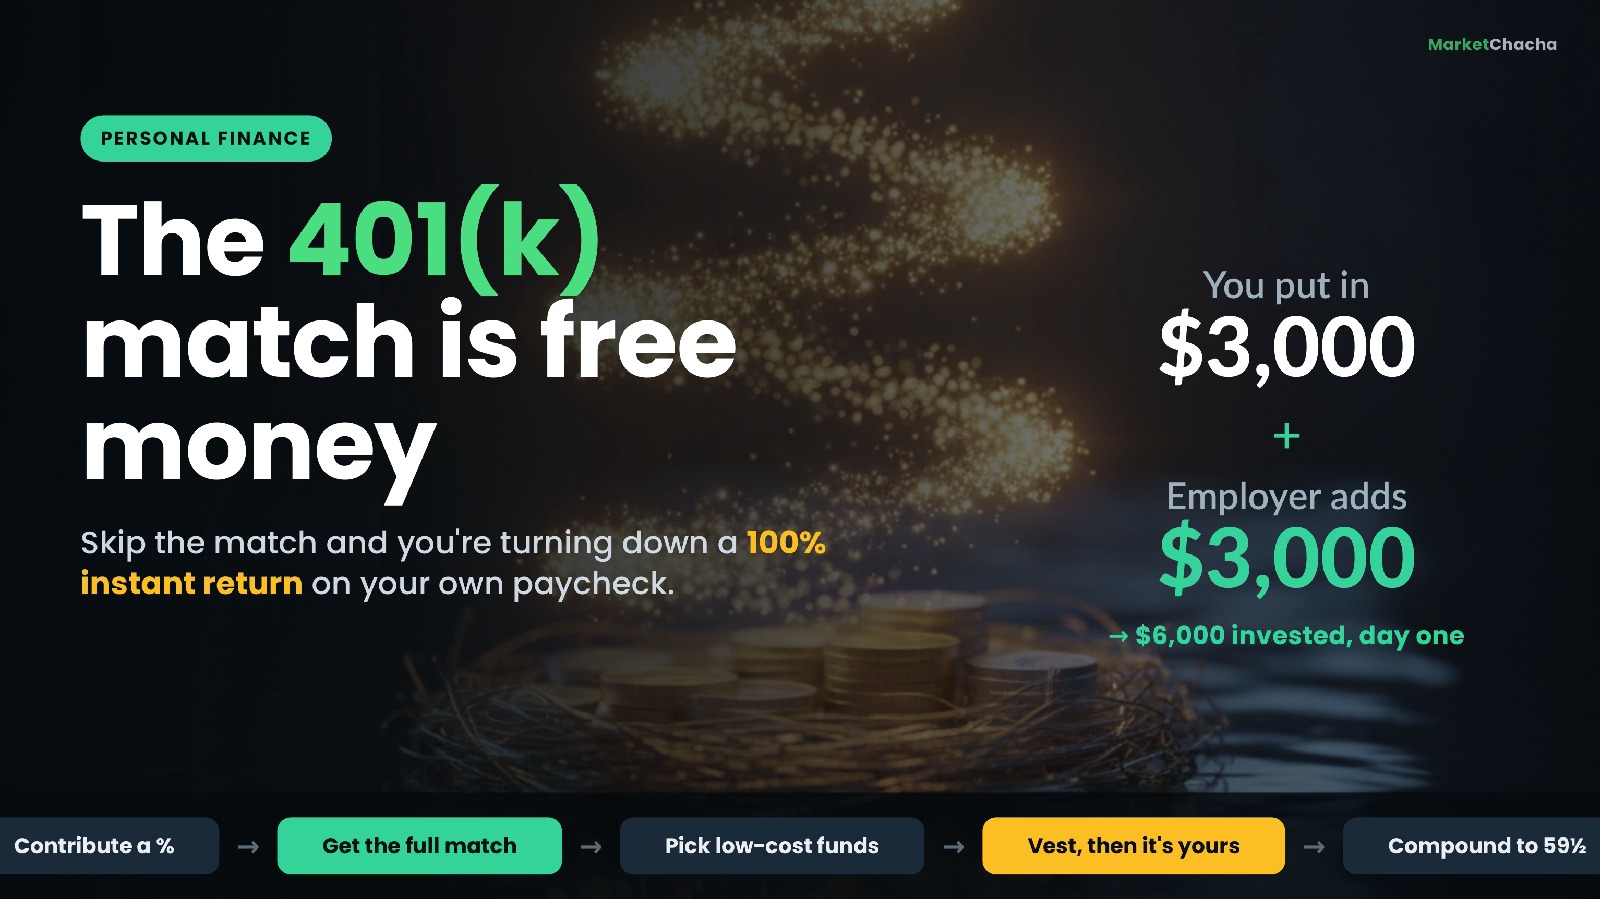
A 401(k) is a retirement savings account offered through your job, where money is taken straight from your paycheck and invested for the long term — and its single most valuable feature is the employer match : extra money your company adds to your account for free when you contribute. If your employer matches 100% of the first 5% you save, every dollar you put in is instantly met by a dollar from them. That is a 100% return before the market does anything , which is why skipping the match is widely considered the biggest avoidable mistake in personal finance. This guide explains, from scratch, what a 401(k) is, exactly how the match works, ho…

What is a 401(k) and how does the employer match actually work? (Beginner's guide)+2 more
1
ranjeet_singh
3 months ago

If I move into a higher tax bracket, do I take home less? Marginal vs effective tax rate explained

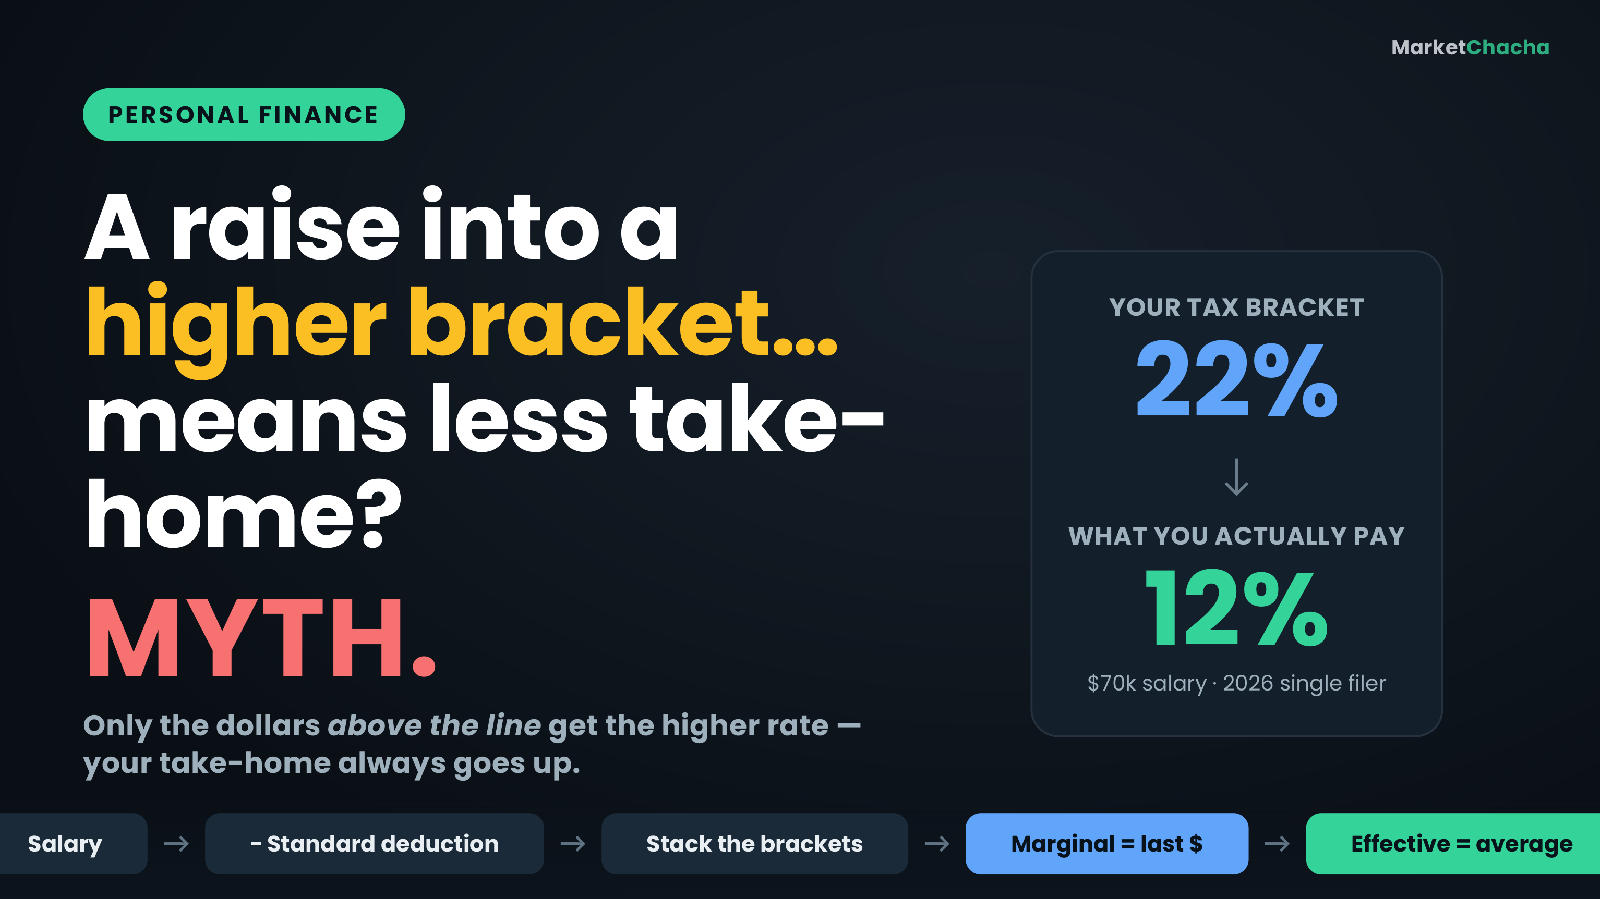
Your marginal tax rate is the rate charged on your last dollar of income; your effective tax rate is the total tax you pay divided by your total income. They are almost never the same number, and mixing them up is behind the most common tax myth in the world — the fear that earning a bit more, or "crossing into the next bracket," can leave you with less money in your pocket. It can't. This guide explains exactly why, with a full worked example using the official 2026 US federal brackets, the arithmetic of a pay raise, and a closing section on how the identical logic works in India. Marginal vs effective rate: the one-sentence differen…

If I move into a higher tax bracket, do I take home less? Marginal vs effective tax rate explained+2 more
1